Socket Mobile Narrows Its Loss On A Sequential Revenue Rebound, But A Thinning Balance Sheet Forces An Exit From NASDAQ
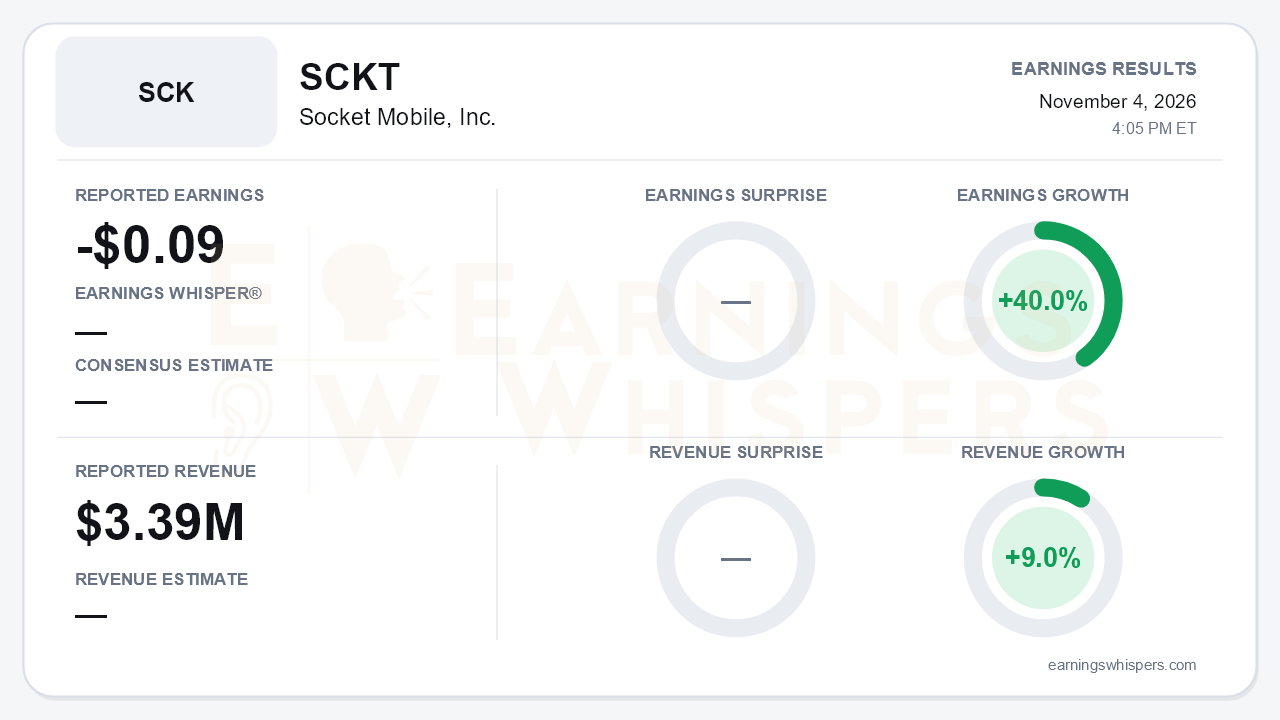
Socket Mobile delivered its best operating quarter of the year in the third quarter, but the balance sheet kept getting weaker, and that is the central tension. The company reported a loss of $0.09 per share on revenue of $3.39 million. Revenue rose 9.0% year over year, and earnings improved 40.0% from the prior-year loss of $0.15 per share. There was no consensus estimate or Earnings Whisper to measure against, so the quarter has to be judged on its trajectory. On that basis, the direction improved clearly. Revenue rose 12% sequentially from $3.0 million, which breaks a slide from $4.0 million in the fourth quarter of 2025 to $3.7 million in the first quarter and $3.0 million in the second. The net loss narrowed to $789,000 from $1.2 million a year earlier, and the per-share loss improved from $0.16 in the second quarter.
Most of the improvement came from cost cuts rather than demand. Gross margin recovered to 48.6% from 46.4% in the second quarter and 47.7% a year ago, though it remains below the 51.3% posted in the first quarter. The bigger lever was spending. Operating expenses fell to $2.3 million from $2.6 million in the prior quarter and $2.5 million a year ago. Sales and marketing dropped sharply to $600,000 from $935,000, and research and development slipped to $930,000. Management credited headcount reductions and AI-driven efficiencies. As a result, the operating loss nearly halved sequentially to $643,000, and management cited an adjusted EBITDA loss of $262,000, down from $745,000.
Two details temper the picture:
- **Rising overhead:** General and administrative expense rose to $761,000 from $577,000 a year earlier, even as other costs fell.
- **Lower year-to-date revenue:** Nine-month revenue of $10.1 million is still down from $11.1 million last year, so the quarter looks more like stabilization than a return to growth.
On the call, management's tone shifted from the second quarter's "not at all satisfied" to talk of a "march toward profitability." Executives still conceded they are not satisfied with revenue. The commercial pipeline offers some substance:
- **New partnerships:** The release names 3Eye Technologies, for Apple-based industrial frontline workflows, and Orda, for workplace dining ordering and self-checkout. The call materials render these as "3i Technologies" and "Orta," so the release spelling is likely correct.
- **Industrial wins:** These include a major construction equipment manufacturer, with flooring and automotive engagements also in progress. Industrial was about 10% of revenue in the second quarter.
Timing is the problem. Industrial deals that management expected to close in 2026 have slipped into the first half of 2027. That extends the "strong second-half build" first flagged back in the first quarter. The company again gave no formal guidance, so investors have only a narrative to underwrite.
The balance sheet is where bears have legitimate ammunition:
- **Shrinking cash:** Cash fell to $1.4 million from $1.6 million at June 30 and $2.0 million at year-end.
- **Note repayment:** The company repaid $575,000 of convertible notes, tied in Q&A to the note held by departed former CEO Kevin Mills.
- **Insider bridge loan:** To cover the gap, Socket took a $425,000, 10% secured bridge loan from Chairman Charlie Bass. This came after saying last quarter it would try to fund itself from operating cash. Another convertible note financing is pending.
- **Falling equity and NASDAQ exit:** Stockholders' equity shrank to $1.8 million from $4.3 million at year-end. That drop triggered an August NASDAQ notice for falling below the $2.5 million minimum. In response, the company is voluntarily moving to the OTCID market around November 19.
Management presents the move as a way to cut legal, compliance and listing costs. Investors should also expect reduced liquidity and visibility. Meanwhile, about $5.3 million of subordinated convertible notes, mostly related-party, still sits on a balance sheet with $11.8 million in total assets. Weighted shares outstanding have also risen about 4% year over year.
The market had already priced in a good deal of distress before this report. Shares opened at just $0.46 after the July report, far below the current 200-day moving average of $0.78. That gap points to a stock that has been in a sustained decline. No current investor sentiment reading or post-report price data was supplied, so it is unclear how the market received the operating improvement. The pending OTC transition is likely to weigh on trading dynamics regardless.
The bottom line is that Socket Mobile showed it can shrink losses quickly by cutting costs, and revenue may have found a floor. The investment case now depends less on quarterly margins and more on whether pipeline deals arrive before the cash does not. With operating losses still running and cash at $1.4 million, the company is leaning on insider financing. A visible step down to the OTC market and a slipped industrial timeline add to the pressure. The improvement is real, but the company's financial runway is now the variable that matters most.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-28 | |
| Oct-27 | |
| Aug-24 | |
| Aug-10 | |
| Aug-10 | |
| Aug-06 | |
| Aug-04 | |
| Jul-30 | |
| Jul-23 | |
| Jul-15 | |
| Jun-19 | |
| Jun-09 | |
| May-05 |
