1stDibs Tops Consensus But Misses The Whisper As Commission Cuts And Softer AOV Cloud A Cautious Q4 Outlook
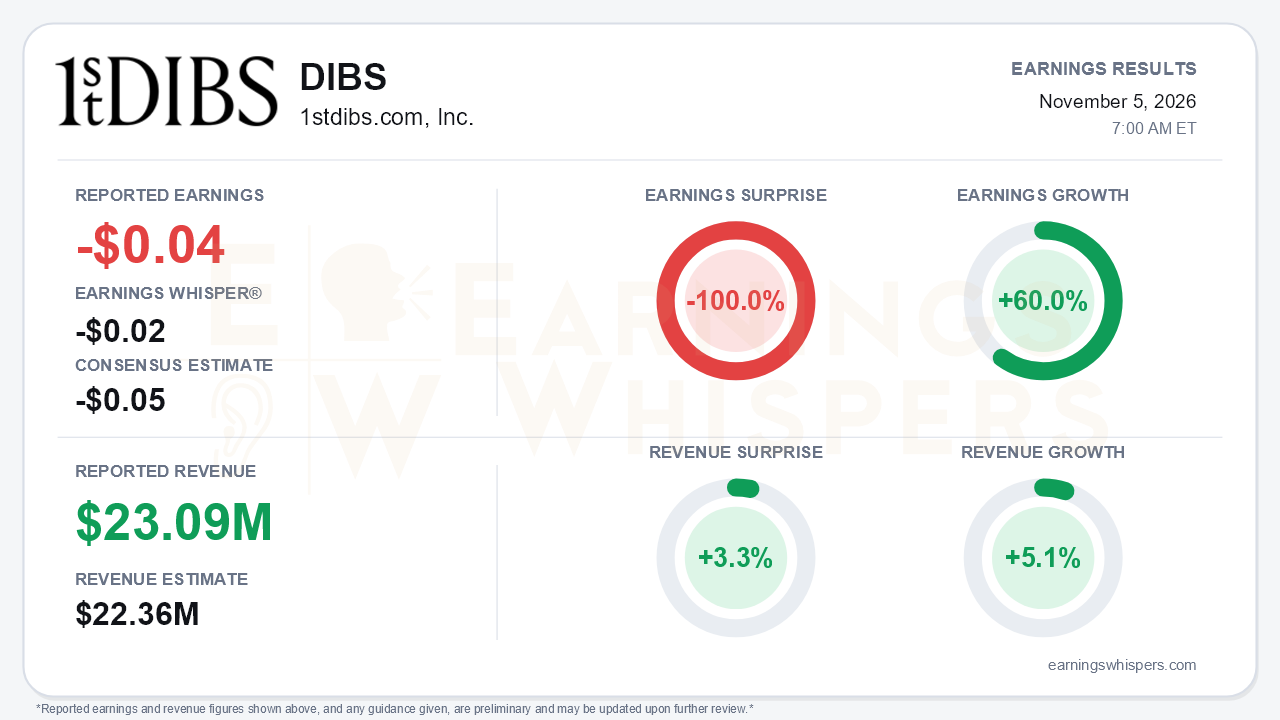
1stdibs.com (NASDAQ: DIBS) reported a third-quarter loss of $0.04 per share. That was a penny better than the -$0.05 consensus but well short of the -$0.02 Earnings Whisper number, a 100.0% miss against the expectation that mattered. Revenue of $23.09 million rose 5.1% from a year ago and beat the $22.36 million consensus by 3.3%, clearing the top of management's own $22.0-$22.9 million guide. Earnings improved 60.0% year over year as the GAAP net loss narrowed to $1.2 million from $3.5 million. The central tension is straightforward: the quarter showed real operating progress, but GMV growth slowed, and fourth-quarter guidance points to flat-to-lower revenue just as the stock ran into the report near its highs.
The quality of the improvement deserves scrutiny. Gross profit grew only 3%, and gross margin slipped to 73.2% from 74.3%. Most of the bottom-line gain came from expense cuts rather than revenue leverage. Sales and marketing fell to $5.3 million from $8.0 million, a roughly one-third reduction, while technology development spending rose. That lifted adjusted EBITDA to $1.0 million, a 4.5% margin, versus a -1% to +2% guide and a negative margin a year ago. It marked a fourth straight positive quarter. Per-share results also benefited from a smaller share base: the company has spent $20.7 million on buybacks this year, cutting weighted shares by about 7%. Lower interest income partially offset those gains. Cash generation was a genuine bright spot. Free cash flow was $2.9 million in the quarter even after an approximately $2.3 million hit from a payment-processor reclassification. Cash and investments stood at $69.0 million, and the board added a fresh $5 million repurchase authorization.
Underneath the headline, the demand picture improved but did not accelerate. Orders grew 1%, the first year-over-year increase since the fourth quarter of 2024, after falling 12% in the first quarter. Conversion rose for a twelfth straight quarter, and active buyers ticked up 1% sequentially to about 58,200. Year over year, however, active buyers were still down 8%. GMV rose 4% to $92.6 million, but that slowed from 7% growth in the second quarter. Average order value growth collapsed from +10% to +2%, and management said quarter-to-date fourth-quarter AOV is down low single digits. Management's tone was more confident. It argued the company is taking share in a high-end furniture market still declining mid-single digits, but the growth engine is clearly shifting from ticket size to transaction count.
The forward story now hinges on a deliberate trade-off. In October, the company cut commissions on select iconic jewelry and watch brands and all handbags, roughly 7% of GMV, to accelerate those categories. The cost shows up immediately in guidance:
- **GMV:** $89-$95 million, or -1% to +5%.
- **Revenue:** $22.2-$23.4 million, or -3% to +2%, below consensus.
- **Adjusted EBITDA margin:** 1%-4%, below the roughly 6% delivered a year earlier.
- **Gross margin:** expected toward the low end of the 72%-74% range.
Management reaffirmed its full-year framework of GMV and revenue growth with positive adjusted EBITDA, but bears have legitimate ammunition in a near-term take-rate squeeze layered on falling AOV. Supporting catalysts include sponsored listings revenue up more than 35%, a product feed submitted to ChatGPT, and an AI chatbot now handling about 25% of chat inquiries. Adding another variable, Bradford Shellhammer succeeds David Rosenblatt as CEO on January 1, 2027, with Rosenblatt moving to executive chair.
The market setup is more complicated than the consensus beat implies. Investor sentiment improved meaningfully heading into the report, rising from 0.12 to 0.28. It remains moderately positive rather than euphoric. The stock reflected that shift: shares closed at $5.56 on the eve of the release, up 11.2% from the open after the prior report and 15.2% above the 200-day moving average. They were also just 0.4% below an inter-earnings high set that same day. Notably, that run came quickly. Shares sat at $3.55 as recently as October 14, so the stock had rallied about 57% in three weeks and entered earnings priced for upside. The elevated whisper number captured that optimism. Earnings Whispers trend readings are mostly positive on momentum and AVWAP, but the sequential growth trend is negative, consistent with the GMV slowdown.
The bottom line is that 1stDibs delivered a cleaner, more profitable quarter, with orders back in growth and cash flow positive. However, the gains leaned heavily on marketing cuts and buybacks, and the Q4 outlook trades near-term revenue and margin for category growth that has yet to be proven. After a sharp pre-report rally, missing the whisper and guiding revenue below estimates leaves the stock exposed until the commission strategy and the new CEO show they can re-accelerate GMV.
Read our earnings preview for 1stdibs.com, Inc.: https://www.earningswhispers.com/article/DIBS/22081
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 10 hours | |
| 13 hours | |
| 14 hours | |
| Oct-28 | |
| Oct-13 | |
| Oct-06 | |
| Aug-13 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-28 | |
| Jul-14 | |
| May-20 | |
| May-13 | |
| May-12 |
