Collegium Beats On ADHD Strength, But Pain Erosion And Heavier Spending Keep Earnings Shrinking
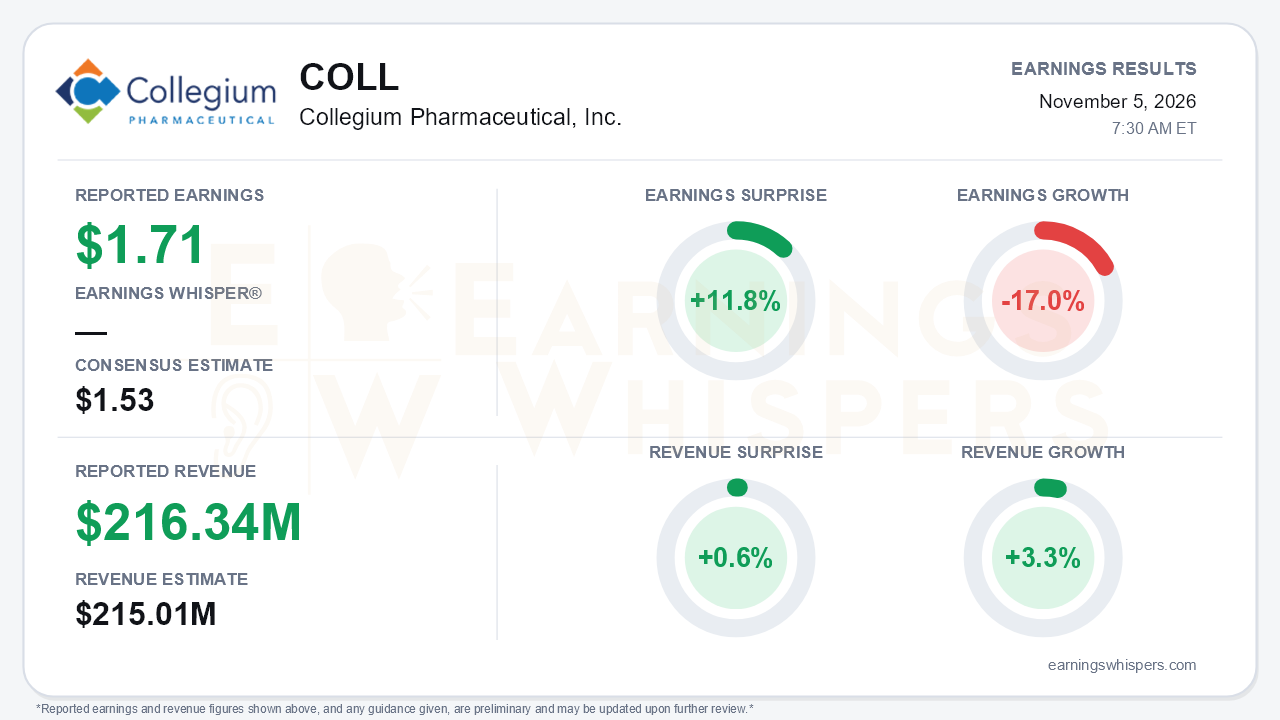
Collegium Pharmaceutical cleared a low bar in the third quarter. It reported earnings of $1.71 per share on revenue of $216.34 million, beating the $1.53 consensus by 11.8% and edging past revenue expectations by 0.6%. The beat does not change the underlying direction, though. Earnings fell 17.0% year over year, and revenue growth slowed to 3.3%. That compares with roughly 6% growth in the second quarter and 9% in the first. The ADHD business is accelerating and the pain portfolio is eroding, and the quarter showed that the first is not yet growing fast enough to offset the second. That is the central tension.
The quality of the quarter deserves scrutiny. The company's own non-GAAP adjusted EPS was $1.96, which differs from Earnings Whispers' normalized $1.71. Either way, profit fell from the prior-year quarter's $2.25 adjusted figure. The GAAP picture is weaker:
- **Pretax income** fell to $7.9 million from $43.4 million.
- **GAAP diluted EPS** of $0.60 was supported by a $13.9 million tax benefit. The company excluded a $21.0 million discrete deferred tax benefit from its adjusted results.
- **Adjusted EBITDA** declined 9% to $121.6 million. It had grown 8% in the second quarter.
- **Adjusted operating expenses** rose 25% to $69.4 million as Collegium expanded ADHD commercial efforts around back-to-school.
- **GAAP operating expenses** absorbed $11.0 million in litigation charges and $6.7 million in acquisition costs.
- **Cost of revenue** included a $9.7 million inventory step-up tied to the AZSTARYS acquisition.
The ADHD numbers are the reason the growth story still holds together. JORNAY PM delivered record net revenue of $51.9 million, up 24% year over year. That continues a clear sequential climb from $38.9 million in the first quarter and $46.1 million in the second. On the call, management cited several supporting trends:
- Prescription growth accelerated to 16% from 13.1% in the second quarter.
- Prescribers reached nearly 33,000.
- Share of branded long-acting methylphenidate climbed to roughly 30%.
- Adult prescriptions rose 27%.
- New-to-brand prescriptions grew 22% in September, with momentum accelerating into October.
AZSTARYS contributed $26.5 million in its first full quarter under Collegium ownership. Its prescriptions grew about 2%, reversing the decline it posted in 2025, and gross-to-net moved to 73.4% from 74.1%, which management described as an improvement with more opportunity ahead. ADHD now accounts for more than 36% of revenue, up from 19% a year ago.
The pain business is where bears have legitimate ammunition. Pain revenue fell 18% year over year to $138.0 million, down from $154.6 million in the first quarter.
- **Nucynta** dropped 44%, a sharper decline than the second quarter's 24%, as authorized-generic pricing bit and the Hikma profit share slipped to $4.2 million from $5.1 million.
- **Xtampza** fell 9%.
- **Belbuca** was roughly flat after growing about 10% in the second quarter.
Belbuca also faces potential generic competition from Teva after a January 23, 2027 settlement date. Management said it has seen no signals of a launch yet, but the risk remains an overhang. There are offsets on the formulary front. Belbuca gains access to 9 million additional covered lives in the fourth quarter. Xtampza secures an exclusive position with a large payer covering about 15% of lives starting January 1, 2027.
Guidance was reaffirmed across the board:
- Product revenue of $825 million to $855 million
- Adjusted EBITDA of $445 million to $470 million
- JORNAY PM revenue of $190 million to $200 million
- AZSTARYS revenue of $65 million to $75 million
That reaffirmation follows the second quarter, when the company trimmed its EBITDA range even as it raised revenue for AZSTARYS. Based on nine-month results, the range implies fourth-quarter adjusted EBITDA of roughly $106 million to $131 million, which leaves room for continued investment. It also implies JORNAY revenue of about $53 million to $63 million, so the record pace has to continue.
The balance sheet has changed meaningfully. Cash and securities fell to $144.8 million from about $387 million at year-end, and term debt rose to $842.5 million to fund the acquisition. Even so, management reported net leverage edging down to about 2.0x. It launched a $50 million accelerated share repurchase, expected to settle by year-end, with $100 million of authorization remaining.
The market had already priced in considerable skepticism. Shares opened at $31.67 after the August report, which also marked the inter-earnings high of $33.03. Since then the stock has fallen 25.3% to $23.67. It hit a 52-week low of $21.43 on October 1 and entered this report just 10.5% above that level and 28.2% below its 200-day moving average. Investor sentiment was essentially unchanged and mildly positive, ticking up to 0.18 from 0.17. The Earnings Whispers trend readings are split: sequential growth is positive, while price and AVWAP trends remain negative. That split mirrors the divergence between improving ADHD operations and the stock's deteriorating price action.
The bottom line is that Collegium delivered a clean beat and a credible ADHD growth narrative. It also delivered another quarter of shrinking earnings, decelerating total revenue and accelerating pain erosion. Reaffirmed guidance and the buyback give the company some cover. Rebuilding confidence, however, likely requires evidence that ADHD growth can outrun Nucynta's decline and absorb the Belbuca generic risk without further margin compression.
Read our earnings preview for Collegium Pharmaceutical, Inc.: https://www.earningswhispers.com/article/COLL/22073
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 13 hours | |
| 15 hours | |
| 16 hours | |
| Oct-29 | |
| Oct-28 | |
| Oct-22 | |
| Oct-21 | |
| Oct-06 | |
| Sep-08 | |
| Aug-13 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-23 | |
| Jul-20 |
