Celsius Beats On Alani Nu's Record Quarter, But Gross Margins Slide Again And The Recovery Timeline Slips
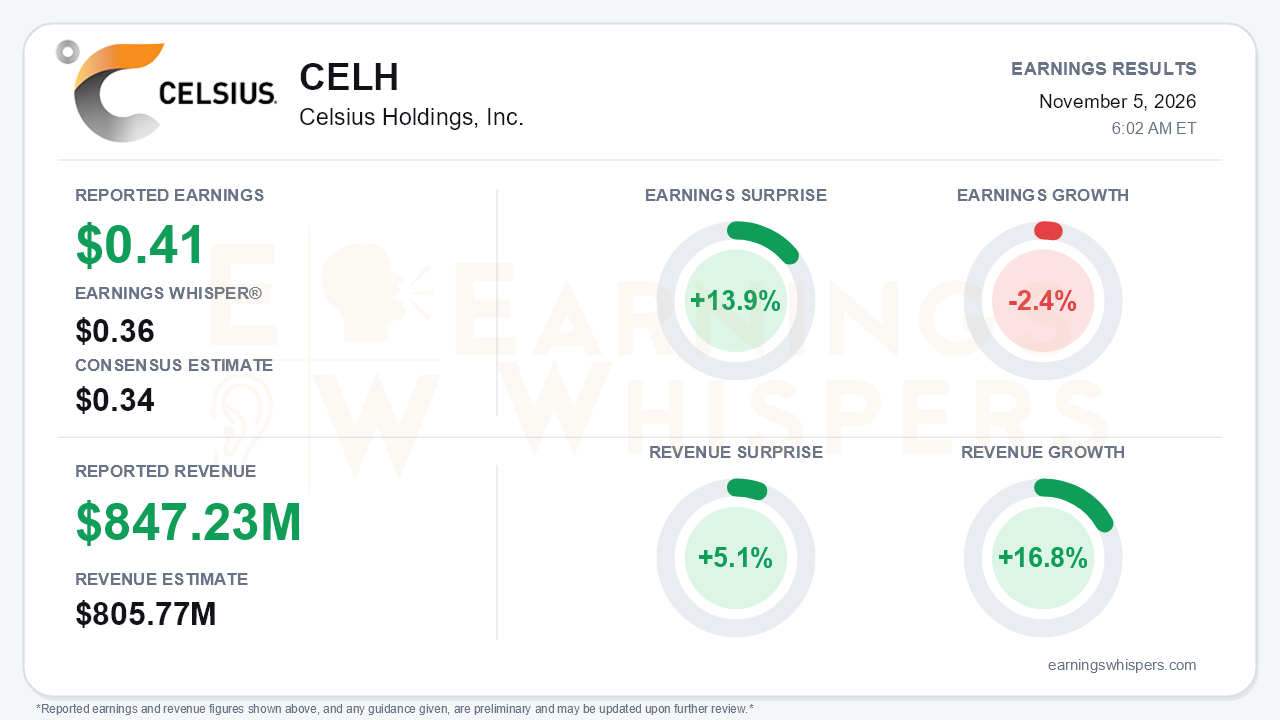
Celsius Holdings delivered a clean-looking third-quarter beat. Adjusted earnings of $0.41 per share topped the $0.34 consensus by 13.9% and cleared the $0.36 Earnings Whisper number. Record revenue of $847.23 million beat expectations by 5.1% and grew 16.8% year over year, a clear acceleration from roughly 11% growth in the second quarter. The headline masks a less comfortable trend, however. Adjusted earnings fell 2.4% from a year ago, gross margin dropped for a third straight quarter, and management again pushed back its timeline for margin recovery. The central tension is that Celsius is selling more product while earning less on each dollar of it.
The quality of the beat deserves scrutiny. Management said roughly $20 million to $25 million of shipments were pulled from the fourth quarter into the third. That accounts for about half of the revenue upside versus consensus. Gross margin fell to 46.8%, down from 48.1% in Q2 and 51.3% a year earlier. The company cited aluminum and fuel inflation and a heavier mix of DSD sales, which carry higher trade investment and billbacks. Adjusted EBITDA slipped 3% to $198.6 million, and adjusted EBITDA margin compressed from 28.4% to 23.4%. On a GAAP basis, the swing from a $(0.27) loss to $0.39 of diluted EPS looks dramatic. Most of it reflects lapping a $246.7 million distributor termination charge in the prior-year quarter, not a step change in operating profitability. One balance-sheet line stands out: accrued promotional allowances rose to $479 million from $308 million at year-end, which fits management's acknowledgment that trade spend as a share of gross sales ticked up again.
Beneath the consolidated numbers, the portfolio is increasingly a two-speed story. Alani Nu is carrying the company. Its net sales rose about 24% to $410.1 million, accelerating from roughly 21% in Q2, and retail scans climbed nearly 58%. The Witch's Brew limited-time offering generated more than $130 million in retail sales, the largest LTO in portfolio history, and core Alani scans were still up about 50% excluding it. The namesake CELSIUS brand moved the other way. Revenue fell about 6% to $356.8 million, and scan declines deepened from roughly 2% in Q2 to 7%. U.S. orders continue to trail scans. Rockstar improved sequentially to about $80 million from $67 million, although the release attributes part of that to Canadian order timing. Portfolio dollar share edged up to roughly 21%. International momentum is real but reported inconsistently: the release cites 78% CELSIUS international growth to $41.0 million, while the call referenced non-U.S. growth of 56%, likely reflecting different geographic definitions.
The forward-looking messaging leaned cautious. Management now frames full-year gross margin in the "high 40s." Return to the low 50s will take "longer than anticipated," after earlier targets of the second half of 2026 and then a Q3/Q4 stair-step. Fourth-quarter reported growth is guided below the year-to-date pace because of the pull-forward and a roughly $25 million prior-year inventory benefit that will not recur. Fourth-quarter trade costs will also be higher on full Alani DSD economics. The company also lost its Chief Supply Chain Officer, Paul Storey, and supply chain is under interim leadership just as cost initiatives are supposed to mature. Buybacks slowed to $44.5 million from about $100 million in Q2.
On the catalyst side, the call preserved a credible growth narrative:
- a new brand-led structure with Alex Zigliara leading CELSIUS;
- an ESPN College GameDay partnership;
- a 2027 innovation slate loading in November and December;
- planned Alani international launches;
- a portfolio-wide revenue growth management program aimed at improving trade efficiency through 2027–2028.
The market setup is more complicated than the surprise implies. Shares closed at $30.75 ahead of the report, up 18.4% from the open after the August release. That move came off a 52-week low of $23.56 set on that day. The stock then spiked to $36.15 later in August and has since faded to about 15% below that high and roughly 10% below its 200-day moving average. Investor sentiment remained negative but improved slightly, from -0.32 to -0.30. The Earnings Whispers trend signals are mixed, with momentum negative while AVWAP is positive.
The bottom line is that Celsius beat on the top and bottom lines, but the drivers of the beat are narrower and less durable than the headline suggests. Alani Nu is accelerating while the CELSIUS brand is deteriorating, margins are still falling, and Q4 has been partially borrowed from. Bulls get genuine growth and a robust 2027 pipeline. Bears have legitimate ammunition in a margin recovery that keeps receding and in increasing dependence on one brand's LTO cadence.
Read our earnings preview for Celsius Holdings, Inc.: https://www.earningswhispers.com/article/CELH/22523
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 4 hours | |
| 4 hours | |
| 5 hours | |
| 6 hours | |
| 6 hours | |
| 7 hours | |
| Oct-30 | |
| Oct-29 | |
| Oct-27 | |
| Oct-20 | |
| Oct-14 | |
| Oct-08 | |
| Oct-08 |
