Acacia Research Swings To An Adjusted Profit, But An $8.2 Million Stock Gain Did The Heavy Lifting While Deflecto Keeps Slipping
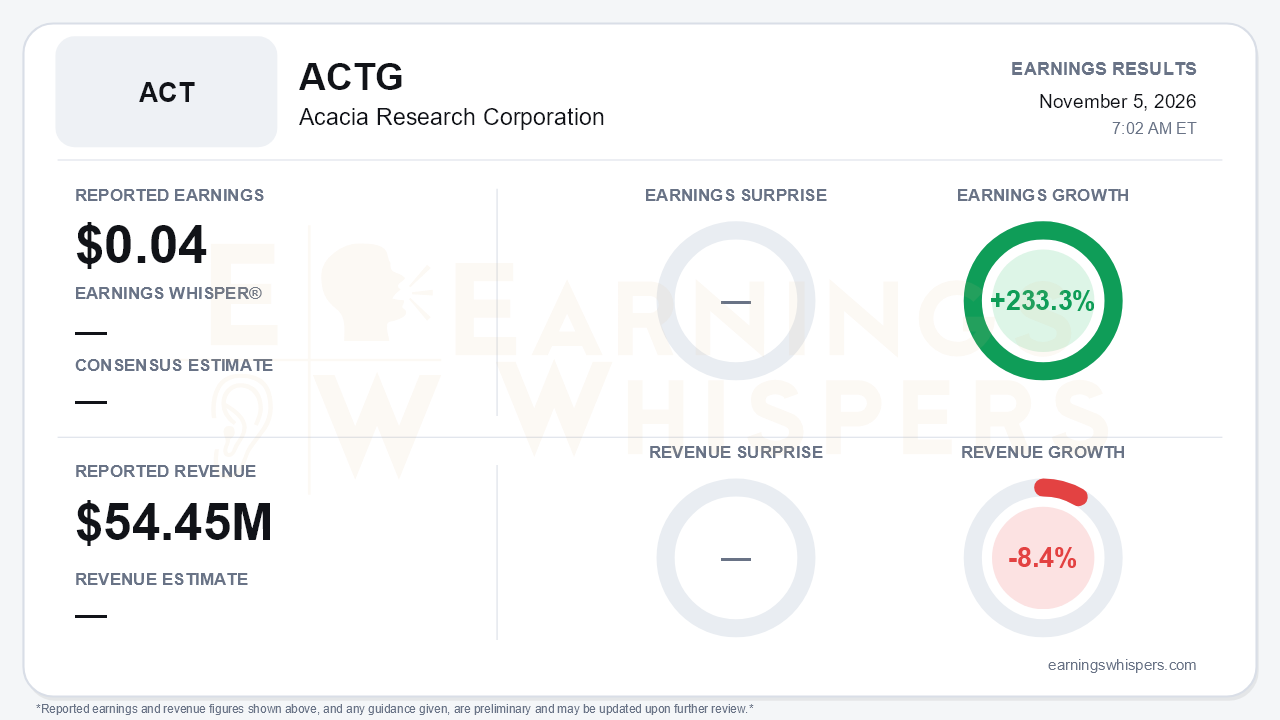
Acacia Research (NASDAQ: ACTG) reported adjusted earnings of $0.04 per share for the September quarter, up 233.3% year over year from an adjusted loss of $0.01. Revenue of $54.45 million fell 8.4%. There was no consensus estimate to measure against, so the more useful question is what produced the profit. The answer is not mainly the operating businesses. On a GAAP basis, Acacia's net loss widened to $5.6 million, or $0.06 per share, from $2.7 million, or $0.03, a year ago. The quarter shows a portfolio that is gradually improving at the operating level but still depends on investment gains and one-time events to post a profit.
The quality of the adjusted beat deserves scrutiny. Acacia booked an $8.2 million realized gain on selling its second public equity position, roughly 2.5x its money in under six months. The adjusted figures exclude unrealized marks but keep realized gains, so that sale flowed straight into adjusted net income of $4.3 million. Without it, adjusted earnings would likely have been negative.
The adjustments also added back a $6.0 million unrealized loss on securities and about $3.8 million of unrealized hedge losses. Total derivative losses at Benchmark were $6.1 million, including roughly $5.1 million unrealized. Total Company Adjusted EBITDA, which strips out investment gains, fell by half to $3.9 million from $8.0 million. That decline is the cleaner read on the consolidated earnings base.
The revenue decline is almost entirely an IP story. Intellectual property revenue collapsed to $263,000 from $7.8 million, with no paid-up licenses signed in the quarter, and the segment posted a $2.5 million EBITDA loss. Strip out IP and the picture improves. Revenue from the operated businesses reached $54.2 million, the third straight sequential increase and near a record. Their combined adjusted EBITDA rose to $11.6 million from $9.6 million a year ago. Two businesses drove that gain:
- **Benchmark Energy:** EBITDA climbed to $9.1 million from $6.1 million.
- **Printronix:** EBITDA nearly doubled to $1.5 million, on revenue that rebounded to $7.5 million from $6.0 million in Q2.
Higher parent costs of $5.1 million absorbed part of the improvement.
The weak spots matter, though. Deflecto is now the clearest problem in the portfolio.
- Revenue fell to $27.2 million from $30.8 million.
- Adjusted EBITDA dropped to $1.0 million from $2.6 million, the third straight quarter stuck around $1.0 to $1.2 million.
- The roughly $2 million in Portland savings flagged for the second half has yet to show up.
- Restructuring charges of about $0.7 million continue with no stated end date.
Management blamed soft U.S. and Canadian housing demand and higher input costs. It pointed to an improved September, positive Class 8 truck trends, and a possible tariff rollback as potential relief, but those remain hopes rather than results.
Benchmark also cooled sequentially. Revenue slipped from a record $20.5 million to $19.5 million, EBITDA eased from $9.8 million, and free cash flow dropped to $2.7 million from $6.5 million as capital spending rose.
The forward catalysts sit mostly in energy. After quarter end, Benchmark closed a senior secured note facility of up to $47.5 million, with $27.5 million committed and $18.5 million funded per the call. The facility funds a four-well Cleveland program in the Western Anadarko Basin. It is non-recourse to Acacia and to Benchmark's other assets, so drilling can accelerate without tying up parent capital. The second Cherokee well, Moon Tower, is tracking ahead of the first in early flowback. Management expects the year-end reserve report to show drilling value that book value does not capture. In IP, overhead was cut further and Wi-Fi 7 patents were added, but that segment's earnings will remain lumpy.
Capital allocation is where bears have the most legitimate ammunition. Cash, securities and loans rose to $346.3 million, or $3.55 per share, with no parent-company debt. Yet management acknowledged being outbid on private deals by what it called irrational private-equity buyers. It again sidestepped questions about buybacks, even with shares trading around a 20% discount to book. Book value per share continued to erode, to $5.65 from $5.71 last quarter and $6.05 at year-end.
On price, shares opened at $4.98 after the August report, comfortably above the $4.53 200-day moving average. A 20% discount to book, however, implies the stock has drifted back toward that average. The market appears to be waiting for proof of capital deployment rather than paying up for the cash pile.
The bottom line is that Acacia's adjusted profit owed more to a well-timed stock sale than to its operating businesses. Underneath, there is real progress at Benchmark and Printronix, offset by a deteriorating Deflecto and a dormant IP segment. The investment case hinges on whether management can put roughly $346 million to work, or return it, before book value erodes further. Until that happens, the discount to book looks less like a mispricing and more like a verdict on capital allocation.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-22 | |
| Oct-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-22 | |
| May-07 | |
| May-07 | |
| Apr-23 | |
| Mar-11 | |
| Mar-11 | |
| Mar-11 | |
| Feb-25 |
