OpenText Clears A Low Bar On Profits And Cash Flow, But Shrinking Revenue And Weak ITOM And Cyber Leave The Story Hinging On February
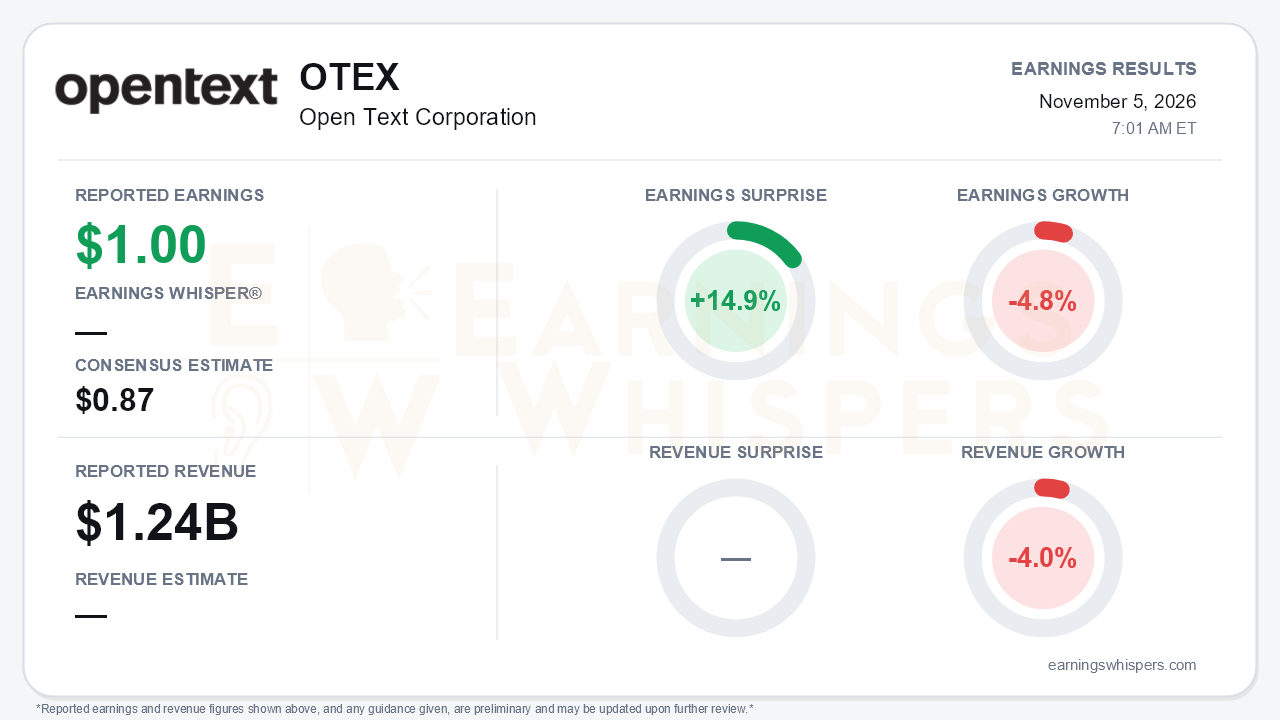
OpenText opened fiscal 2027 with a profit beat. Revenue still fell. Earnings Whispers normalized EPS was $1.00, 14.9% above the $0.87 consensus, but earnings fell 4.8% year over year on revenue of $1.237 billion, down 4.0%. The company's own non-GAAP EPS was $1.05, flat with a year ago, so the per-share comparison depends on the yardstick. The direction of travel does not: profitability and cash generation are being managed well while the top line keeps contracting. The central tension is that management is asking investors to trust a growth pivot that the reported numbers do not yet show.
The beat was driven more by cost discipline, capital structure and share count than by operating growth. Non-GAAP net income fell 4.5%, and per-share earnings held up largely because diluted shares dropped to about 242 million from nearly 254 million. GAAP EPS rose 10.3% to $0.64, but the gains came from below the operating line:
- Acquired-intangible amortization fell to $98.9 million from $123.8 million.
- Interest expense fell to $67.9 million from $81.1 million.
- Other income swung to a $16.1 million gain from a small loss.
GAAP operating income actually declined 7.1%. Spending is being reallocated: R&D fell to $142 million from $169 million while sales and marketing rose to $278 million from $257 million, consistent with the push to expand sales capacity. Free cash flow of $139 million rose 36.8%, helped partly by lower capital spending. The 35.8% adjusted EBITDA margin comfortably topped the 32%-33% Q1 outlook. It was still down 50 basis points from a year ago and well below the prior quarter's 37.6%.
Beneath the headline, the business is splitting in two:
- **Growing pieces.** Core cloud revenue grew 11.7% in constant currency, up from 8.9% in the fourth quarter. Content cloud grew 20.7%, its fifth straight quarter near 20%. Cloud CRPO rose 12% and long-term RPO rose 13%, giving the cloud franchise genuine forward visibility.
- **Shrinking pieces.** Client support revenue fell 9%, client support CRPO fell 5%, license dropped 8%, and professional services fell 11%. Total annual recurring revenue declined 3%.
The weakest spots were inside the core itself. ITOM and cybersecurity both fell by double digits, and management attributed the declines to execution. That leaves the commitment that every core category grows in fiscal 2027 dependent on a second-through-fourth-quarter recovery. Core revenue growth also eased to 2.7% from 3.1%. The quality of that core figure deserves scrutiny: $116 million of quarterly revenue was reclassified from core to non-core, and management said further reclassifications are possible. Moving legacy products out of the core makes the remaining core easier to grow.
Forward indicators were mixed. Large cloud wins slowed sharply: 35 deals above $1 million, up 6%, versus 64 deals up 49% in the fourth quarter. Management also discontinued the enterprise cloud bookings metric, which bears will read as a loss of disclosure at an inconvenient moment. Full-year guidance was reaffirmed, with nothing raised or cut. However, the fiscal 2027 EBITDA margin outlook of 32%-33%, down from 36.3% last year, implies meaningful second-half compression as $100 million to $200 million of growth investment ramps. Other risks include a Middle East client pause and stalled divestitures amid tight buyer financing.
The balance sheet offers a counterweight. After the quarter, OpenText:
- refinanced its 2027 notes with $1.0 billion of secured debt;
- tendered $300 million of 2028 notes;
- extended its revolver.
Gross debt has fallen roughly $949 million over twelve months, and net leverage is 2.55x. On the go-to-market side, all 300 client executive roles are filled. More than 150 Aviator agents are live, with Aviator deals running about four times larger. The Cohere partnership and SAP integration give the AI narrative some substance. The real catalyst is the February 10 Investor Day, where management will present its strategic framework and financial model following the enterprise assessment.
Investor sentiment remains negative but improved modestly, moving from -0.29 to -0.21 ahead of the report. Price action has been more constructive. Shares entered the release at $26.59:
- about 11.5% above the 200-day moving average;
- up 23.7% from the late-September low of $21.50;
- 6.1% below the October 23 high of $28.32.
Net of that round trip, the stock is up just 1.2% since the open after the August report. Earnings Whispers price and AVWAP trend readings are positive, while sequential growth and momentum are neutral, consistent with a stock that has stabilized more than it has rerated.
The bottom line is that OpenText delivered a credible quarter on margins, cash flow and deleveraging, and its content cloud engine is real. Those strengths sit on top of a shrinking total revenue base, double-digit declines in two core categories, slowing large cloud deals and a guided margin squeeze in the back half. Until the February Investor Day shows that ITOM and cyber can turn and that the redefined core can grow on its own, the beat looks more like disciplined execution of a holding pattern than proof of a turnaround.
Read our earnings preview for Open Text Corporation: https://www.earningswhispers.com/article/OTEX/22161
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 13 hours | |
| 16 hours | |
| 16 hours | |
| Oct-28 | |
| Oct-14 | |
| Oct-08 | |
| Oct-08 | |
| Oct-05 | |
| Oct-02 | |
| Oct-02 | |
| Oct-01 | |
| Sep-30 | |
| Sep-25 | |
| Sep-24 | |
| Sep-23 |
