Manulife Posts Record Core EPS And Beats Estimates, But Stalling New Business And Slowing Growth Cloud The Quality Of The Quarter
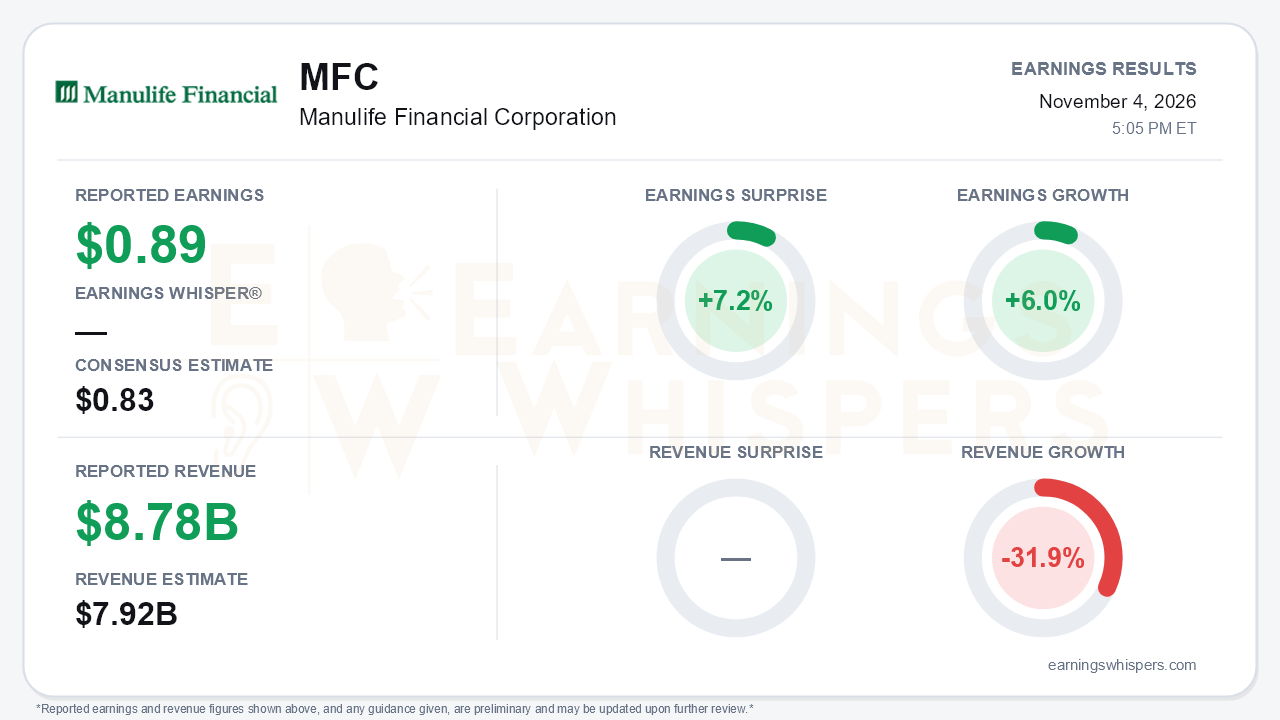
Manulife delivered a clean headline beat in the third quarter. Earnings Whispers' normalized EPS of $0.89 topped the $0.83 consensus by 7.2% and rose 6.0% from a year ago. Revenue of $8.779 billion beat the $7.92 billion estimate by 10.8%. The normalized figure tracks the company's record core EPS of C$1.24, up 6% at constant exchange rates. Core ROE reached 17.8%, up from 16.3% in the second quarter, which puts the reaffirmed 18%-plus 2027 target within reach. The central tension is that profitability hit a record just as growth slowed sharply. Core EPS growth eased to 6% from 16% in the second quarter and 11% in the first. Core earnings growth slowed to 4% from 12%, and insurance sales went flat after a strong first half.
The quality of the beat deserves scrutiny. Core earnings of C$2.125 billion were a record and well above the C$1.923 billion reported in the second quarter. However, the release credits part of the gain to the net positive impact of the annual actuarial review and to improved claims experience, alongside genuine business growth. Asia's 17% core earnings increase, for example, included assumption updates and better claims, partly offset by higher expected credit loss provisions. GAAP results told a weaker story. Net income attributed to shareholders fell to C$1.4 billion from C$1.8 billion a year earlier and C$2.1 billion in the second quarter, and GAAP EPS of C$0.82 dropped 21%. The charges behind that decline included:
- a C$388 million market-experience charge, driven by shortfalls in alternative long-duration assets (private equity, real estate and farmland), public equity losses and hedge ineffectiveness;
- a net charge from Vietnam.
The 31.9% year-over-year revenue decline also needs context. Realized and unrealized gains on assets backing insurance liabilities swung to a C$2.2 billion loss from a C$3.8 billion gain a year ago. That kind of mark-to-market volatility makes reported revenue a poor gauge of underlying demand.
The call showed that the demand picture is where momentum faded. Asia APE sales were roughly flat after rising 21% in the second quarter, even though Hong Kong sales rose 45% and Japan sales rose 39%. The Chinese Mainland and Singapore declined. Total new business CSM of C$957 million was the lowest of the past five quarters, and Mainland China new business CSM fell to C$43 million from C$112 million a year ago. Mix is also eroding margins. Hong Kong NBV margin dropped below 40%, down from the 50s, as sales shifted toward lower-margin high-net-worth savings products. In the U.S., APE was flat, but product mix cut new business CSM by 20% and NBV by 13%. Global Wealth and Asset Management swung to C$3.6 billion of net outflows from a C$0.4 billion inflow in the second quarter, mainly on retirement redemptions. Its core earnings fell 5%, and the core EBITDA margin slipped to 29.6% from 31.2%. There were bright spots in the segment: retail flows reached neutral, institutional inflows were C$1.4 billion, and management expects positive operating leverage from here.
Catalysts are real but mostly forward-looking:
- Manulife | Comvest closed a record US$5.4 billion private credit fund.
- The Ant Health partnership has begun cashless Alipay billing in the Chinese Mainland.
- Management expects materially stronger Mainland China sales in the fourth quarter.
- The company sold more than C$1 billion of equities to reduce market sensitivity.
Bears have legitimate ammunition. Management guided to further valuation pressure on alternative long-duration assets for a couple more quarters. Chinese tax enforcement on offshore policies is slowing decisions by Mainland Chinese visitor customers, and Hong Kong's regulator issued a circular on premium financing. Management also expects Japan sales to normalize as macro tailwinds fade. Other pressures include U.S. lapse experience, Canada group disability claims and higher credit provisions. Capital remains ample, with a 136% LICAT ratio and C$1.3 billion returned to shareholders, though the LICAT surplus edged down and leverage rose to 23%.
Investors appear to have registered the slowdown. Earnings Whispers sentiment fell from 0.59 to 0.31, a meaningful decline that nonetheless leaves sentiment in positive territory. The stock has held up better than that shift suggests. At $45.99, shares are up 2.2% from the open after the August report and trade about 14.7% above the 200-day moving average of $40.08. Momentum and AVWAP trend readings are positive, while the price trend is neutral. That combination fits a stock that has consolidated gains rather than broken down.
The bottom line is that Manulife's record core ROE and earnings beat show a profitability engine that keeps improving, and management's reaffirmed 2027 targets keep the medium-term story credible. The headline, however, masks a quarter in which sales growth stalled, margins compressed in Hong Kong and wealth flows reversed. The beat also leaned partly on favorable assumption changes and claims. With shares well above their long-term average and sentiment cooling, the next leg likely depends on whether the promised fourth-quarter rebound in Mainland China sales and steadier wealth flows materialize.
Read our earnings preview for Manulife Financial Corporation: https://www.earningswhispers.com/article/MFC/21873
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 12 hours | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-27 | |
| Oct-22 | |
| Oct-21 | |
| Oct-13 | |
| Oct-08 | |
| Oct-05 | |
| Oct-01 | |
| Sep-21 | |
| Sep-10 |
