Lightspeed Hits The Whisper As Margins Expand, But Shrinking Location Adds Undercut The Growth Story
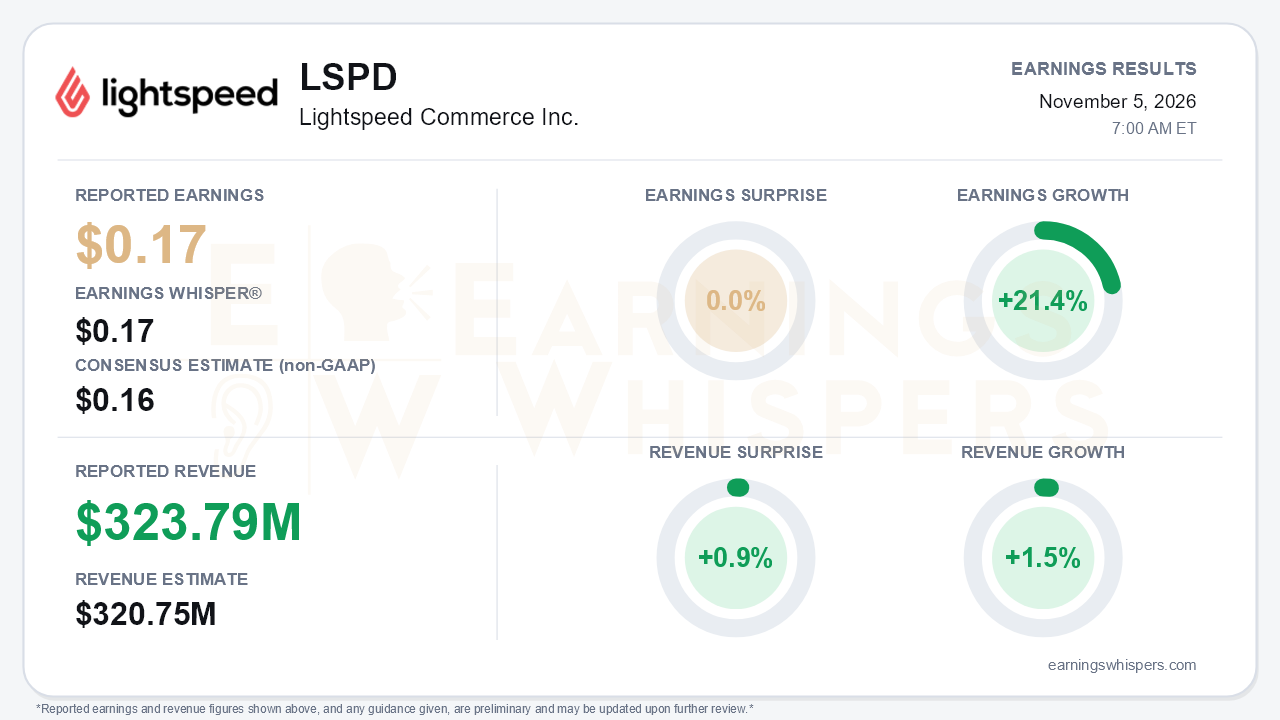
Lightspeed Commerce delivered a quarter that matched expectations but did not exceed them. Adjusted earnings of $0.17 per share topped the $0.16 consensus and matched the $0.17 Earnings Whisper number exactly, a 0.0% surprise against the bar that mattered most. Earnings grew 21.4% year over year, and revenue of $323.79 million beat consensus by 0.9%. Reported revenue growth of only 1.5% reflects the April divestiture of Upserve. On an organic basis, revenue rose 15%, at the high end of the company's outlook, and management reaffirmed full-year guidance. The central tension is that profitability and software metrics are clearly improving while the customer-acquisition engine that supports Lightspeed's growth targets is losing speed.
The profit side of the story is real, but the quality of the beat deserves scrutiny. The GAAP net loss narrowed sharply to $0.03 per share from $0.24. Much of that improvement, however, came from intangible amortization falling to $8.3 million from $34.7 million rather than from operating performance alone. The cleaner signal is sequential:
- Adjusted EBITDA rose to $22.7 million, or 16% of gross profit, from $17.5 million (13%) in the first quarter.
- Software gross margin reached 84%, up from 82% a year ago.
- Hardware margin improved to -59% from -74%.
Other lines were less encouraging. Transaction-based gross margin was flat year over year at 32% on an organic basis, and the call cited declining referral fees. Overall gross margin of 44% compared with 46% on an organic basis last year, a reminder that the mix shift toward payments carries a cost. Cash flow was also weaker. Operating activities consumed $7.5 million because outstanding merchant cash advances grew by $26 million. Adjusted free cash flow of $4.0 million was up from a first-quarter deficit but well below last year's $18.0 million.
The call made the trade-off explicit. Management tightened deal parameters and pushed further upmarket, and new growth-engine locations now carry 27% more software revenue than a year ago. Growth-engine software revenue accelerated to 14% from 12%, and software ARPU growth improved to 7% from 6% in Q1 and 4% in Q4. The cost of that discipline showed up in volume:
- Net growth-engine location adds fell to roughly 800, from about 1,300 in Q1 and about 3,200 in Q4 FY26.
- Location growth slowed to 8%, below the 10-15% three-year CAGR assumption management has highlighted.
- Growth-engine revenue growth decelerated for a third straight quarter, to 17% from 20% and 24%.
- Lightspeed Capital growth slowed to 42% from 56%.
Management spent much of the Q&A defending the location slowdown as a deliberate mix shift. That explanation may prove correct, but bears have legitimate ammunition until the ARPU gains clearly offset the thinner pipeline.
The forward setup leans on cost control. About 250 roles were eliminated after the quarter, following an earlier 10% reduction in product and technology headcount. Management raised the third-quarter adjusted EBITDA outlook to $25-30 million from the prior quarter's $20-25 million guide. Third-quarter organic revenue guidance of 11-15%, however, sits below Q2's 15% pace, confirming continued top-line deceleration. Several items support the story:
- Hardware pricing commitments with Apple and the company's payments provider run into FY28.
- Agentic AI usage is reportedly rising 20-30% month over month.
- Outbound sales motions are up about 30%.
The execution risk is that another go-to-market change is being layered on repeated restructurings. The cash picture also bears watching. First-half adjusted free cash flow was slightly negative, yet management still expects significant growth over FY26's $18.2 million and reiterated its $95 million FY28 target. Cash fell to $342.9 million from $453.9 million at fiscal year-end, driven largely by $76.8 million of buybacks and merchant cash advance growth.
The market setup is more complicated than the in-line print implies. Shares entered the report at $11.56, up 10.5% since the open following the July report. That left them 17.5% above the 200-day moving average and just 1.4% below an inter-earnings high set the day before results. Price and AVWAP trend readings are positive, while sequential growth and momentum are neutral. Investor sentiment, however, remained negative and weakened modestly, slipping to -0.49 from -0.42. In other words, the stock ran into the print while sentiment did not follow. A quarter that only matched the whisper gives little cushion against that positioning.
The bottom line is that Lightspeed is executing well on margins, software monetization and cost discipline, and reaffirmed guidance keeps its profitability targets credible. The headline, though, masks a decelerating growth engine, with location adds, growth-engine revenue and capital revenue all slowing. Until the upmarket pivot shows it can restore volume growth, the stock's run toward its quarterly high rests more on margin progress than on demand.
Read our earnings preview for Lightspeed Commerce Inc.: https://www.earningswhispers.com/article/LSPD/22136
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| 12 hours | |
| Oct-28 | |
| Oct-22 | |
| Oct-15 | |
| Oct-12 | |
| Oct-08 | |
| Sep-15 | |
| Sep-04 | |
| Sep-03 | |
| Aug-27 | |
| Aug-25 | |
| Aug-05 | |
| Jul-31 | |
| Jul-30 |
Lightspeed CEO breaks down Q1 growth 'we're firing on all cyclinders'
LSPD -12.26%
Yahoo Finance Video
|
