GigaCloud Beats And Raises Again, But Freight-Driven Service Margins Are Masking Softer Product Economics
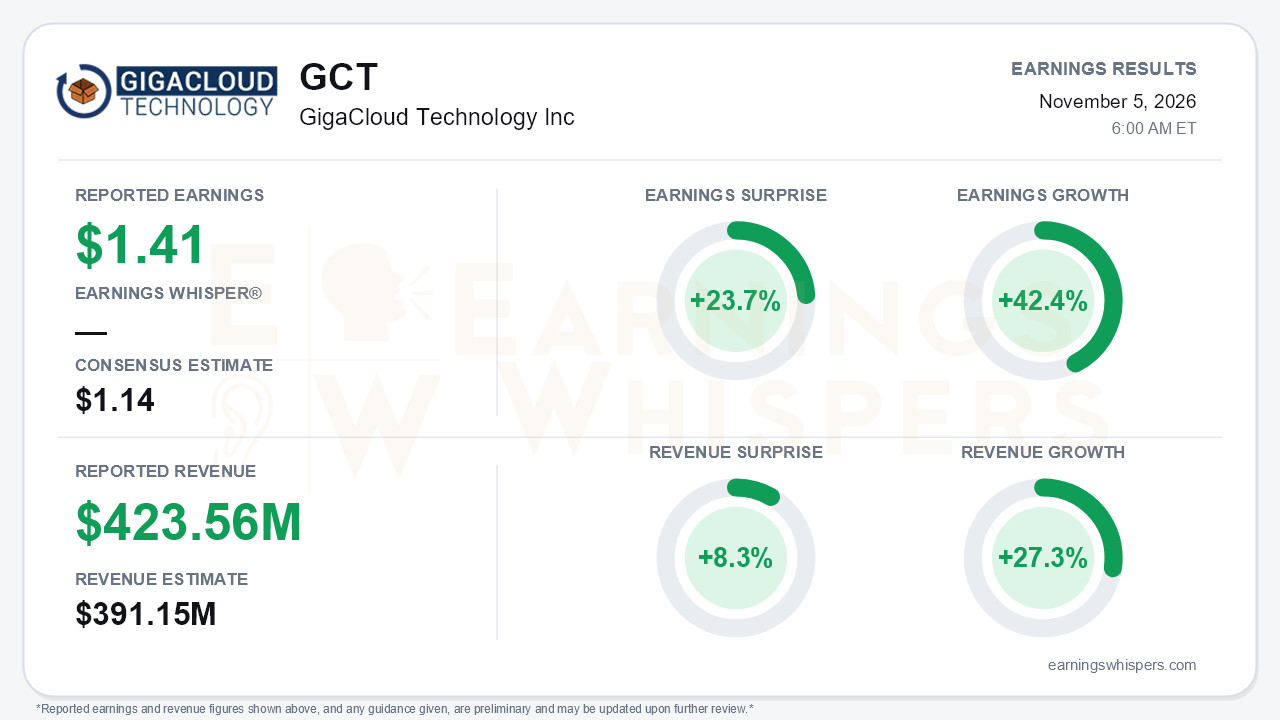
GigaCloud Technology delivered its third straight quarter of results well above its own guidance. Third-quarter earnings of $1.41 per share beat the $1.14 consensus by 23.7% and rose 42.4% year over year. Revenue of $423.56 million topped expectations by 8.3%, grew 27.3%, and cleared the company's own $375-400 million guide by a wide margin. Management then set fourth-quarter revenue guidance of $425-450 million, roughly $50 million above the prior quarter's guide at the midpoint and above Street expectations. The headline is unambiguously strong. The quality of the beat deserves scrutiny, however, because the margin expansion came from the service side of the business. That segment depends partly on ocean freight conditions management says it cannot forecast. Meanwhile, the core product business showed thinner margins and slower growth in several key areas.
The income statement shows where the leverage came from. Gross margin improved to 24.9% from 23.2% a year ago, and net margin reached 11.9%. Operating income rose about 46% to $59.0 million. G&A was held to roughly 2% of revenue, compared with about 5% in the second quarter, when share-based compensation weighed more heavily. Buybacks amplified the per-share result. Diluted shares fell to 35.8 million from 37.6 million, which is why EPS growth of 42.4% outpaced net income growth of 36.0%. Investors should also note that GigaCloud's 'Adjusted EPS' of $1.73 is simply adjusted EBITDA divided by shares. It is not a conventional adjusted earnings figure, and the GAAP $1.41 is the cleaner benchmark.
The call explains the mixed character of the gross-margin line. Service gross margin climbed to 15.3%, up from 11.7% in the second quarter and just 2.7% in the first. Management credited the spread between contracted ocean costs and higher spot rates, along with better ground performance. Product gross margin moved the other way, falling about two points sequentially to 29.4%. Management cited higher ocean and last-mile costs, 3P sellers competing with GigaCloud's own 1P inventory in Europe, and seasonal discounting. As a result, total gross margin slipped to 24.9% from 25.6% in the second quarter. That is the central tension: the most visible margin improvement relies on a freight dynamic that could reverse, while product profitability is eroding.
Growth beneath the headline is also uneven. Total revenue grew 23% organically, and US marketplace GMV growth improved to 13% from 9%. However, US organic product growth was only about 5%, against what management describes as a persistently weak furniture and housing backdrop. Europe remains the standout: 3P GMV rose roughly 330% and contributed about $30 million. Still, Europe product growth has decelerated from 80% to 54% to 46% over the year, and management expects further moderation. The New Classic acquisition is getting worse before it gets better. Its revenue fell about 30% to $14 million as SKUs were deliberately exited, compared with an 8% decline in the second quarter. Management positioned the October High Point launch of 140 collections and about 500 SKUs as a 2027 contributor. Two developments add credibility to that plan: about two dozen New Classic retailers now source through the marketplace, and more than 60 are in the pipeline. Management also called the M&A environment buyer-friendly, citing distressed wholesalers.
Cash generation was solid in the quarter, with $56 million of operating cash flow compared with $48 million in the second quarter. Year-to-date operating cash flow, however, is down to $83.1 million from $126.3 million, as inventories, receivables, and prepayments absorbed cash. With $418 million in liquidity, no debt, and $115 million left on the buyback authorization, the balance sheet gives management ample flexibility. That includes the possibility of a special dividend if repurchase capacity goes unused by 2029.
The market setup has shifted materially. Investor sentiment swung from slightly negative (-0.10) at the prior report to clearly positive (+0.32), a meaningful change in expectations. Shares entered the report at $57.88, up 20.6% since the open after the August release and about 31% above the 200-day moving average. The stock sits 6.7% below the 52-week high of $62.03 set on October 29. Price, momentum, and AVWAP trend readings are positive, while sequential growth is neutral. That neutral reading fits the guide: the Q4 midpoint implies year-over-year growth decelerating to roughly 17-24%. With the stock near its highs and sentiment more optimistic, expectations are no longer depressed.
The bottom line is that GigaCloud again beat and raised, and its execution record against its own guidance is now hard to dismiss. The margin story, though, is more fragile than the record EPS suggests. Product margins are compressing, New Classic is shrinking, and Europe and US product growth are moderating, while service margins depend on unpredictable spot freight rates. Bulls have a credible multi-driver growth narrative, but bears have legitimate ammunition on margin durability, and a stock trading near its highs leaves less room for any normalization in freight.
Read our earnings preview for GigaCloud Technology Inc: https://www.earningswhispers.com/article/GCT/22448
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-29 | |
| Oct-29 | |
| Oct-23 | |
| Oct-10 | |
| Oct-08 | |
| Sep-29 | |
| Aug-06 | |
| Aug-06 | |
| Aug-04 | |
| Jul-30 | |
| Jul-03 | |
| Jun-10 | |
| Jun-03 |
