Virtu Beats Handily, But Its Third Quarter Is Another Step Down From The Q1 Peak
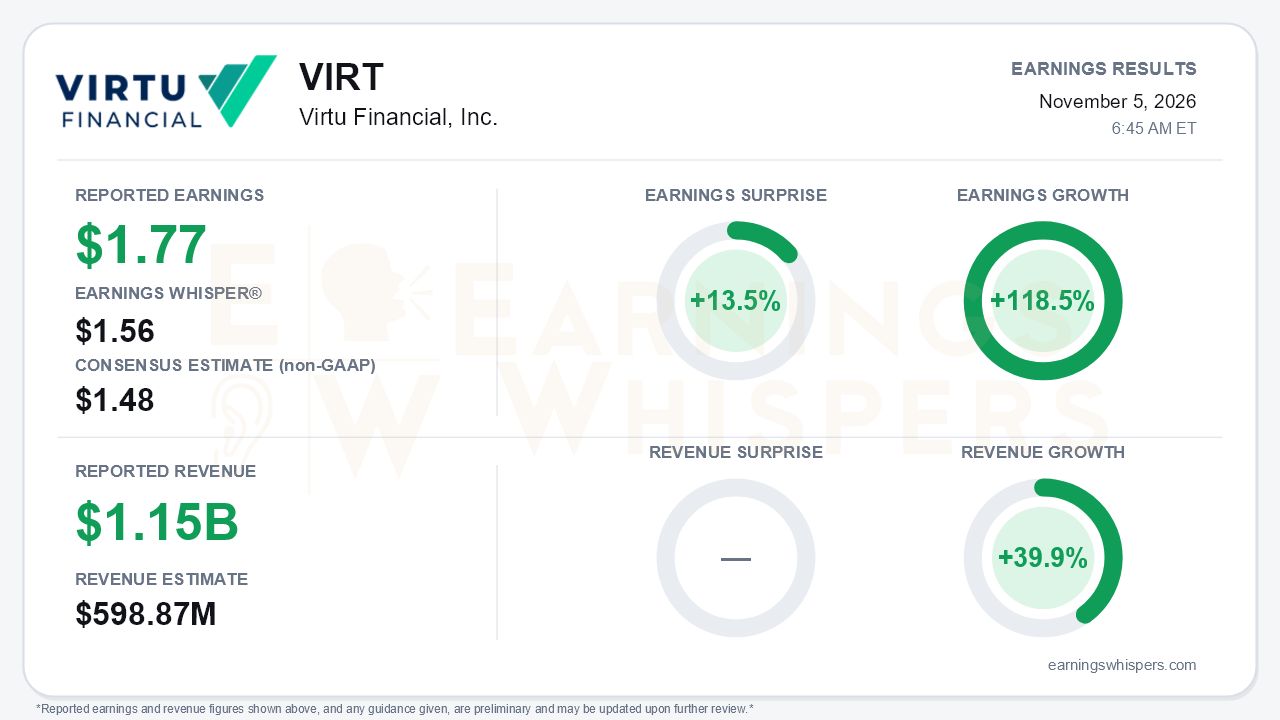
Virtu Financial delivered a clean beat on paper. Normalized adjusted EPS of $1.77 topped the $1.48 consensus by 13.5% and cleared the $1.56 Earnings Whisper number. Revenue of $1.154 billion rose 39.9% year over year, and Earnings Whispers calculates earnings growth of 118.5%. GAAP EPS nearly doubled to $1.65 from $0.86, and Adjusted EBITDA jumped 63.5% to $437.9 million. Yet the year-over-year comparison flatters a business that is cooling in sequence. Adjusted EPS has now slipped for two straight quarters, from $2.24 in Q1 to $1.82 in Q2 to $1.77. That is the central tension: an easy comparison against a soft 2025 quarter is masking a gradual deceleration from the first-quarter peak.
The headline numbers deserve some scrutiny. The 92.7% revenue surprise looks enormous partly because Virtu's total revenue is a gross figure. It includes $151.2 million of interest and dividend income that is largely offset by $197.5 million of interest expense. The $598.87 million consensus appears to sit on a different, closer-to-net basis, so the size of that surprise should be read cautiously. Adjusted Net Trading Income (ANTI) is the better gauge of performance. It rose 50.7% to $704.0 million, but nearly all of that gain came from Market Making, where segment ANTI climbed to $578.8 million from $344.1 million. Execution Services barely moved, at $125.2 million versus $122.9 million. Costs are also climbing:
- Employee compensation rose 26% to $199.0 million.
- Financing interest increased to $43.2 million from $33.3 million.
- Long-term debt principal reached $2.55 billion after the July term-loan add-on.
The call filled in the sequential picture. Daily ANTI fell from $12.9 million in Q1 to $11.6 million in Q2 and $11.0 million in Q3. Market making slipped to $9.0 million a day, and Virtu Execution Services (VES) dropped to $2.0 million from $2.5 million. That ended the eight-quarter growth streak management had highlighted earlier in the year. The adjusted EBITDA margin edged up to 62% from 61%, but it remains well below the 72% posted in Q4 2025 and 66% in Q1. Management's best counterargument was resilience. U.S. equity volumes fell by a mid-teens percentage and realized volatility dropped more than 20%, yet market making declined only about 4% quarter over quarter. Management credited diversification into offshore equity perpetuals, crypto, and global AI and chip-stock activity, arguing that results are becoming less tied to U.S. retail metrics. On a trailing basis, the scorecard looks strong: records in trailing-twelve-month ANTI ($11.3 million a day), adjusted EBITDA ($1.8 billion), and adjusted EPS ($7.69).
The forward story rests on capital deployment rather than formal guidance, which Virtu does not provide. Invested capital rose to $3.4 billion from $2.6 billion in Q1. About $900 million was added this year, roughly half organic and half debt, and leverage eased to 1.4x from 1.5x. Management reiterated its goal of $4 billion or more in capital, its $10 million-a-day through-the-cycle ANTI aspiration, and a cash compensation ratio in the low-to-mid 20s. The risks are tangible:
- Hiring and compute spending are rising amid AI-driven supply-chain cost pressure, with headcount set to exceed 1,100.
- Analysts pressed on risk appetite and P&L distribution. Management acknowledged that distribution has widened since the IPO, though it said it is unchanged over the past year.
- Media reports of a possible VES sale add strategic uncertainty. Management called VES strategic and said no asset sale is needed to reach its capital goal.
Separately, the board approved moving Virtu's incorporation to Texas, with approval from the controlling stockholder by written consent. Governance-focused holders will notice.
Investors entered the report skeptical, and they became slightly more so. Earnings Whispers sentiment remained negative and weakened modestly, from -0.33 to -0.38. The price action explains the caution. Shares spiked to a 52-week high of $68.76 in late August, then gave back that entire rally. They bottomed at $51.56 in late September and closed at $53.03 before the report. That leaves the stock 22.9% below its high, just 2.9% above the quarter's low, and 4.7% below where it opened after the July report. Shares sit only 1.4% above the 200-day moving average of $52.30. The trend readings are mixed: momentum is positive, while the AVWAP trend remains negative, consistent with buyers who chased the August spike still sitting on losses.
The bottom line is that Virtu beat expectations comfortably and showed it can still earn well in a quieter tape. However, the quarter extended a sequential slide in ANTI, adjusted EPS, and VES activity that the year-over-year growth figures obscure. Bulls can point to record trailing results, a larger capital base, and diversified revenue sources. Bears have legitimate ammunition in rising costs, heavier debt service, margins well off their peak, and uncertainty around VES. With shares hugging their 200-day average and sentiment still negative, the market appears to be pricing a normalizing environment rather than rewarding the beat.
Read our earnings preview for Virtu Financial, Inc.: https://www.earningswhispers.com/article/VIRT/22206
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 13 hours | |
| 16 hours | |
| 16 hours | |
| Nov-03 | |
| Oct-28 | |
| Oct-19 | |
| Oct-15 | |
| Oct-07 | |
| Sep-28 | |
| Sep-08 | |
| Sep-03 | |
| Aug-27 | |
| Aug-18 | |
| Jul-30 | |
| Jul-30 |
