Victory Capital Misses On Fee Compression As Record $11.7 Billion Inflows Arrive In Lower-Fee Products
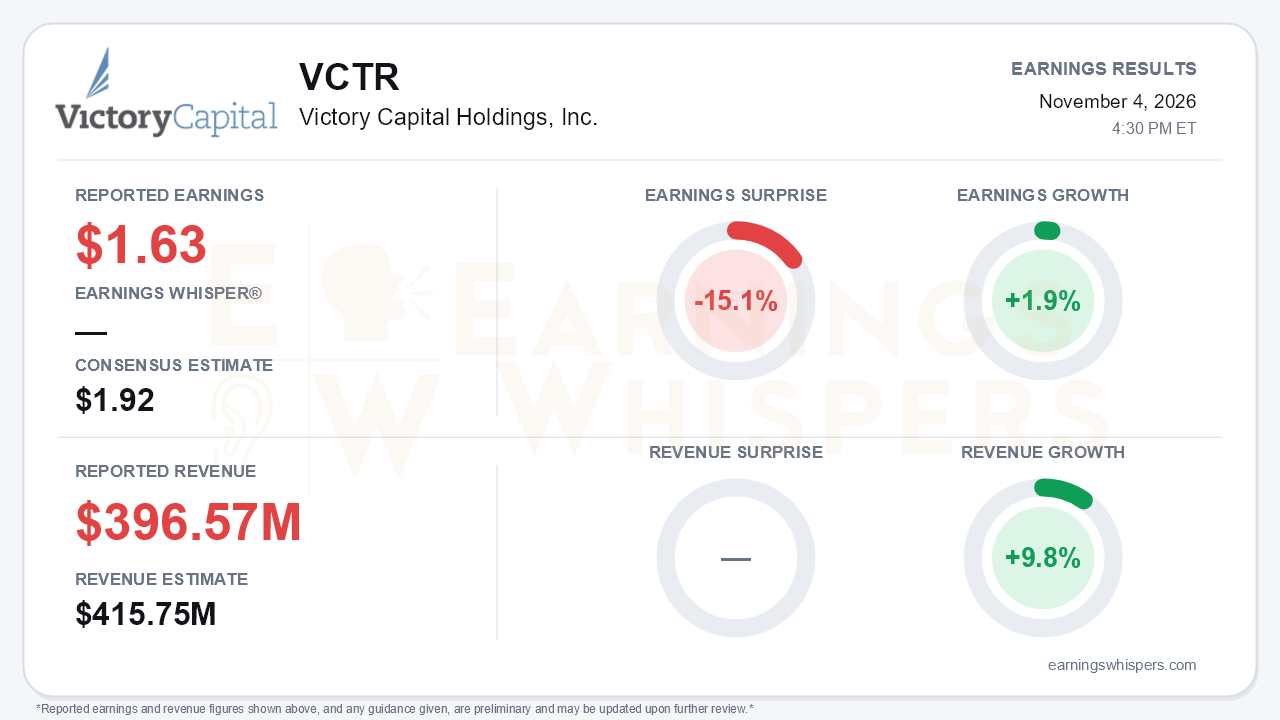
Victory Capital delivered its best quarter for asset gathering and a disappointing quarter for monetizing it. On Earnings Whispers' normalized basis, the company earned $1.63 per share, 15.1% below the $1.92 consensus and up just 1.9% from a year ago. Revenue of $396.57 million rose 9.8% year over year but missed the $415.75 million consensus by 4.6%. Investors should note that the company's own headline figure, adjusted net income with tax benefit, was $1.98 per share, up from $1.63 a year earlier. Whichever measure is used, the direction is the same: earnings fell sharply from the second quarter's $2.21 adjusted result. That is the central tension. Record long-term net inflows of $11.7 billion, roughly a 14% annualized organic growth rate, coincided with falling revenue and margins.
The quality of the miss deserves scrutiny because most of it came from pricing rather than volume. Average AUM rose about 6% sequentially to $350.6 billion. Even so, revenue fell 8.9% from $435.4 million, and AUM revenue realization dropped to 44.8 basis points from 47.9 in the second quarter and 47.2 a year ago. That is below the 46-47 basis point fee-rate range management discussed last quarter. Management attributed the decline to annual fees that crystallized in the second quarter and to shifts in asset-class and client mix. The flow detail supports the mix explanation. Fixed income ($6.8 billion), solutions ($7.2 billion) and ETFs ($3.9 billion) drove the inflows. U.S. mid-cap, small-cap and large-cap equity, which carry higher fees, bled a combined $3.9 billion. Victory is growing fastest in its cheapest products.
GAAP results look worse. Operating margin fell to 34.7% from 44.5% in the second quarter, and GAAP EPS dropped to $1.11 from $1.68. The main drivers were $15.5 million of First Eagle acquisition costs and a jump in share-based compensation to $32.5 million, which the company excludes from its adjusted figures. On that adjusted basis, EBITDA margin slipped 230 basis points to 53.5%. That remains comfortably above the 50% long-term target set in the second quarter and 80 basis points better than a year ago. Cash generation was strong. Operating cash flow reached $223.4 million, and the company returned $81 million to shareholders, including $39 million of buybacks.
The conference-call material offers little help in reconciling these numbers. The transcript analyzed was a media fireside chat rather than a quarterly earnings call. It contained no new financials, flow commentary, fee-rate guidance or margin update, and several figures cited by the CEO appeared stale relative to second-quarter disclosures. Management was promotional about the Amundi distribution channel, describing it as significantly net-flow positive since closing. The CEO also pointed to expansion of U.S.-listed VictoryShares ETFs into Asia and framed the 15-year exclusive Amundi agreement as an advantage when sourcing acquisitions. The main new fact was a negative one: the Janus Henderson pursuit failed, with that firm going private with Trian and General Catalyst. The chat framed the path to $1 trillion in AUM as dependent on finding another large deal. That framing sits awkwardly beside the release, which describes the pending First Eagle acquisition as "transformational" and expected to close by the end of the first quarter of 2027. Investors should treat First Eagle, not Janus, as the operative M&A story. They should also recognize that it brings integration costs, regulatory and client-consent conditions, and execution risk on top of roughly $975 million of existing debt.
The market setup made the miss more consequential. Shares opened at $102.50 after the August report and stood at $120.19 heading into this release, a gain of 17.3%. That left the stock about 33.8% above its 200-day moving average. Investors were paying for continued earnings momentum, and the fee-rate slide undercuts that assumption at least for a quarter. Sentiment had already turned. Earnings Whispers investor sentiment fell from 0.19 to -0.15, a meaningful swing from mildly positive to mildly negative. Trend readings are mixed: sequential growth and momentum remain positive, while AVWAP is negative.
Bulls can argue that flows, investment performance and margins are all healthy. Sixty-nine percent of AUM beat benchmarks over three years, 77% over ten years, and ending AUM reached a record. Bears have legitimate ammunition as well. Organic growth is concentrated in lower-fee strategies, legacy active equity continues to shrink, and adjusted EPS fell by double digits sequentially despite record inflows.
The bottom line is that Victory Capital's growth engine is working, but the revenue yield on that growth is deteriorating. Until fee realization stabilizes near the mid-40s basis points or First Eagle closes and broadens the earnings base, record flows alone may not justify a stock trading well above its long-term trend.
Read our earnings preview for Victory Capital Holdings, Inc.: https://www.earningswhispers.com/article/VCTR/21962
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-20 | |
| Oct-12 | |
| Sep-11 | |
| Sep-10 | |
| Sep-03 | |
| Aug-28 | |
| Aug-26 | |
| Aug-26 | |
| Aug-26 |
