REGENXBIO's Narrower Loss Leans On A Sarepta Settlement Gain While Investors Wait On The Wet AMD Readout
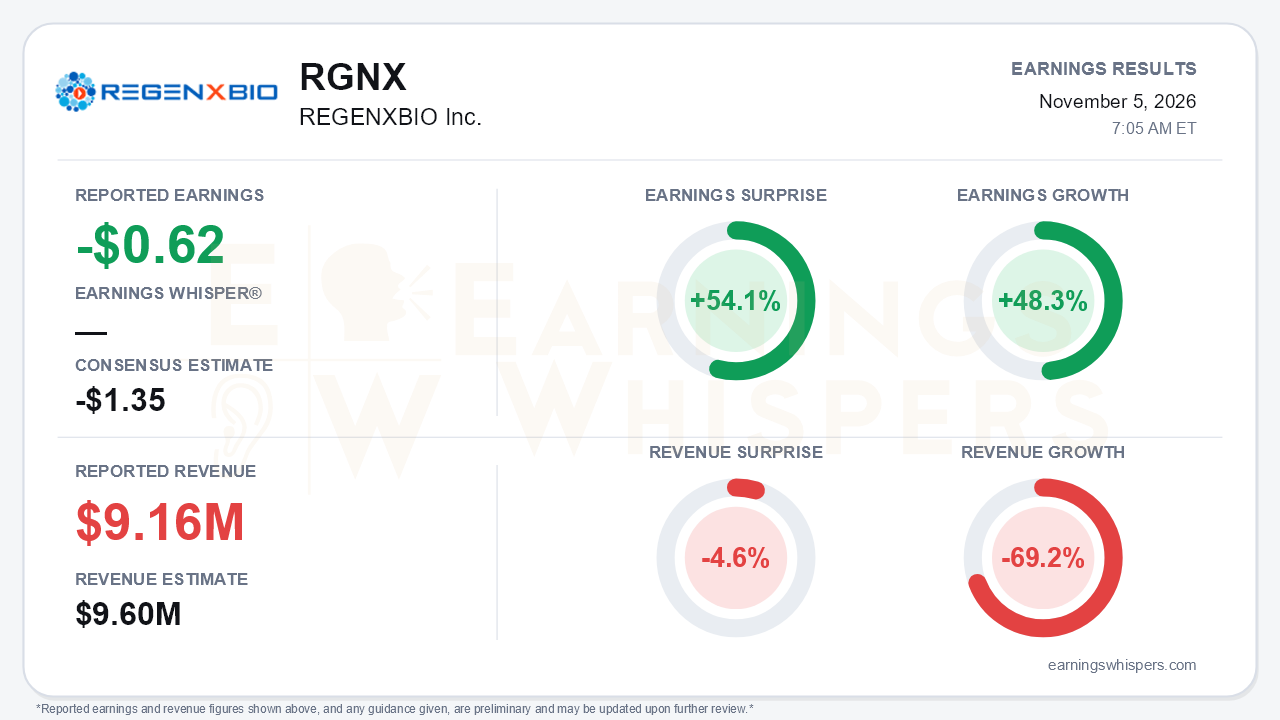
REGENXBIO (NASDAQ: RGNX) reported a third-quarter loss of $0.62 per share, beating the -$1.35 consensus by 54.1% and improving 48.3% from a year ago. Revenue of $9.16 million missed the $9.6 million consensus by 4.6% and fell 69.2% year over year. The headline beat says little about the underlying business. The narrower loss came largely from a one-time litigation gain and a larger share count, while the core royalty base is still shrinking. For a company about to report pivotal wet AMD data, the quarter's financials matter less than its balance sheet and timelines, and on those the picture is mixed.
The quality of the beat deserves scrutiny. REGENXBIO booked a $38.0 million gain on its patent settlement with Sarepta Therapeutics, which cut total operating expenses to $44.7 million from $82.1 million a year earlier. Without that credit, the quarter's loss would have been wider than last year's $61.9 million, because R&D rose to $61.0 million from $56.1 million on RGX-202 clinical spending. The per-share comparison also benefits from dilution: weighted shares climbed to 65.3 million from 51.7 million after the July equity offering. The revenue drop was expected. ZOLGENSMA royalties fell $21.2 million after U.S. patents expired in January. ITVISMA added $2.8 million in royalties, with patent protection extending to 2037, but it replaces only a fraction of the lost stream so far. There is also a mild inconsistency in the revenue story. On the call, the CFO said royalty revenue came in ahead of analyst models on the ITVISMA ramp, yet total revenue still missed consensus. That suggests softness elsewhere, such as service revenue, which fell to $3.9 million from $6.1 million.
The call amounted to a pre-catalyst holding pattern, with the core programs reaffirmed and the secondary timelines slipping:
- **Sura-vec in wet AMD:** Topline data from the ATMOSPHERE and ASCENT pivotal trials, which enrolled more than 1,300 patients, remains on track for this quarter. Management set an explicit bar of at least a 50% reduction in injection burden, with a meaningful share of patients needing no further injections.
- **Sura-vec in diabetic retinopathy:** Three-year ALTITUDE data showed 60% of patients at dose level 3 achieved at least a two-step DRSS improvement without additional treatment, up from 50% at two years.
- **RGX-202 data package:** The safety database now exceeds 60 patients, versus roughly 50 discussed earlier this year. About 14 patients will have 12-month functional data, up from 9 at the May topline.
- **RGX-202 filing plan:** The company dropped the rolling BLA it had planned to begin in Q3 2026 in favor of a single full submission in Q1 2027. Management says targeted 2H 2027 approval is unaffected.
The RGX-121 program is the clearest setback. Last quarter, management targeted a Q3 2026 BLA resubmission for Hunter syndrome. The FDA has since placed a clinical hold after asymptomatic spine MRI findings in five participants. The company now offers no timeline, only further imaging and long-term follow-up. It also stopped citing a priority review voucher sale as a potential non-dilutive funding source.
The balance sheet story is less comfortable than the runway extension implies. Cash and investments were $251.0 million, up from year-end only because of the $100 million AbbVie milestone and $107.8 million in offering proceeds. Against the more than $310 million pro forma figure cited after Q2, the decline implies roughly $60 million of quarterly burn. Management nudged its runway guidance to "late into Q4 2027" from "into Q4 2027," but that extension relies on the Sarepta proceeds. The size of those proceeds is unclear. The press release puts the October payment at $39.0 million, while the call analysis references $49 million. Investors should treat the release's $39.0 million as the documented figure until the discrepancy is clarified. Either way, the runway ends right around the hoped-for RGX-202 launch, so the wet AMD data and any associated AbbVie milestones carry real financing weight. Analysts also raised newer risks:
- an unestablished payer framework and the need for a J-code for gene therapy in wet AMD;
- competing gene therapy readouts in 2027;
- shifting FDA leadership and heightened immunosuppression and liver-safety scrutiny across Duchenne gene therapies.
The market has not been generous. Shares have fallen 31.6% since the open after the August report, from $11.28 to $7.71. They sit 15.6% below the 200-day moving average and 36.2% below the inter-earnings high of $12.08 set on August 20. The stock did bounce 19.4% off its October 27 low of $6.46 heading into the print. Investor sentiment, already negative, became modestly more negative, moving from -0.157 to -0.252. That is a measured deterioration rather than capitulation. Price and AVWAP trend readings remain negative, although momentum has turned positive alongside the recent rebound.
The bottom line is that the earnings beat is largely an accounting artifact of the Sarepta gain and a larger share count, while declining royalties, steady burn, and the stalled RGX-121 program give bears legitimate ammunition. The investment case now rests almost entirely on the sura-vec wet AMD readout this quarter and a clean RGX-202 filing in early 2027. The improving DR durability data and the expanded RGX-202 dataset keep the growth story credible, but the stock's slide shows investors want proof before they pay for it.
Read our earnings preview for REGENXBIO Inc.: https://www.earningswhispers.com/article/RGNX/22453
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 3 hours | |
| 4 hours | |
| Nov-03 | |
| Oct-29 | |
| Oct-29 | |
| Oct-12 | |
| Oct-05 | |
| Oct-05 | |
| Sep-25 | |
| Sep-24 | |
| Sep-16 | |
| Sep-08 | |
| Aug-25 | |
| Aug-25 |
