Real REMAX Beats On Revenue But Misses On EPS As Faster Synergies Collide With A Lower 2027 EBITDA Outlook And Slowing Organic Growth
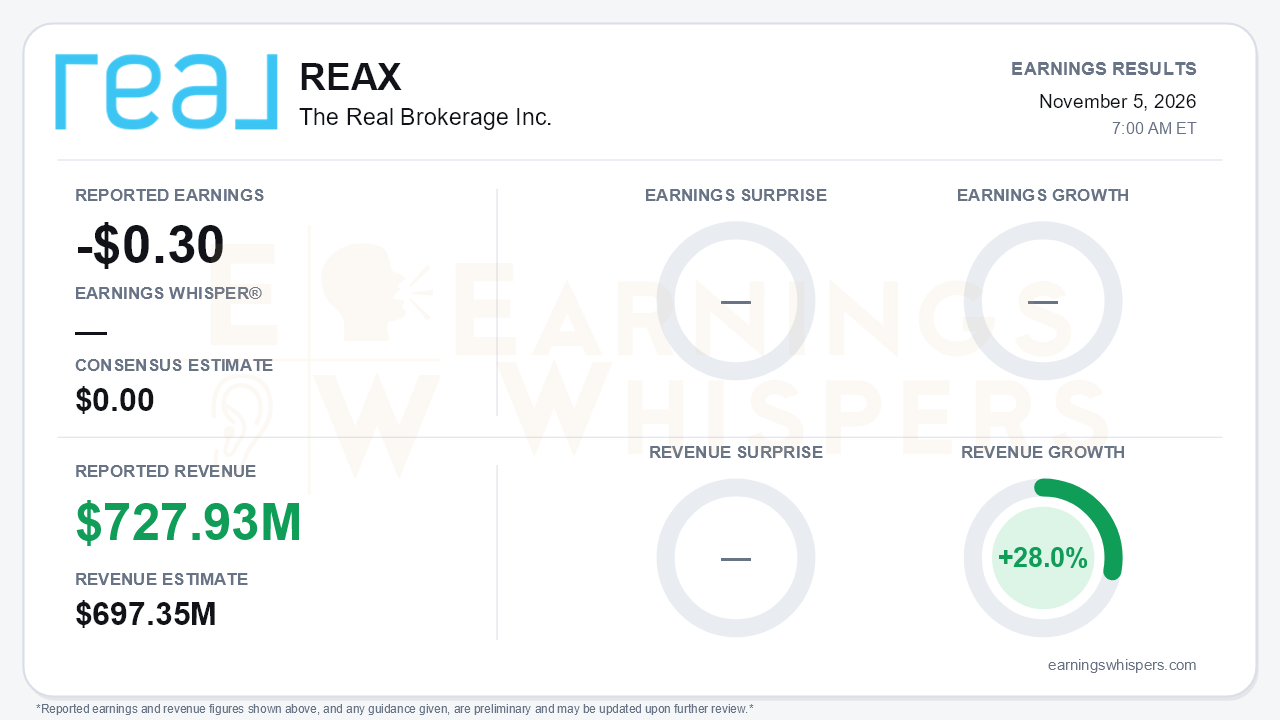
Real REMAX Group's first combined quarter beat on revenue and missed on earnings, and the more important development is a conflict over the outlook. Integration is moving faster than promised, but management's 2027 earnings outlook came in below the level it framed only three months ago. Earnings Whispers recorded a loss of $0.30 per share against a consensus estimate of breakeven, a clear miss. Revenue of $727.93 million topped the $697.35 million consensus by 4.4% and grew 28.0% year over year. The GAAP picture was far worse: a net loss of $67.2 million, or $2.25 per diluted share, compared with a $0.3 million loss a year ago. That deficit was driven by $52.3 million of acquisition and integration costs, $23.7 million of deal-related severance and $26.4 million of accelerated stock compensation tied to terminations.
Strip out the deal noise and the operating quarter looked better than the bottom line. Adjusted EBITDA rose 66% to $33.8 million, an acceleration from the 38% gain to $27.6 million in Q2. Adjusted EBITDA margin widened to 4.6% from 3.6%, helped by the higher-margin REMAX franchise stream that contributed $27.1 million in its first five weeks. Pro forma combined revenue grew 20% to $770.0 million, against an industry that management characterized as down about 2%. The quality of the quarter still deserves scrutiny, however. Nine-month operating cash flow fell to $14.5 million from $65.8 million as deal costs hit. The company now carries a $525 million term loan, and it expects roughly $50 million of interest and about $100 million of stock-based compensation in 2027. Those items sit outside adjusted EBITDA but squarely inside the per-share story.
The call made clear that Real's organic engine is losing speed:
- **Transactions:** Closed transaction sides grew 17% in Q3, down from 27% in Q2, 25% in Q1 and 38% in Q4 2025.
- **Agent growth:** Year-over-year agent growth slowed to 21% from 26%, and transactions per agent slipped to 1.7 from 1.8.
- **Attrition:** Agent count has since fallen to roughly 36,200 from 36,610 at quarter-end. The release cites more than 500 agents proactively offboarded in October for unpaid dues or expired licenses. On the call, management put offboarding since September at more than 1,000, with another 300 to 400 under review.
- **REMAX network:** U.S. and Canadian REMAX agents fell 3%, and management signaled no immediate reversal.
Net agent growth, the core of the Real thesis, has effectively stalled for now.
The synergy story is the offset, and it is credible. Management has already actioned more than $40 million of gross annualized savings, including about $28 million that benefits adjusted EBITDA, and headcount is down more than 14%. The prior target of roughly $30 million within three years of close is now more than $30 million in 2027 and more than $40 million in 2028. Other catalysts include:
- **Leo Pro:** The AI platform reached about 3,500 paying agents within weeks, with a REMAX network rollout planned.
- **Reason platform:** A rollout to REMAX broker-owners is targeted for Q1 2027.
- **Portfolio cleanup:** Loss-making Motto Mortgage and wemlo are being wound down.
- **Deleveraging:** A $25 million voluntary debt paydown sets up roughly $75 million of planned 2027 repayment toward net leverage below 2.0x by end-2028.
Guidance is where bears have legitimate ammunition. Fourth-quarter revenue guidance of $575 million to $625 million fell below expectations. The initial 2027 adjusted EBITDA range of $175 million to $190 million tops out at the roughly $190 million that management described last quarter as a floor, not a ceiling. The reset rests on a gloomier housing assumption: existing-home sales down 5% to 10% and prices down 3% to 4%. Management noted that a flat market would imply about $200 million. That framing suggests the cut is macro-driven rather than a synergy shortfall, but it also means management is planning for another very challenging year. Higher mortgage rates are delaying any recovery.
Investor sentiment improved meaningfully into the report, rising from -0.51 to -0.16. It remains negative, but much less pessimistic. The stock tells a rougher story. Shares spiked to $28.85 on August 25, the first day of trading as REAX, then collapsed to a 52-week low of $13.25 on October 14. They closed at $16.99 on November 4, the day before the report. That price is 7.2% below the open after the prior report, 41% below the inter-earnings high, 28% above the low and 22% below the 200-day moving average of $21.78. The Earnings Whispers trend signals are mixed: momentum is positive, while price trend and AVWAP remain negative.
The bottom line is that Real REMAX delivered a messy but operationally encouraging first combined quarter. The revenue beat, accelerating adjusted EBITDA and faster synergies argue that the merger math is working. The EPS miss, decelerating Real growth, stalled agent counts and an outlook that slipped below last quarter's floor argue that the housing cycle is overwhelming the organic story. With the stock still far below its post-close high and new leverage on the balance sheet, investors will need evidence that synergies and Leo Pro monetization can outrun agent attrition and a shrinking market.
Read our earnings preview for The Real Brokerage Inc.: https://www.earningswhispers.com/article/REAX/22176
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-03 | |
| Oct-30 | |
| Oct-28 | |
| Oct-28 | |
| Oct-26 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-15 | |
| Oct-08 | |
| Oct-06 | |
| Sep-29 | |
| Sep-09 |
