Vistance Networks Beats On EPS, But A Third Guidance Cut And CEO Exit Overshadow A Cost-Driven Quarter
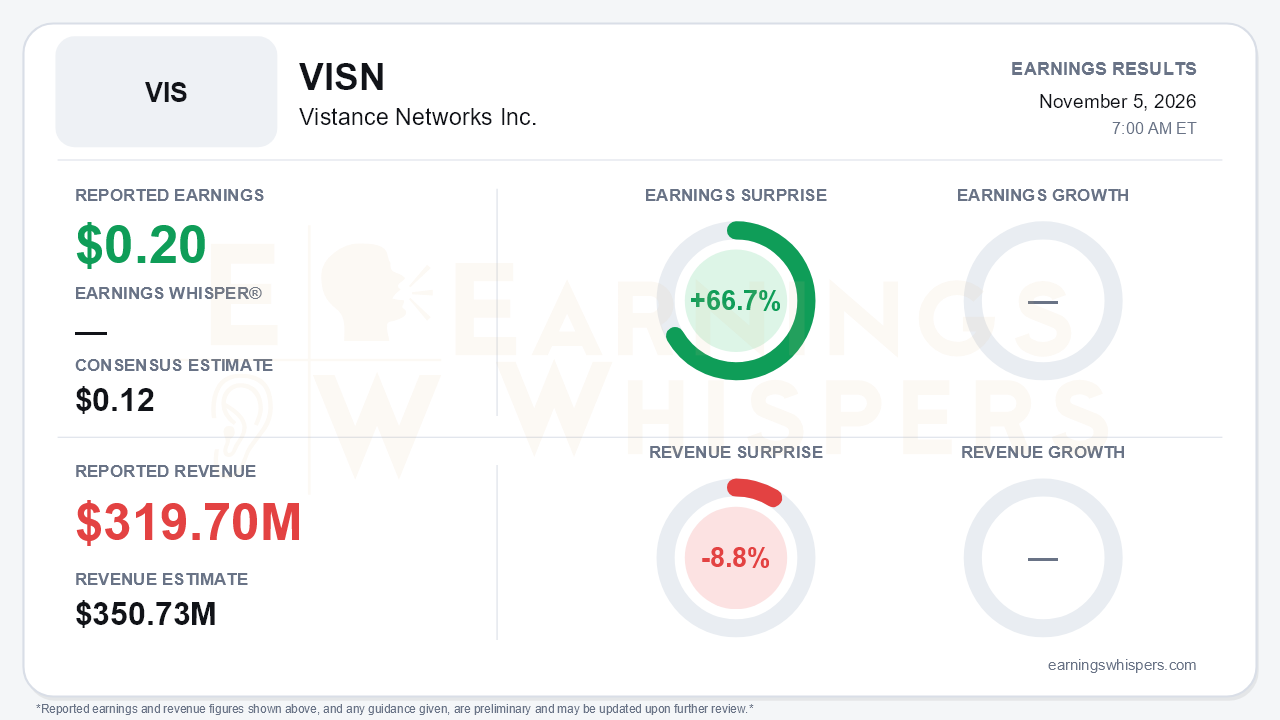
Vistance Networks delivered an earnings beat that does not hold up well under scrutiny. Earnings Whispers puts third-quarter EPS at $0.20, 66.7% above the $0.12 consensus. Revenue of $319.7 million missed the $350.73 million consensus by 8.8%. The company's own figures run higher: GAAP income from continuing operations of $0.24 per diluted share, against a $0.16 loss a year ago, and non-GAAP adjusted EPS of $0.23 versus $0.06. Whichever figure investors use, the central tension is the same. Profit beat on costs, interest income and taxes while the top line and the full-year outlook kept deteriorating. Management cut full-year Aurora adjusted EBITDA guidance for the second straight quarter and announced that CEO Chuck Treadway will step down on February 1, 2027.
The composition of the quarter deserves scrutiny.
- **Revenue fell.** Net sales declined 5.4% year over year. The U.S. was down 7.9%, Canada 24.5% and CALA 36.8%, which more than offset a 75% jump in EMEA.
- **Gross margin slipped.** Adjusted gross margin was 35.2%, down from 35.6% a year ago and well below Q1's 39.0%. Memory chip costs are the main drag.
- **Below-the-line items did much of the work.** Pretax income from continuing operations was $34.7 million. GAAP net income from continuing operations reached $54.7 million only because of a $20.0 million tax benefit. Interest income of $12.9 million on divestiture cash also helped.
- **Aurora's profit gain leaned on compensation.** Aurora adjusted EBITDA rose 5% to $56.8 million, a 17.8% margin. CFO Kyle Lorentzen credited lower variable compensation for more than offsetting memory pricing and stranded costs. Aurora GAAP operating income actually fell 9.8% to $23.0 million.
- **Opex cuts are real but may not fully repeat.** Adjusted operating expense dropped to 20.8% of sales from 32.2% a year ago. Some of that reflects stranded-cost work, but part looks like one-time relief.
The call showed a business losing momentum on the metrics that matter most.
- **Revenue trajectory:** Aurora growth went from +33% in Q1 to -1% in Q2 to -5% in Q3.
- **Guidance trajectory:** The full-year Aurora EBITDA outlook has moved from $225-250 million to $200-225 million to the current $180-200 million. Management blamed customer demand being pushed into 2027.
- **Customer pushouts:** Charter was referenced among large customers delaying amplifier orders for inventory and deployment-timing reasons. That matters for a business with roughly 70% customer concentration.
- **Memory headwind:** The estimated annual impact has grown from $20 million to about $40 million, following another price increase in Q3, with part rolling into 2027.
- **Inventory and cash flow:** Inventories swelled to $357.8 million from $238.7 million at year-end. Management does not expect normalization until the first half of 2027. Free cash flow was negative again at -$57.7 million.
- **No 2027 view:** Management said it was too early to give specifics.
There is a credible counterargument, and it centers on orders. Aurora orders rose 41% year over year after falling 55% in Q2, and backlog of $410 million was up 3% from a year ago. However, backlog fell sequentially from $470 million. Other forward catalysts include:
- Ziggo's first large-scale live deployment of unified DOCSIS 4.0 nodes.
- A three-year VC-CAP EVO remote PHY award at O2.
- ESD amplifier shipments expected to ramp in 2027.
- A PKI/security push, roughly a $10 million business today, targeting a market management sizes at about $700 million and growing around 15% a year.
The common thread is timing. Most of the upside sits in 2027, under a new CEO who has not yet been named.
Capital returns remain the most tangible support. A new $1.50 special distribution brings 2026 distributions to $16.50 per share. Buybacks of $225 million have retired 28.9 million shares, about 13% of the Q2 count, and the authorization was raised by $100 million to $350 million. The company is debt-free with $683.1 million of cash. That generosity has a cost, though: projected year-end cash is now $275-300 million, down from the $700-750 million guided last quarter.
Investor sentiment remained negative but improved meaningfully, moving from -0.65 to -0.47. The price action has been harsh. Shares were at $6.44 entering the report, down 41.3% from the $10.97 open after the August release. They sit 49.6% below the 200-day moving average and just 11.8% above the 52-week low of $5.76 set October 20. Some of that decline likely reflects the roughly $1.12 billion in special distributions paid during the quarter, so the raw price change overstates the value lost. Even so, momentum and AVWAP trend readings remain negative.
The bottom line is that Vistance's EPS beat was built on lower variable compensation, cost cuts, interest income and a tax benefit. It was not built on demand, which slipped further into 2027 alongside a third consecutive guidance reduction. Rebounding orders and DOCSIS 4.0 wins keep the longer-term story intact, and capital returns have been substantial. Still, bears have legitimate ammunition in the falling revenue, negative cash flow, rising memory costs and a leadership transition, and the next leg of the thesis depends on a 2027 that management has not yet framed.
Read our earnings preview for Vistance Networks Inc.: https://www.earningswhispers.com/article/VISN/22207
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 9 hours | |
| 9 hours | |
| Oct-28 | |
| Oct-15 | |
| Oct-14 | |
| Sep-29 | |
| Sep-28 | |
| Sep-28 | |
| Sep-08 | |
| Aug-26 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-21 |
