Upland Software Resets The Story: Churn Turns Organic Growth Negative And Pushes Growth To 2028, Leaving A 35% Margin Target To Carry The Thesis
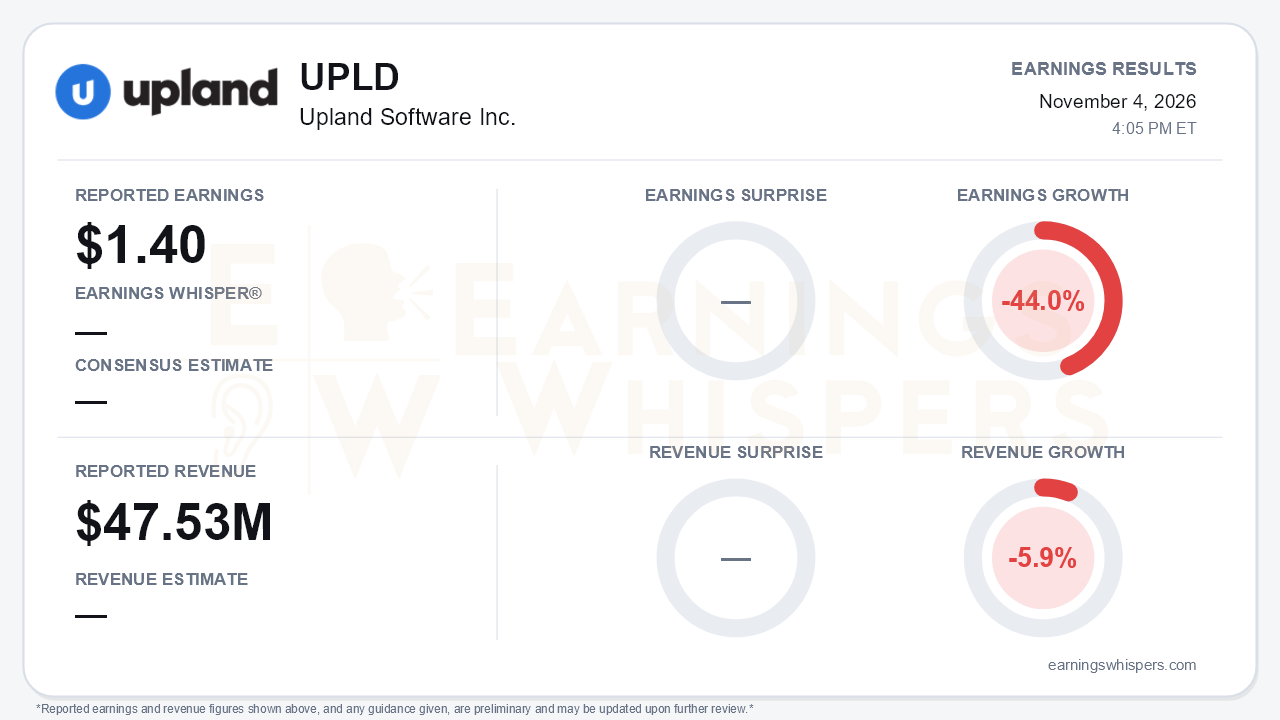
Upland Software's third quarter was less about the numbers and more about a reset. On Earnings Whispers' normalized basis, the company earned $1.40 per share on revenue of $47.53 million. Earnings fell 44.0% from a year ago and revenue declined 5.9%. No consensus or Whisper figure was available, so there is no surprise to measure. The more meaningful benchmark is Upland's own prior framework, and against that the quarter fell short. Core organic growth swung to -3.9%. Full-year guidance moved lower. The new management team now treats 2027 as a stabilization year, with revenue growth deferred to 2028. In exchange, investors got a higher margin ambition: roughly 35% adjusted EBITDA margin in the first half of 2028. That is the central tension. The company is asking shareholders to underwrite margin expansion on a shrinking revenue base.
The quality of the quarter deserves scrutiny. Revenue landed above the midpoint of guidance ($45.7 million to $48.7 million). Adjusted EBITDA of $12.6 million met the midpoint. Margin improved sequentially to 27% from 26%. But adjusted EBITDA fell from $16.0 million a year ago, and margin dropped from 32%. Subscription and support revenue, the recurring core, declined 5% to $45.3 million. Professional services fell roughly a third. Upland's own non-GAAP diluted EPS was $1.71 versus $2.97 a year ago, which differs from the Earnings Whispers normalized figure. The direction is the same either way: sharply lower. On a GAAP basis, the net loss narrowed to $0.5 million from $1.1 million. That improvement was helped by much lower stock-based compensation and the absence of last year's divestiture and debt-extinguishment charges, and it came despite interest expense rising to $5.1 million from $4.2 million. Free cash flow was $2.7 million versus $6.7 million. Management noted the year-ago figure included a $5.4 million swap benefit.
The call explained why the trajectory bent. Three customer churn events drove the miss against the prior plan. Some came from financially stressed customers cutting usage. Others came from customers retiring legacy applications in favor of AI tools. That second category matters because it cuts directly against the company's pitch as an AI-era knowledge layer. Leading indicators also softened:
- New customers fell to 77 (10 major) from 97 (14 major) a year ago and 110 in the fourth quarter of 2025.
- Deferred revenue slipped sequentially to $69.7 million from $71.6 million.
- Gross margin eased to 76% from 77% as cloud hosting and compute costs rose.
Management described the full-year revenue and EBITDA ranges as narrowed for churn. In practice they were lowered. Revenue guidance is now $190.1 million to $193.1 million, versus $194.2 million to $206.2 million previously. Adjusted EBITDA guidance of $50.5 million to $52.0 million sits entirely below the prior $52.6 million low end. Fourth-quarter guidance implies a 6% revenue decline and a 29% EBITDA margin, versus 31% a year ago. Compounding the visibility problem, Upland will stop reporting core organic growth after this quarter, just as the metric turned negative.
The forward case rests on execution under new leadership. CEO Sean Nathaniel started in May and CFO Jennifer Simon in August. Their three-phase plan runs from Simplify and Delever, to Stabilize and Expand, to Grow. Several pieces support it:
- Carahsoft, named master government aggregator, opens public-sector channels for four products.
- Management positioned channel partnerships as the main near-term growth lever.
- Six-figure wins included a Canadian police force, a Big Four expansion, and a healthcare capture deployment.
- Scheduled term loan amortization steps down to 1.75% from 2.5%, freeing cash for voluntary paydown.
The term loan has fallen to $225.4 million from $238.5 million at year-end. Still, net leverage of 3.7x on a declining EBITDA base leaves little room for error. The new 35% margin target exceeds the old 32% long-term model, but it replaces nearer-term targets that slipped: 29%+ for 2026 and 31%+ for 2027. Bears have legitimate ammunition in that pattern of deferral.
The market had already been skeptical. Shares opened at $5.07 after the August report, below the 200-day moving average of $6.34. The July Nasdaq notice for failing the $15 million minimum market value of publicly held shares reflects a thin public float and depressed valuation. The company has until January 27, 2027, to regain compliance. Management says, as a sponsor-backed company with HGGC behind it, that listing status should not affect operations. Even so, the notice is an overhang for public holders. Current sentiment and price data were not available to gauge the immediate reaction.
The bottom line is that Upland traded growth credibility for margin ambition this quarter. The headline revenue beat against guidance was real but narrow. Underneath it, organic growth turned negative, new-logo momentum faded, guidance moved below prior ranges, and a key disclosure metric is going away. The 35% margin target and steady debt reduction give the new team a credible self-help path. Until churn stabilizes and channel partnerships produce measurable bookings, however, the investment case depends more on cost discipline than on demand.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Oct-22 | |
| Aug-25 | |
| Aug-17 | |
| Aug-14 | |
| Aug-14 | |
| Aug-06 | |
| Jul-28 | |
| Jul-21 | |
| Jul-08 | |
| Jun-04 | |
| Jun-04 | |
| May-26 |
