Teads' Enterprise Turnaround Reverses As Revenue Drops 26%, EBITDA Turns Negative And The Focus Shifts To Debt Talks
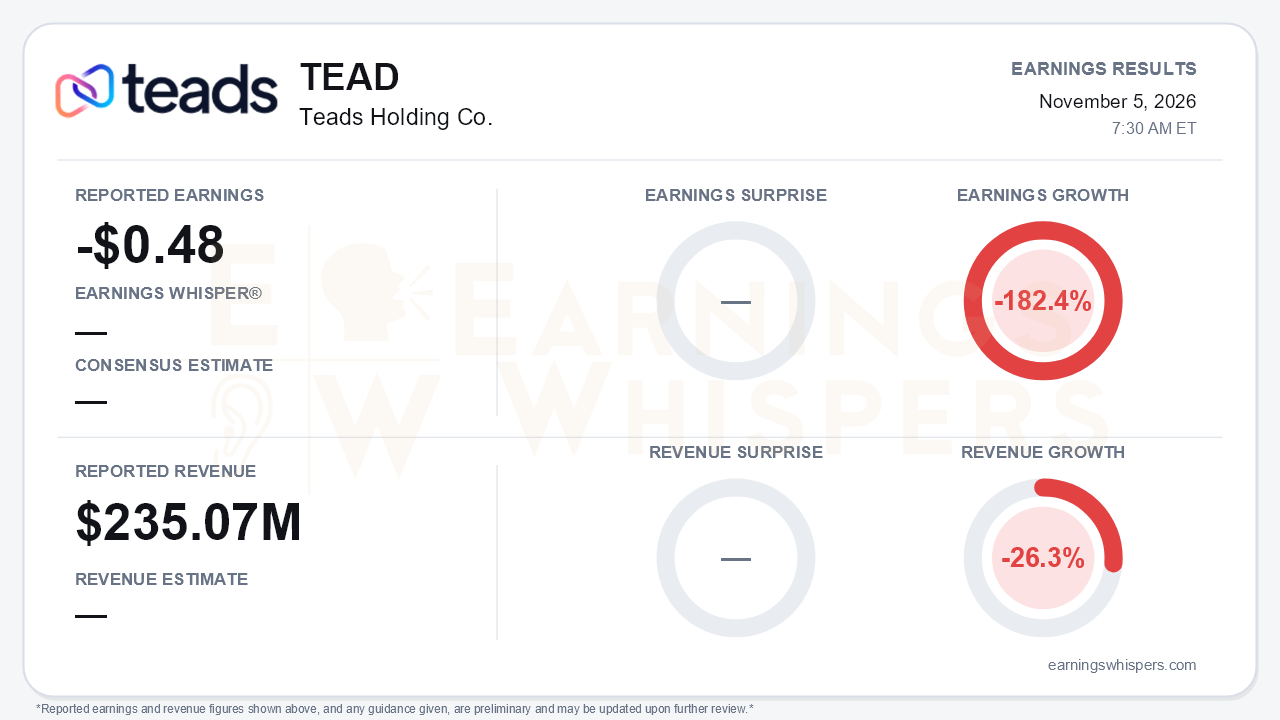
Teads Holding Co. (NASDAQ: TEAD) reported an adjusted loss of $0.48 per share on revenue of $235.07 million for the September quarter. Earnings fell 182.4% year over year and revenue fell 26.3%. No consensus estimate or whisper number was available, so the quarter cannot be judged as a beat or a miss. That matters less than the direction of the business, which is getting worse quickly. Revenue declines have widened from 7% in Q1 to 17% in Q2 and 26% now. Adjusted EBITDA turned negative. The enterprise recovery management promised last quarter went backward instead. The central story is no longer whether Teads can return to growth. It is whether the company can stabilize operations fast enough to manage a heavy debt load.
The GAAP numbers look worse still. Teads lost $325.5 million, or $3.31 per share, versus a $19.7 million loss a year ago. That figure includes:
- a $272.4 million non-cash charge that wrote off all remaining goodwill;
- a $6.4 million impairment of a publisher commercial agreement asset.
The goodwill charge follows roughly $350 million of impairments in Q4 of fiscal 2025. Back-to-back write-downs of this size amount to an admission that the Legacy Teads acquisition is worth far less than was paid. Stockholders' equity is now a deficit of $318.2 million.
The operating results underneath are also weak. GAAP gross margin fell to 25.9% from 33.2%. Ex-TAC gross profit, which strips out the traffic payments made to publishers, fell 28% to $93.5 million, and Ex-TAC margin slipped to 39.8% from roughly 41%. Adjusted EBITDA swung to negative $8.1 million, down from $19.2 million a year ago, $7 million in Q2 and $37 million in Q4 of fiscal 2025. Operating expenses fell about 10%, but that is nowhere near enough to offset the drop in Ex-TAC gross profit.
The call showed weakness on two fronts.
- **Enterprise business.** Enterprise Ex-TAC gross profit fell 14% to $75 million, versus a decline of about 6% in Q2. North America was down 15%, and EMEA was weak in August. On the Q2 call, management said the low point was behind the company and guided to mid-single-digit enterprise growth in the second half. That expectation has now failed outright.
- **Direct-response/SME business.** Ex-TAC gross profit here collapsed 50% to $20 million, versus a 30% decline in Q2. Management blamed AI-generated search summaries, which have cut publisher page views by 20% to 60%. In Q2 the company cited declines of 15% to 25%.
This looks like a structural problem for open-web advertising rather than a cyclical slowdown. Management's tone reflects the shift. Q4 described a "breakout year" and Q1 was "confident." This quarter was framed as a challenging period the company hopes will improve.
Connected TV (CTV) remains the credible growth story. CTV revenue rose 37%, now makes up about 12% of total revenue and roughly 20% of the enterprise business, and has reached nearly $100 million year to date. Other positives:
- an expanded HomeScreen footprint, including the Whale TV and Telly deals;
- joint business partnership renewals with BMW, Lenovo, Shell and Kia;
- the agentic Teads Ad Manager launch;
- participation in OpenAI's ChatGPT ad pilot;
- APAC enterprise growth of 5%.
Still, CTV growth slowed from 67% in Q2 and more than 50% in Q1. The segment is too small to offset declines in the core business. Management said October showed some improvement, CTV growth reaccelerated, and page-view declines may be bottoming. Investors should treat that as management's view, not reported results. Guidance remains suspended, so there is no formal outlook to hold the company to.
The balance sheet is the main risk. Cash fell to $90.3 million from $128.2 million at year-end. Total debt is $657.2 million, mostly 10% senior secured notes due 2030 with principal the release puts at $628.2 million. The call summary refers to these as €628 million notes, so the currency should be verified.
Interest is the problem in plain terms. Free cash flow before interest was close to breakeven at negative $1.4 million. Cash interest of $31.7 million turned that into negative $33.1 million of free cash flow. The company is not generating enough cash to service its debt.
Teads is drawing on new sources of liquidity:
- $15 million drawn on its revolver;
- a new receivables facility, with $30.9 million drawn at quarter-end per the release. The call cited about $55 million drawn on a $125 million facility, which likely reflects activity after quarter-end.
Management put total liquidity at roughly $140 million. It also disclosed constructive talks with debt holders, and CFO Jason Kiviat is departing. Equity holders should read both developments carefully.
The market had largely priced in distress before this report. Shares opened at just $0.63 after the August release, below the current 200-day moving average of $0.74. The release also cites the company's need to regain compliance with Nasdaq listing requirements. Current price and sentiment data were not available, so we cannot say how investors reacted to this quarter. But a sub-dollar stock with a negative equity balance and active creditor negotiations means debt holders largely determine the outcome for shareholders.
The bottom line is that Teads' third quarter weakened the investment case on almost every measurable front. Revenue and Ex-TAC declines accelerated, EBITDA turned negative, the promised enterprise recovery reversed, and a second large impairment wiped out the remaining goodwill. CTV and the new product launches are real assets, and October may prove to be the low point. Until the company shows a sustained revenue recovery and reaches a clear resolution with its noteholders, the balance sheet will matter more to the stock than CTV growth.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-03 | |
| Oct-29 | |
| Oct-22 | |
| Sep-29 | |
| Sep-29 | |
| Sep-15 | |
| Sep-10 | |
| Aug-18 | |
| Aug-06 | |
| Aug-06 | |
| Aug-03 | |
| Aug-03 |
