SAB Biotherapeutics Beats On A Narrower-Than-Expected Loss As SAFEGUARD De-Risks Execution, But Rising Burn Moves The Focus To 2027 Data
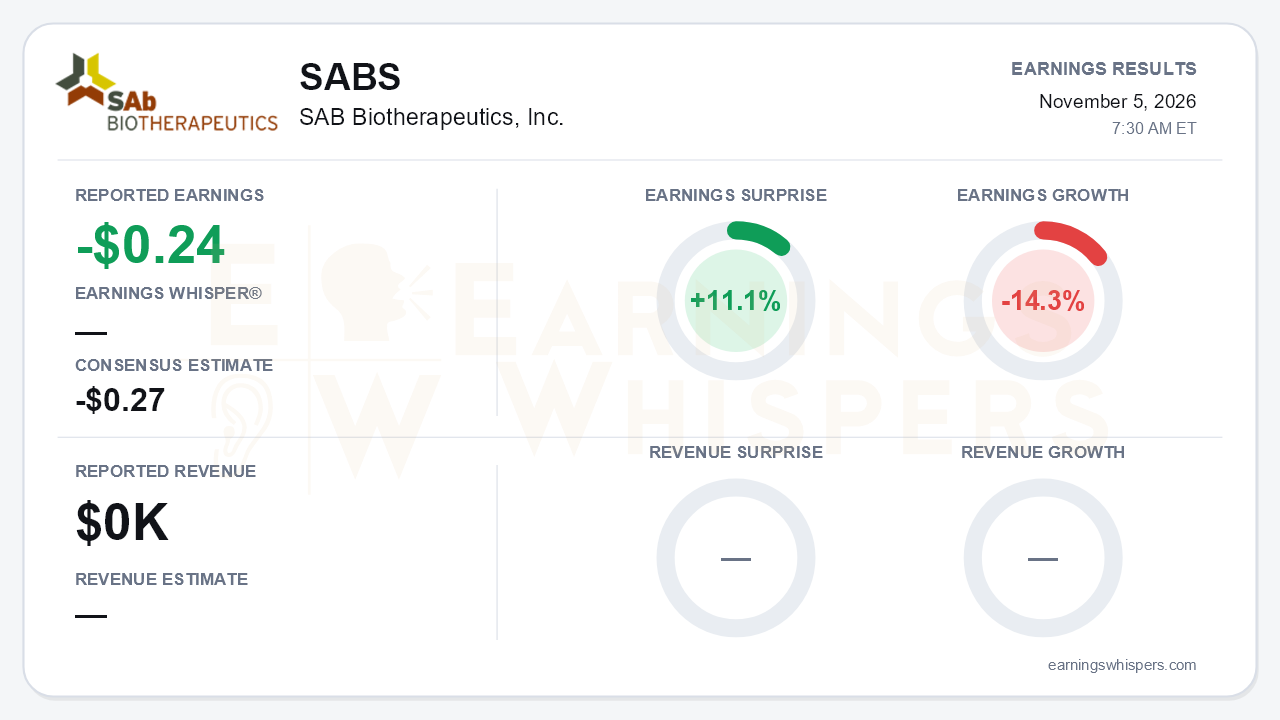
SAB Biotherapeutics (NASDAQ: SABS) reported a third-quarter loss of $0.24 per share, beating the consensus estimate of -$0.27 by 11.1%. Earnings fell 14.3% year over year on Earnings Whispers' normalized basis, and the company again reported no revenue. For a clinical-stage company, the EPS beat matters less than what changed in the program. The quarter's central development was execution on SAB-142. The adult and adolescent cohorts of the registrational SAFEGUARD study are fully enrolled. The final pediatric stepdown was approved. The FDA granted Fast Track designation. That is the story investors will price, not the beat.
The quality of the income-statement comparison deserves scrutiny. On a GAAP basis, the year-ago quarter showed net income of $45.4 million. That figure was driven by $58.1 million in other income, primarily from changes in the fair value of warrant liabilities, so the reported swing to a $22.3 million net loss overstates any operating deterioration. The real cost trend is still unmistakably higher:
- **R&D:** $18.1 million, up from $9.0 million a year ago and $13.4 million in the first quarter.
- **G&A:** $7.8 million, up from $3.7 million a year ago and $6.6 million in the first quarter.
- **Stock-based compensation:** A meaningful share of the increase is non-cash. It totaled roughly $7.5 million across R&D and G&A, versus $0.8 million a year earlier.
- **Net loss:** Widened from $18.9 million in the first quarter.
The beat came against a rising spending base, which is what a company running a ~159-patient registrational trial across more than 60 sites should look like.
The call preserved a credible growth story for the program, and it marked clear sequential progress:
- **Pediatric enrollment:** Management was still waiting on the pediatric stepdown during the second-quarter call. In September, the Data Monitoring Committee approved expansion to ages 5–11 with no new safety signals. SAFEGUARD remains on track for full enrollment in the fourth quarter and topline data in the second half of 2027.
- **PRISE-hATG:** The investigator-led Phase 3 trial moved from planning to expecting first patient dosed in the fourth quarter. It is funded by Breakthrough T1D and could extend the label to patients up to two years post-diagnosis. Management described physician demand as very high.
- **Fast Track:** The designation brings more frequent FDA interaction, rolling BLA eligibility and potential priority review. It builds on the C-peptide surrogate-endpoint confirmation disclosed earlier in the year.
- **Tzield:** Management's tone shifted from "too soon to draw conclusions" last quarter to being "very encouraged" by the drug's uptake, which it now frames as validation of the market.
None of the guidance was raised. It was reaffirmed.
Bears have legitimate ammunition:
- **Cash decline:** Cash and investments fell to $205.3 million from $217.6 million at the end of the first quarter, even after $13.4 million in warrant-exercise proceeds.
- **Runway:** Guidance through 2028 is unchanged, and management said PRISE costs are already embedded in burn guidance. The cushion beyond the 2H 2027 SAFEGUARD readout is not enormous if spending keeps climbing.
- **PRISE timing:** Management declined to reiterate data timing on this call after citing a first-quarter 2029 topline last quarter, framing PRISE as investigator-led and subsequent to SAFEGUARD.
- **Disclosure gaps:** Redosing patient counts remain undisclosed, and Phase 1 durability data do not extend beyond day 120.
- **Competition:** Tzield's approval and uptake in Stage 3 cut both ways. It validates the market but raises the bar. SAB-142's differentiation will ultimately rest on C-peptide, HbA1c and immunogenicity data that do not yet exist in registrational form.
Investor sentiment improved meaningfully heading into the report, rising from -0.26 to -0.09. It remained negative, but skepticism has clearly eased. The price action tells a rougher story. Shares closed at $3.18 ahead of the release, down 15.4% from the $3.76 opening after the August report and 13.4% below the 200-day moving average of $3.67. The stock peaked at $3.99 in late August, then slid to a 52-week low of $2.44 on October 19. It has since rebounded about 30% off that low but still sits roughly 20% below the quarter's high. The Earnings Whispers trend readings are mixed: price and sequential-growth trends are negative, while AVWAP is positive.
The market setup is more complicated than the surprise implies. The fundamentals that matter for SAB, enrollment velocity and regulatory standing, clearly improved this quarter. The stock, however, has spent most of the period being sold. The recent bounce looks more like a repair of damage than a re-rating.
The bottom line is that SAB delivered the operational quarter it needed: adult and adolescent enrollment closed, the pediatric cohort opened, Fast Track was secured and PRISE is about to dose. The modest EPS beat is incidental. What has changed is that execution risk on SAFEGUARD has fallen, while the investment debate narrows to cash burn and the 2H 2027 topline data that will determine whether SAB-142 can differentiate in a market Tzield is already building.
Read our earnings preview for SAB Biotherapeutics, Inc.: https://www.earningswhispers.com/article/SABS/22454
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-05 | |
| Nov-05 | |
| Oct-29 | |
| Oct-29 | |
| Oct-14 | |
| Oct-13 | |
| Oct-01 | |
| Sep-22 | |
| Sep-01 | |
| Aug-06 | |
| Aug-06 | |
| Jul-30 | |
| Jul-07 | |
| May-29 |
