Playtika's Record-Margin Beat Relies On Marketing Cuts As Its Audience Shrinks And The Strategic Review Ends Without A Deal
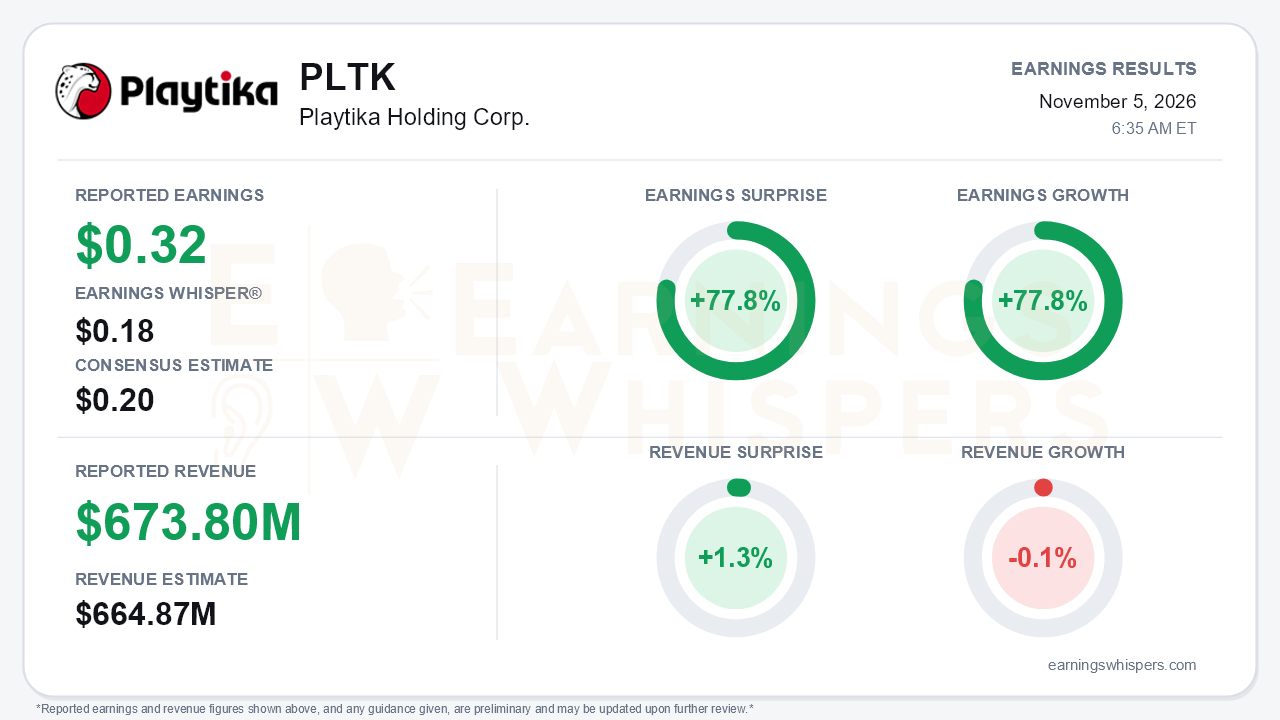
Playtika delivered a clean beat by the numbers. Adjusted earnings of $0.32 per share topped the $0.20 consensus by 77.8% and cleared the $0.18 Earnings Whisper. Revenue of $673.8 million edged past the $664.87 million estimate by 1.3%. Earnings grew 77.8% year over year while revenue slipped 0.1%, and that gap is the story of the quarter. Playtika is generating more profit from a smaller, more heavily monetized audience, mainly by spending less to acquire players. Record adjusted EBITDA of $252.1 million and a 37.4% margin show strong cost discipline. They do not show renewed growth.
The quality of the beat deserves scrutiny. The $0.32 figure reflects adjusted net income of $120.7 million, which excludes an $80 million revaluation of SuperPlay contingent consideration. On a GAAP basis, net income was $40.4 million, or $0.11 per share, unchanged from a year ago. The margin expansion came largely from lower spending. Sales and marketing fell to $167.8 million from $206.3 million, R&D dropped about 12%, and stock-based compensation fell to $6.0 million from $21.8 million. Meanwhile, G&A jumped to $123.9 million and the tax provision consumed more than half of pretax income. Revenue declined 7.8% sequentially, and year-over-year growth decelerated to flat from +5.5% in Q1. The release also shows that adjusted EBITDA margin climbed from 16.8% in Q1 to 28.2% in Q2 to 37.4% in Q3. That trajectory reflects a planned step-down in marketing, and management said explicitly that this was the plan.
Beneath the headline, user trends weakened. Average DAUs fell to 7.1 million from 8.2 million a year ago, and MAUs dropped to 21.5 million from 26.4 million. Paying users declined 5.9% to 333,000, down from 387,000 in Q1. Monetization offset much of that erosion. ARPDAU rose to $1.03 from $0.89, and payer conversion improved to 4.7%. The portfolio split sharply:
- **Bingo Blitz**, the largest title, fell 18.2% year over year to $133.0 million, down from $153.7 million in Q1. Management acknowledged the decline was steeper than planned.
- **Disney Solitaire** grew 88.4% year over year but dropped 21.9% sequentially as user acquisition was pulled back.
- **June's Journey** was a genuine bright spot, growing 12.1% in its ninth year.
- **Slotomania** improved from roughly -50% a year ago to near flat.
- **DTC revenue** rose 31.4% and reached 40.8% of sales, hitting a two-year target early. That shift structurally supports margins.
The forward picture was firmer than the quarter itself. Playtika reaffirmed full-year guidance of $2.75 to $2.85 billion in revenue and $750 to $790 million in adjusted EBITDA. It also lifted its positioning to around the midpoint, after framing the bottom end on the Q2 call. Management's tone was more confident, emphasizing a fourth straight year of meeting EBITDA guidance and a now-profitable SuperPlay. Two catalysts carry into Q4: the launch of a permanent Leagues feature in Bingo Blitz, and lapping the exit from an acquisition channel. Still, the strategic review concluded with Playtika staying independent. Investors hoping for a takeout got a balance-sheet repair story instead.
That balance sheet is where bears have legitimate ammunition. Cash fell to $594.6 million from $779.2 million in Q1. Long-term debt stands at $2.37 billion, and stockholders' equity remains in deficit. The $550 million revolver expires in March 2027, another earn-out payment is due from cash in Q2 2027, and 2028 maturities must be refinanced. Management intends to refinance without increasing total debt, though terms depend on market conditions. Two figures in the source materials do not line up:
- The call cited a $461 million earn-out payment, while the cash-flow statement shows $350 million of contingent consideration within financing activities.
- The call referenced roughly $288 million of nine-month free cash flow, while the release reports $177.5 million.
The reported figure makes the full-year target of more than $400 million look back-end loaded. Even that target trails the record $481.6 million posted in FY25.
The market had already turned hostile. Shares entered the report at $2.12, down 38.9% from the $3.47 open following the August release and 30.8% below the 200-day moving average of $3.06. The stock set a 52-week low of $1.89 on October 30 and sat only 12.5% above it. It had also surrendered roughly 40% from the inter-earnings high, which was set the day after the last report. Investor sentiment, already negative, deteriorated modestly from -0.33 to -0.40. Price momentum and AVWAP trend readings remain negative, consistent with a stock that has been sold steadily all quarter.
The bottom line is that Playtika beat expectations on cost control rather than growth. Record margins, rising DTC mix and midpoint guidance give management credibility on execution. However, a shrinking audience, a faltering Bingo Blitz, flat GAAP earnings and a looming refinancing leave the core questions unresolved. With the takeover option off the table and sentiment souring, the stock now depends on stabilizing engagement and refinancing on reasonable terms. Adjusted earnings beats alone are unlikely to change that.
Read our earnings preview for Playtika Holding Corp.: https://www.earningswhispers.com/article/PLTK/22168
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 7 hours | |
| 7 hours | |
| Oct-28 | |
| Oct-16 | |
| Oct-12 | |
| Oct-01 | |
| Aug-06 | |
| Aug-06 | |
| Jul-17 | |
| Jun-02 | |
| May-28 | |
| May-07 | |
| May-07 | |
| Apr-16 |
