BD Ends Its Transformation Year With Its Strongest Quarter, But A Modest FY27 Guide Tests A Stock Priced For Momentum
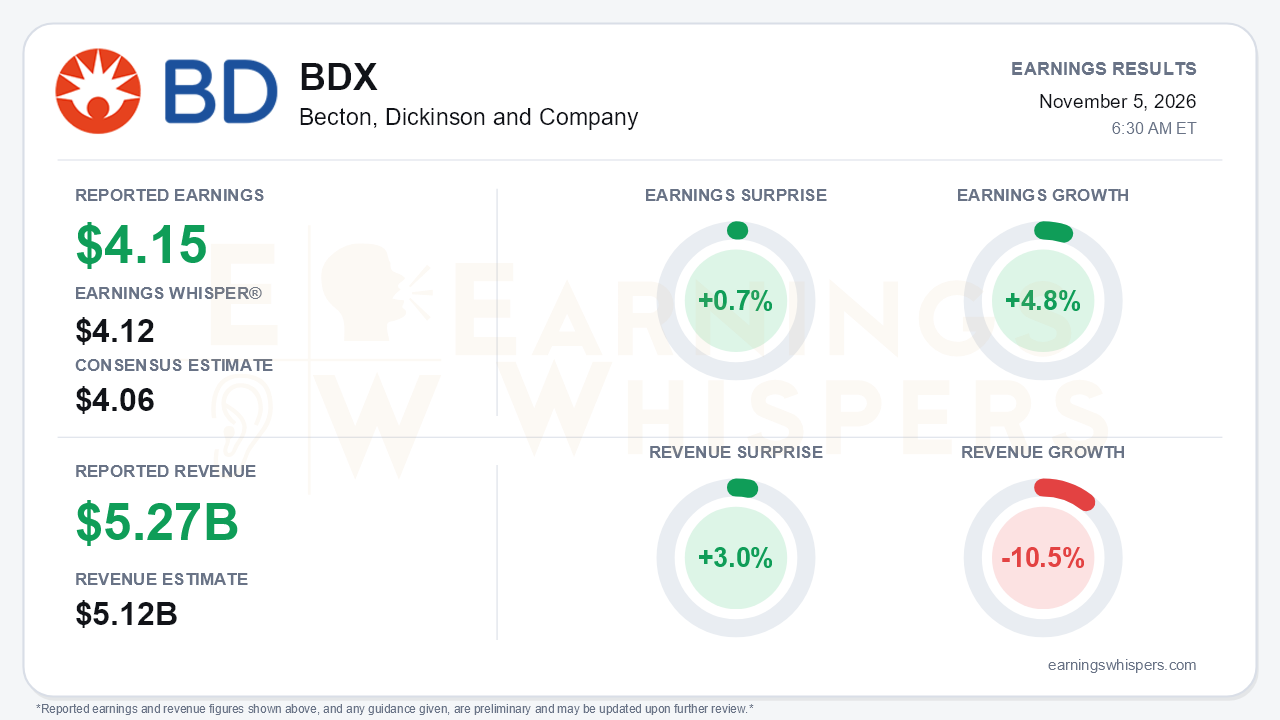
Becton, Dickinson and Company delivered the cleanest quarter of its separation year. Fiscal fourth-quarter adjusted earnings of $4.15 per share topped the $4.06 consensus by 0.7% and edged past the $4.12 Earnings Whisper number. Revenue of $5.274 billion beat the $5.12 billion consensus by 3.0%, the more meaningful of the two surprises. The central tension is that BD exited fiscal 2026 accelerating, while its fiscal 2027 framework calls for a slower year. Management guided to low single-digit revenue growth and adjusted EPS of $13.10 to $13.30. That works out to roughly 3% to 5% growth, below the 6.7% delivered in fiscal 2026.
The growth comparisons need context. On Earnings Whispers' normalized basis, earnings grew 4.8% year over year and revenue fell 10.5%. BD's own figures show something different: revenue up 5.4% (5.6% currency-neutral) and adjusted EPS up 27.3% against a recast year-ago base of $3.26. The gap appears to reflect the February spin-off of the Biosciences and Diagnostic Solutions business into Waters. BD restated prior periods as continuing operations, which changes the comparison base.
On the continuing-operations basis that management is steering by, the trajectory is clearly improving. Currency-neutral growth stepped up every quarter, from 2.6% in the fiscal second quarter to 4.4% in the third and 5.6% in the fourth. Adjusted operating margin swung from 24.9% in the third quarter, down 130 basis points, to 28.6% in the fourth, up 280 basis points. Adjusted gross margin rose 180 basis points to 56.8%.
The quality of the beat holds up reasonably well, with some caveats:
- **Tariff refund excluded.** A $66 million benefit from refunded IEEPA tariffs was stripped out of adjusted results rather than flattering them.
- **Buybacks helped.** Diluted shares fell to 274 million from 287 million after $2.4 billion of repurchases, so per-share growth benefited.
- **GAAP comparison is distorted.** GAAP EPS from continuing operations more than doubled to $2.52 from $1.20. The year-ago quarter absorbed $232 million of legal charges and carried an unusually low tax provision.
- **Cash flow is the strongest evidence.** Free cash flow rose 42.5% to $2.9 billion, with conversion near 74% versus roughly 57% a year earlier. Long-term debt dropped to $13.4 billion from $17.6 billion.
Beneath the consolidated number, the mix tells the story:
- **Interventional:** up 7.6%, with Peripheral Intervention accelerating every quarter.
- **BioPharma Systems:** up 7.0%, a sharp recovery from a 1.8% decline in the second quarter. The vaccine drag halved to roughly an 11% decline and is expected to disappear in fiscal 2027.
- **Specimen Management:** up 9.4%.
- **Connected Care:** the soft spot at 2.1%. Medication Management Solutions slipped 2.2% currency-neutral, including a 5.6% U.S. decline, as the business laps prior Alaris infusion-pump volume. Advanced Patient Monitoring offset part of that with 17.3% growth.
Management said Alaris share gains exceeded 250 basis points for the year and that ex-Alaris growth ran near high single digits in the quarter.
That Alaris comparison is the crux of fiscal 2027. Management quantified it as follows:
- **Revenue:** roughly a 200-basis-point headwind for the year and about 250 basis points in the first quarter.
- **Margin:** about 60 basis points of drag, alongside resin and oil inflation, leaving adjusted operating margin roughly flat.
- **First quarter:** EPS guided to $2.32 to $2.37, with revenue at the low end of the range. Part of that caution stems from an Advanced Patient Monitoring ERP system cutover.
Bears have legitimate ammunition. China pricing pressure lingers, and a competitor's caution on 2027 GLP-1 glass packaging adds uncertainty to BioPharma.
The offsets are tangible:
- **Product launches:** FDA approval of the Liverty TIPS stent graft, clearance for Phasix ST peristomal mesh, and the Vmax pharmacy robot launch, which won all six central-fill opportunities in the quarter.
- **Software:** 95% to 100% attachment of the AI platform on new Pyxis placements.
- **Capital return:** a new buyback authorization.
- **Tariff option:** a $19 billion U.S. investment pact offering Section 232 tariff relief. Management characterized the investment as reprioritized rather than incremental, and the relief is not in guidance.
Management's tone was more confident. Executives reiterated mid-single-digit growth and margin expansion for fiscal 2028 ahead of the December 10 Investor Day.
The market setup is more complicated than the surprise implies. Shares entered the report at $209.19, up 18.9% since the open after the August release. That put them 0.3% below their inter-earnings high and 23.2% above the 200-day moving average. Price, momentum, and AVWAP trend readings were all positive. Investor sentiment, by contrast, was essentially unchanged and still negative, moving from -0.31 to -0.30. The stock has rallied without a matching improvement in investor conviction. That leaves it exposed to a guide whose headline growth looks pedestrian, even though management had previously signaled only modest fiscal 2027 leverage.
The bottom line is that BD proved the New BD can accelerate, with improving growth, margins, and cash generation, but fiscal 2027 is a bridge year defined by the Alaris comparison and a soft first quarter. With shares near their recent highs, the burden now shifts to the December Investor Day to make fiscal 2028 targets credible enough to look past it.
Read our earnings preview for Becton, Dickinson and Company: https://www.earningswhispers.com/article/BDX/22052
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 6 hours | |
| 10 hours | |
| 10 hours | |
| 10 hours | |
| Nov-04 | |
| Oct-28 | |
| Oct-28 | |
| Oct-15 | |
| Oct-14 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Oct-07 | |
| Oct-07 |
