Appian Crushes Estimates And Raises Guidance A Third Time, But Lumpy On-Prem Revenue And A Cash Drain Complicate A 65% Rally
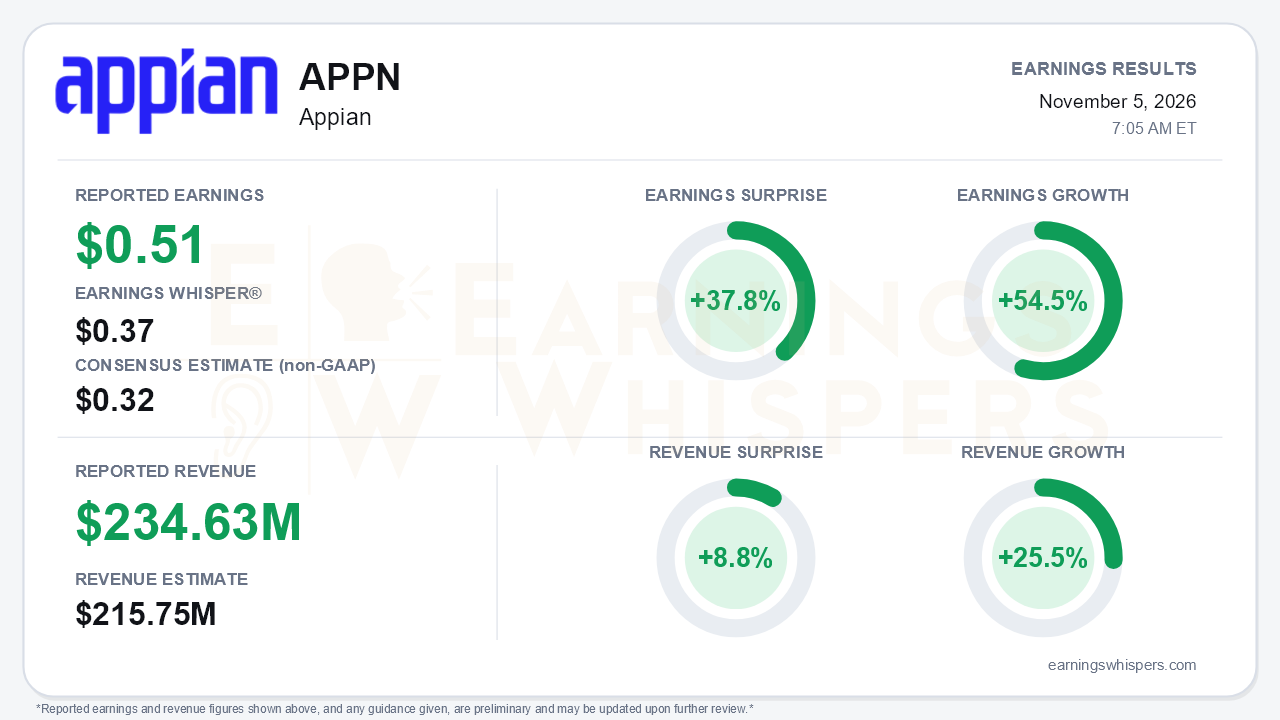
Appian delivered the kind of quarter that forces a rethink of its growth ceiling. Non-GAAP earnings of $0.51 per share beat the $0.32 consensus by 37.8% and cleared the $0.37 Earnings Whisper number. Revenue of $234.63 million topped the $215.75 million consensus by 8.8%. Earnings grew 54.5% year over year and revenue rose 25.5%, which management said was roughly six points faster than the prior quarter. Management also raised every full-year guidance line for the third consecutive time. On the call, it described the period as "by far the strongest quarter in Appian history," a notable shift from the cautious optimism of earlier in the year. The central tension is that the acceleration was real but not uniform. A meaningful slice came from lumpy, upfront-recognized revenue, and it arrived alongside negative operating cash flow and a sharply smaller cash cushion.
The quality of the beat deserves scrutiny. Total subscriptions revenue jumped 28% to $187.8 million, about nine points faster than the prior quarter. Cloud subscriptions, the recurring core, grew a steadier 20% to $136.4 million. The gap came from self-managed deployments, driven by European data-sovereignty and public-sector demand. Under ASC 606, roughly 70% of that revenue is recognized upfront. That flatters a single quarter and makes comparisons choppy, and the fourth-quarter guide implies non-cloud subscriptions will dip slightly. Professional services revenue rose 18%, but services gross margin slid to 24% from 31% the prior quarter. Overall gross margin still improved to 74% from 72%. On a GAAP basis, the picture is real but more modest. Operating income rose to $21.3 million from $13.1 million, and diluted EPS reached $0.17 versus $0.10. The non-GAAP figures exclude $4.7 million of Pegasystems litigation expense, which more than doubled from a year ago.
Beneath the headline, the strongest evidence of improving fundamentals is retention. Cloud net ARR expansion climbed to 120% from 115% in each of the first two quarters and 112% a year ago, the best reading in more than five years. Management cited AI usage rising more than 50% sequentially, with usage bundles and overages emerging as an added monetization lever, though it said this is not yet material. Federal momentum also looks tangible: a seven-figure procurement-automation deal at a cabinet-level agency, and a prime contract with a military branch after another integrator's implementation failed. Most importantly, the fourth-quarter guide calls for cloud growth of 22% to 24%, a further acceleration from 20% and in the mid-20s at constant currency. That figure, more than the one-time self-managed spike, is what supports a durable growth story.
The guidance progression is striking. Full-year cloud revenue moved from $502-510 million in February to $536-538 million. Total revenue went from $801-817 million to $873-877 million, adjusted EBITDA from $89-99 million to $116-119 million, and non-GAAP EPS from $0.82-0.96 to $1.20-1.24. Still, the near term softens. Fourth-quarter total revenue growth is guided to just 15% to 17%. Currency has turned into a two-to-three-point headwind after previously being expected to be neutral. Adjusted EBITDA of $30-33 million steps down from $43.4 million as the company accelerates sales hiring ahead of 2027.
Bears have legitimate ammunition on the balance sheet. Operating cash flow was negative $15.4 million versus positive $18.7 million a year earlier. Management attributed this to collection timing and pointed to record October collections. Cash and investments fell to roughly $89 million from $187 million at year-end. Year-to-date, the company has spent $83 million on buybacks and refinanced its debt down to about $200 million. The stockholders' deficit widened to $97.9 million. A pending Pega retrial adds another unresolved variable.
The market had already priced in a great deal of optimism. Shares closed at $49.82 ahead of the report, up 64.9% from the $30.21 open after the August release. That leaves them roughly 70% above the 200-day moving average and less than 8% below the 52-week high of $54.12 set on October 23. Investor sentiment improved meaningfully, from -0.62 to -0.40, but remains negative. Skepticism has eased without disappearing, despite the stock's surge. Earnings Whispers trend signals are mostly positive, with momentum neutral.
The bottom line is that Appian produced a genuinely strong quarter, anchored by record net retention, accelerating cloud growth, and a third straight guidance raise. Turnaround skeptics were not positioned for results this strong. Yet the headline acceleration leaned on lumpy on-premises recognition, cash went the wrong way, and fourth-quarter total growth and EBITDA both step down. With the stock up nearly two-thirds in a quarter, investors must decide whether the cloud and retention story justifies a premium that leaves little room for those blemishes to linger.
Read our earnings preview for Appian: https://www.earningswhispers.com/article/APPN/22042
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-15 | |
| Oct-15 | |
| Oct-06 | |
| Sep-30 | |
| Sep-30 | |
| Sep-22 | |
| Sep-18 |
