ACI Worldwide Misses On EPS As Renewal Timing Guts Q3, But An Accelerating ARR Engine And A Third EBITDA Raise Shift The Burden To Q4
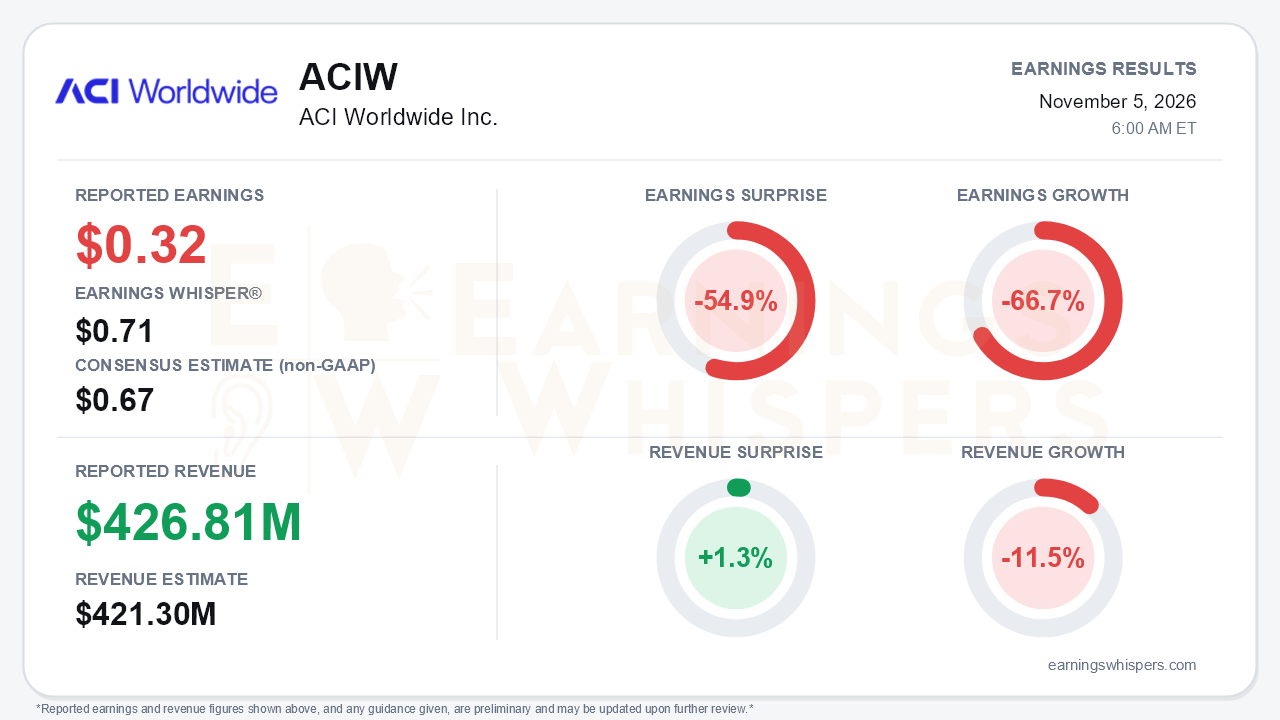
ACI Worldwide (NASDAQ: ACIW) reported third-quarter earnings of $0.32 per share on revenue of $426.81 million. That fell well short of the $0.67 consensus and the $0.71 Earnings Whisper number, a 54.9% miss, while revenue edged past the $421.3 million consensus by 1.3%. Earnings fell 66.7% year over year and revenue declined 11.5%, a sharp deceleration from a nine-month period in which revenue was flat. The headline needs context, however. The reported $0.32 is GAAP, while consensus was framed on a non-GAAP basis. ACI's adjusted diluted EPS was $0.54, down 50% from $1.09, which still left the company short of the Street. The central tension is that the quarter looked poor against analyst models yet beat management's own guidance. That guidance always assumed the year's license renewals would land in the fourth quarter.
The damage was concentrated in Payment Software. Segment revenue fell 24% to $216 million, and license revenue dropped from $162 million to $95 million. Because those renewals carry very high margins, their absence was felt immediately: segment adjusted EBITDA fell 41% and segment margin compressed from 64% to 49%. Total adjusted EBITDA fell 43% to $98 million, and net adjusted EBITDA margin slid from 49% to 35%. Costs added pressure as well. Research and development rose to $50 million from $43 million and G&A climbed to $42 million from $34 million, reflecting the investment push management described. Still, revenue landed at the top of the $417-427 million guide, and adjusted EBITDA cleared the $90-95 million range. Operating cash flow was a genuine bright spot, jumping 63% to $119 million in the quarter and 26% year to date to $254 million.
Beneath the timing noise, the forward indicators improved. Net new ARR bookings rose 86% to roughly $24 million, continuing a clean sequential climb from about $12 million in Q1 and $18 million in Q2. Biller revenue grew 6% with a stable 51% net margin, and management said the Biller sales team exceeded its full-year target before the quarter ended. The ACI Connetic platform moved from pipeline to production, with its first customer, Solaris, now live and generating initial SaaS revenue. Additional wins include two U.S. institutions and a large African bank slated for 2027, and the Cranium Ventures tuck-in adds card-switching capability. Management's tone has shifted from defending against AI disruption late last year to articulating a broader orchestration-and-intelligence vision, backed by a claim that more than 95% of full-year revenue is contracted or tied to scheduled renewals.
Bears still have legitimate ammunition. Payment Software recurring revenue slipped 1%, a notable cooling from 9% recurring growth in Q1. New license and services bookings fell 21% in the quarter and 22% on a trailing basis, and trailing ARR bookings were down 3% despite the strong Q3. The mix shift toward SaaS and consumption contracts structurally reduces upfront license revenue. Management also acknowledged that where results land within the guidance range depends on how customers choose to contract. Revenue guidance of $1.895-1.925 billion was only reaffirmed after raises earlier in the year. Meanwhile, adjusted EBITDA guidance rose for a third straight quarter to $550-565 million. The arithmetic is demanding: Q4 is guided to $257-272 million of adjusted EBITDA, roughly matching the $294 million generated in the first nine months combined.
The market had already moved toward the constructive interpretation. Shares closed at $59.19 heading into the report, up 11.9% from the open after the August release. That left the stock 24.8% above its 200-day moving average and just 1.3% below its inter-earnings high of $59.98, set the day before earnings. The stock has rallied roughly 24% from its September 30 low. Investor sentiment swung meaningfully, moving from a clearly negative -0.31 to a marginally positive +0.04, so expectations are no longer depressed. The Earnings Whispers trend signals are mostly positive, with price, momentum, and AVWAP trends constructive and sequential growth neutral.
That combination makes the setup more complicated than the miss implies. A stock sitting at its highs with sentiment recently repaired has less cushion if Q4 renewals slip or customers lean toward consumption pricing. The repurchase program, at $157 million year to date and 50-60% of operating cash flow, offers some support at the margin.
The bottom line is that ACI's Q3 miss was largely a scheduled consequence of renewal timing rather than a demand failure. Accelerating ARR bookings, Connetic's first go-live, Biller strength, robust cash flow, and another EBITDA raise preserved a credible growth story. But with nine-month revenue flat, license bookings shrinking, and an unusually heavy fourth quarter required to hit guidance, the investment case now rests on execution over the next three months. Shares are priced closer to success than to doubt.
Read our earnings preview for ACI Worldwide Inc.: https://www.earningswhispers.com/article/ACIW/22032
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 8 hours | |
| 9 hours | |
| 9 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-22 | |
| Sep-30 | |
| Sep-28 | |
| Sep-28 | |
| Sep-24 | |
| Sep-23 |
