Warby Parker Clears A Low EPS Bar, But Its Guidance Now Depends On Intelligent Eyewear As Core Customer Growth Slows
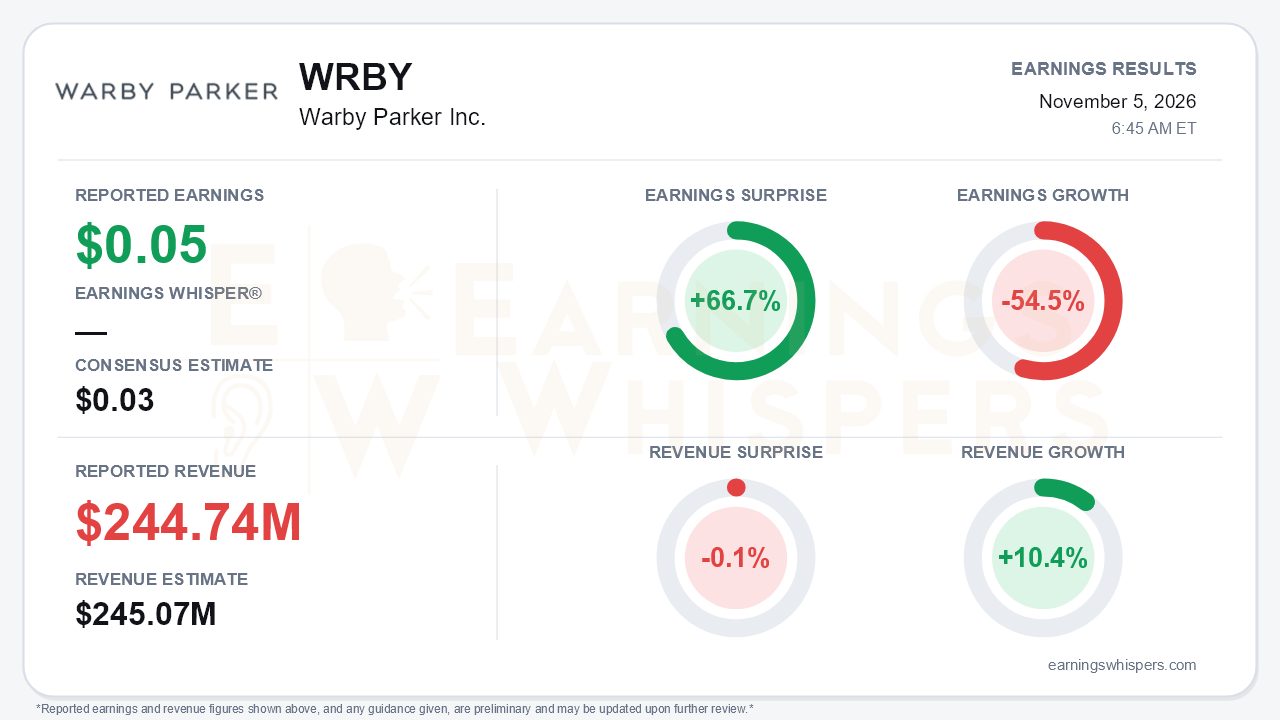
Warby Parker cleared a low bar in the third quarter, but the more important development was how its outlook changed. The company reported earnings of $0.05 per share, beating the $0.03 consensus by 66.7%, on revenue of $244.74 million that grew 10.4% year over year but missed the $245.07 million consensus by 0.1%. Earnings fell 54.5% from a year ago. On a GAAP basis, diluted EPS was $0.04 and net income slipped to $5.6 million from $5.9 million, so the beat reflects a modest estimate rather than earnings growth. The central tension is that management is making its most ambitious growth case yet just as the core customer engine is losing momentum.
The quality of the quarter was respectable but not inspiring. Adjusted EBITDA of $28.6 million came in above guidance, and margin edged up 10 basis points to 11.7%. Adjusted gross margin rose 40 basis points to 54.6%, a clear reversal from the 220-basis-point decline in the first quarter. The company cited lower tariffs, shipping savings, optical lab efficiencies and a richer mix of progressive lenses. SG&A gave much of that back. Adjusted SG&A deleveraged 70 basis points on retail compensation and technology costs, and GAAP operating income was flat at roughly $3.6 million. The underlying margin picture also looks flatter than the second quarter suggested, since that quarter's 14% EBITDA margin was flattered by an $11.8 million tariff refund. Free cash flow was negative $2.0 million as capital spending tied to Intelligent Eyewear rose. Year-to-date free cash flow of $13.2 million compares with $35.6 million a year ago.
Beneath the headline, the operating trends diverged sharply. On the positive side:
- E-commerce growth accelerated to 4.8%, up from flat in the second quarter and a 4.1% decline in the first quarter, as the Home Try-On headwind faded.
- Retail grew 12.4%.
- Eye exams grew about 30%.
- Insurance revenue rose 22%, with in-network penetration at 8.4% versus 7.4% a year ago.
- Average revenue per customer increased 6.7%.
Customer acquisition tells a different story. Trailing-12-month active customer growth slowed to 3.0%, from 4.1% in the second quarter, 4.8% in the first quarter and 7% for fiscal 2025. Management described traffic as softer than it would like, noted that industry units are down and that cash-pay consumers are under pressure, and flagged softness in late September. That echoes the late-June weakness cited on the prior call. Management again promised a fourth-quarter inflection in active customers before any Intelligent Eyewear contribution. Investors have now heard that promise while the metric decelerated for several straight quarters.
The guidance deserves scrutiny. Warby Parker narrowed full-year revenue guidance to $966 million to $976 million, or 11% to 12% growth, by raising the low end from $959 million. Fourth-quarter revenue is guided to $243 million to $253 million, up 15% to 20%. However, the new range now includes up to a point of growth from Intelligent Eyewear, which prior guidance excluded. That implies the core outlook was trimmed to roughly $962 million from a $967.5 million midpoint. Adjusted EBITDA guidance of $117 million to $119 million was held despite the third-quarter beat, implying a fourth-quarter margin near 11%. That reflects launch, staffing and marketing costs. Management also said Intelligent Eyewear carries a lower gross margin percentage, with the focus shifting to gross profit dollars.
The catalyst calendar is real and near-term. Pre-orders for the Google and Samsung-partnered Intelligent Eyewear open November 12, with deliveries starting in mid-December. Demos begin in 65 stores before rolling out to the full fleet. The launch comes alongside the company's largest-ever marketing campaign, partly funded by more than $50 million remaining from Google's $75 million reimbursement. Other new initiatives include:
- a Rare Beauty collaboration;
- the Warby Parker Care protection program;
- a second Sport collection;
- a $5.6 million lens-technology investment.
Management's tone was noticeably more expansive, calling Intelligent Eyewear a "step function change" and expecting "rapid acceleration" in 2027. The risk is execution timing. Revenue is recognized only on delivery, which leaves a narrow holiday window for an unproven product to carry the fourth-quarter guidance.
The market was not positioned for optimism heading into the print. Shares closed at $21.29, down 15.1% since the open after the August report and 15.1% below the 200-day moving average of $25.09. The stock set its inter-earnings low of $21.19 the day before earnings, about 25.8% below the August 19 high of $28.70. Investor sentiment, already slightly negative, became modestly more negative, slipping from -0.017 to -0.069. The Earnings Whispers trend signals lean negative, with price and AVWAP trends both pointing down.
The bottom line is that Warby Parker delivered a clean EBITDA beat and improving gross margin and e-commerce trends, but the core outlook softened while customer growth decelerated again. The investment setup has shifted from steady store-led compounding toward a story that depends on an Intelligent Eyewear ramp and a promised customer inflection. Bulls get a credible catalyst within weeks. Bears have legitimate ammunition in the trimmed core guide and flat full-year EBITDA.
Read our earnings preview for Warby Parker Inc.: https://www.earningswhispers.com/article/WRBY/22215
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-15 | |
| Sep-29 | |
| Sep-25 | |
| Sep-08 | |
| Aug-12 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 |
