Enovis Beats And Raises Profit Guidance, But Slowing U.S. Hips And Knees And A Trimmed Revenue Ceiling Limit The Upside
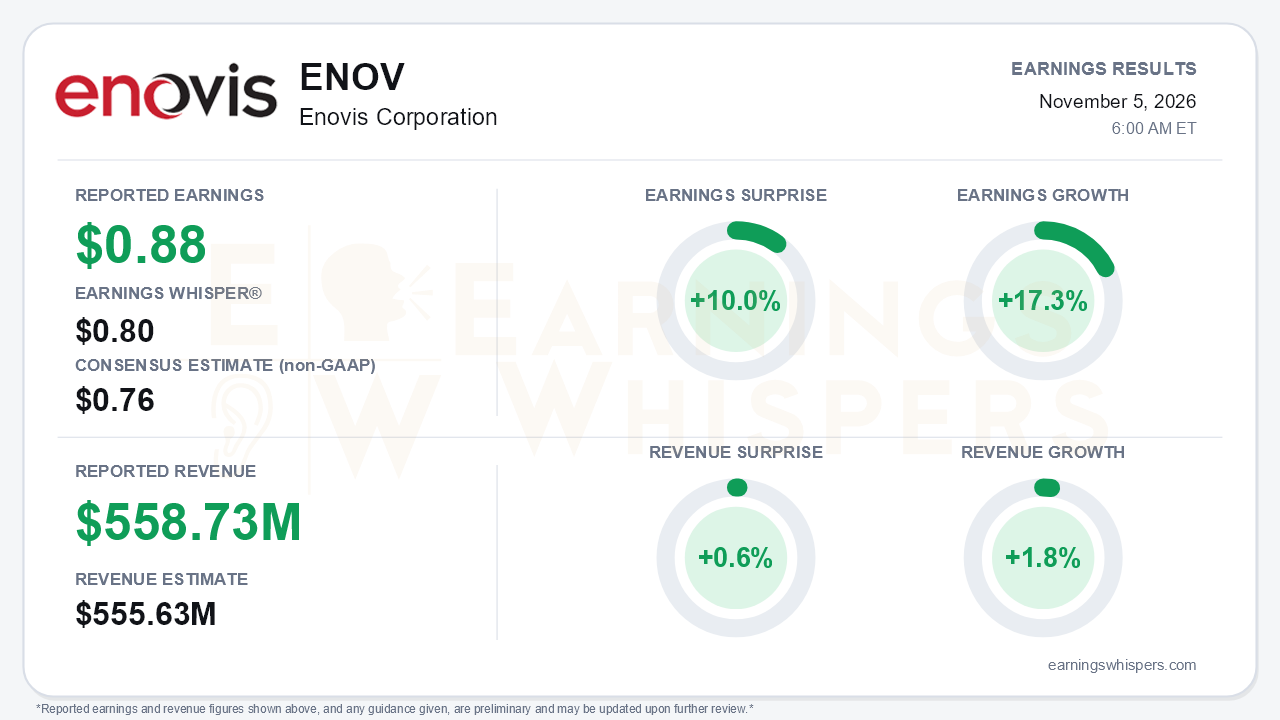
Enovis delivered a clean profit beat in the third quarter. Adjusted earnings of $0.88 per share topped the $0.76 consensus and the $0.80 Earnings Whisper number by 10.0%, and grew 17.3% from a year ago. Revenue of $558.73 million edged past the $555.63 million consensus by 0.6%, but reported sales rose only 1.8%. That gap between double-digit earnings growth and low-single-digit sales growth is the central story. Enovis is extracting more profit from a top line that is merely steady, and the most important growth engine, U.S. reconstructive, is losing speed.
The headline revenue figure understates the underlying business. The October 2025 divestiture of Dr. Comfort removed $13.8 million of year-ago sales. Organic growth was 4.6%, slightly above the 4.2% year-to-date pace. Reconstructive grew 6% reported and 6.3% organically, while Prevention & Recovery fell 1.9% reported but grew 3.0% organically. Adjusted EBITDA rose to $103.5 million, and margin expanded 120 basis points to 18.5%. On a GAAP basis, Enovis earned $0.02 per share from continuing operations, compared with a $9.99 loss a year earlier. That swing is largely explained by last year's $548 million goodwill impairment, not by a transformation in GAAP profitability. The quality of the margin story also deserves scrutiny. Adjusted gross margin of 60.9% looks up from 60.3%, but the call revealed it included roughly $8 million of tariff refunds. Excluding the refunds, gross margin was down about 80 basis points on mix and Middle East-related inflation. The EBITDA improvement owes more to operating discipline and one-time help than to a richer product mix.
The call laid out the deceleration plainly. U.S. reconstructive organic growth slowed from 8% in the first quarter to 6% in the second and 5% in the third. U.S. hips and knees fell from 6% to 3%, and management described a choppy market marked by cancellations and patient co-pay sensitivity. U.S. foot and ankle was softer than expected, and France and Germany remain pressured. The Middle East conflict cost about 100 basis points of international growth and added roughly $3 million of raw material and freight inflation. There were offsets:
- International reconstructive accelerated to 8% from 3% in the first quarter.
- U.S. shoulder returned to high-single-digit growth.
- The Nebula stem is now the top seller, with more than 80% of new sets going to competitive users.
- Regenerative products in P&R grew at a double-digit rate.
Guidance reflects the same split. Adjusted EBITDA guidance rose to $428-438 million and adjusted EPS guidance to $3.58-3.79, but the $0.06 raise is only about half the quarter's beat. Management attributed the gap to $4 million of incremental fourth-quarter robotics R&D and $1 million of currency. Revenue guidance was narrowed to $2.32-2.35 billion, with the $2.37 billion top end removed and organic growth pinned at about 5%. The profit outlook improved, while the revenue ceiling came down.
The forward catalysts center on capital deployment and robotics. Leverage of 2.9x, down from 3.1x at year-end, underpins a new $200 million buyback, double the prior authorization. The pending eCential Robotics acquisition (rendered "Essential" in the call notes) fills a robotics gap, with a knee robot targeted within about two years and close expected by year-end. Management reiterated its 2027 framework of at least 50% free cash flow conversion and about $100 million of cash generation. Third-quarter free cash flow of $35 million was a step forward. Bears still have legitimate ammunition:
- Leverage will rise about half a turn when the deal closes, putting buybacks in competition with deleveraging.
- Quarter-end cash was just $13 million.
- Full-year free cash flow conversion is guided only to 25% or higher.
- Competitors are launching new shoulder systems and robotic applications.
Investor sentiment heading into the report had weakened, falling from -0.27 to -0.40 and moving further into negative territory. Price action explains why. Shares opened at $28.86 after the August report, which marked the inter-earnings high, and then slid to a 52-week low of $16.70 on October 8. The stock has since rebounded about 46% to $24.42, 6% above its 200-day moving average but still 15.4% below the post-August open. Price and AVWAP trend readings remain negative. In short, the stock entered the print after a sharp recovery rally, with the crowd still skeptical.
The bottom line is that Enovis produced a credible beat-and-raise on profitability, backed by better cash generation and a larger buyback. The quarter does not resolve the question that matters most for the stock: whether U.S. reconstructive growth can stabilize. The margin gains leaned partly on tariff refunds, and the revenue range lost its upside. The robotics deal is a long-dated story with near-term leverage costs. Until U.S. hips and knees reaccelerate, earnings upside may continue to run ahead of the underlying growth trend.
Read our earnings preview for Enovis Corporation: https://www.earningswhispers.com/article/ENOV/22088
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-08 | |
| Sep-22 | |
| Sep-02 | |
| Sep-01 | |
| Sep-01 | |
| Aug-31 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-28 | |
| Jul-17 |
