Chimera's Modest Year-Over-Year EAD Gain Masks A Broken Quarter: Book Value Falls 16.5%, HomeXpress Margins Turn Negative And The $1.80 Target Goes Unrepeated
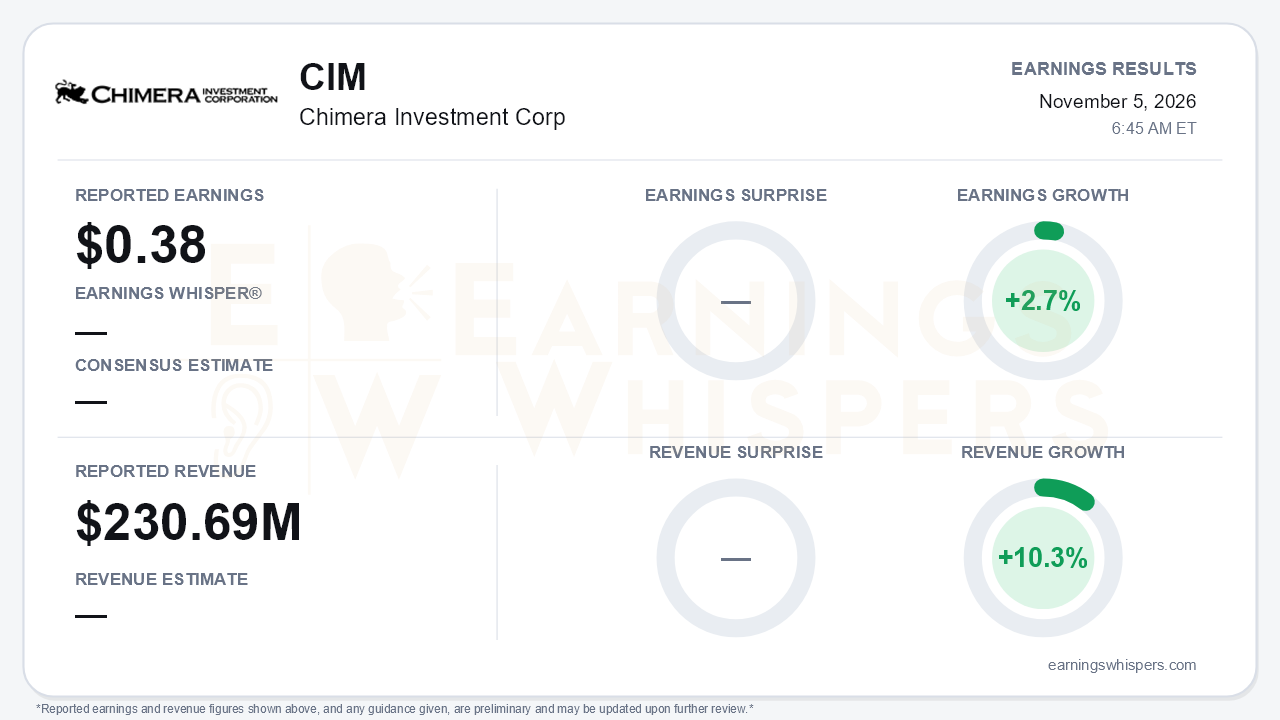
Chimera Investment Corp (NYSE: CIM) reported earnings available for distribution (EAD) of $0.38 per share on revenue of $230.69 million for the September quarter. EAD grew 2.7% year over year and revenue grew 10.3%. No consensus estimate was available for comparison. The year-over-year framing is the most flattering way to read this report, and it is misleading. EAD has now fallen for two straight quarters, from $0.54 in Q1 to $0.46 in Q2 to $0.38. The comparison quarter was itself a weak $0.37. Beneath the non-GAAP line, a September rate and spread shock produced a GAAP loss of $193.7 million, or $2.31 per share. Book value per share dropped to $14.82 from $17.75 and the economic return was -13.98%. That is the central tension: a REIT that spent the first half of 2026 describing itself as on track just absorbed its worst quarter in years, and management guided for more pressure.
The GAAP damage came almost entirely from marks. The company recorded $391 million of net unrealized losses on fair-value instruments and $26.9 million of realized losses on sales. Hedges offset only part of that, with $207.8 million of derivative gains. Tangible common equity fell to $1.05 billion from $1.29 billion in a single quarter. The core spread business, by contrast, held up. Investment Portfolio economic net interest income rose to $69.4 million from $66.3 million, and the net interest margin was steady at 1.9%. Management also repositioned the Agency book into higher coupons, lifting the average coupon to 5.67% from 5.28% and shortening duration by roughly nine months. The EAD decline was driven by the origination side rather than the portfolio. Management put EAD excluding one-off items at $0.47, though investors should weigh that adjusted figure accordingly.
HomeXpress is where the quarter broke. Volume kept climbing to a record $1.12 billion, up 27% year over year and above $1.10 billion in Q2. Correspondent share rose to 16.8% from 13%, and credit quality held, with a 743 FICO and 72.4% LTV. Profitability did not hold:
- Net origination margin swung from 124 basis points in Q2 to -7 basis points, after July had run at 74 basis points.
- Segment EBTDA collapsed to $439 thousand from $11.8 million.
- The segment posted a $2.4 million GAAP loss.
Management blamed losses on locked pipeline loans and competitors that were slower to raise rates. The pace now sits far below the $62-80 million pre-tax contribution projected for 2026 when the acquisition was framed. Growing volume while margins vanish shows the business is exposed to rate volatility and pricing competition, not just scale.
The call offered real catalysts:
- **Prism securitization:** the inaugural $291 million Prism deal priced its AAA tranche at 160 basis points, in line with seasoned issuers, and management intends to make Prism a regular issuer.
- **Financing:** two maturing non-mark-to-market repo facilities were refinanced at lower cost, extended two years and upsized to about $355 million.
- **Recovery so far:** book value is up roughly 5% quarter-to-date, and Agency levered returns are now pegged at 16-17%.
- **Outlook and costs:** the HomeXpress pipeline is described as profitable again at note rates near 8%, and a cost-efficiency review is under way.
The risks are more immediate, however:
- **Q4 guidance:** HomeXpress is guided to roughly breakeven while it works off the Q3 pipeline, with possible further losses on loans held ahead of securitization. Profitability is not expected to return until Q1 2027.
- **EAD target:** the 'at least $1.80' full-year EAD target reiterated in Q2 was not repeated. With nine-month EAD at $1.38 and a weak Q4 expected, that silence reads as an implied miss.
- **Dividend coverage:** cumulative EAD of $1.38 now exceeds the $1.35 in dividends declared by only a few cents.
- **Leverage and liquidity:** recourse leverage rose to 4.1x from 3.3x in Q2 (and 2.4x at year-end 2025), and cash plus unencumbered assets fell to $561 million from $656 million as loans were warehoused for Prism.
- **Execution and credit:** only one of the three securitizations targeted by year-end has closed, and investor DSCR delinquencies ticked up in September before largely reversing.
Management's tone shifted accordingly, from 'play offense' in Q1 and 'on track' in Q2 to language about liquidity preservation and 'what we can control.'
Market context is thin. Current price and sentiment readings were not available. Shares opened at $12.15 after the August report, essentially at the 200-day moving average of $12.24. At that point they traded at a steep discount to the $17.75 book value. Much of that discount has now been closed by the decline in book value rather than by any rally in the shares. Investors who treated the discount to book as a margin of safety have watched the gap close the wrong way.
The bottom line is that the 2.7% year-over-year EAD gain says little about this quarter. The spread portfolio is earning more, and Prism's debut validates the integrated origination-to-securitization strategy. But HomeXpress margins went negative, book value fell 16.5%, and leverage rose while liquidity fell. Management also stopped defending its full-year earnings target and pushed origination profitability into 2027. The quarter-to-date book value recovery helps, but bears have legitimate ammunition until HomeXpress margins and EAD stabilize.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 8 hours | |
| 10 hours | |
| 10 hours | |
| Oct-30 | |
| Oct-22 | |
| Sep-17 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-23 | |
| May-07 | |
| May-07 | |
| May-07 |
