BlackSky's Record Gen-3 Quarter Delivers Margin Breakout And Higher Guidance, But Backlog, Satellite Timing And A Soft Q4 Setup Keep The Market Skeptical
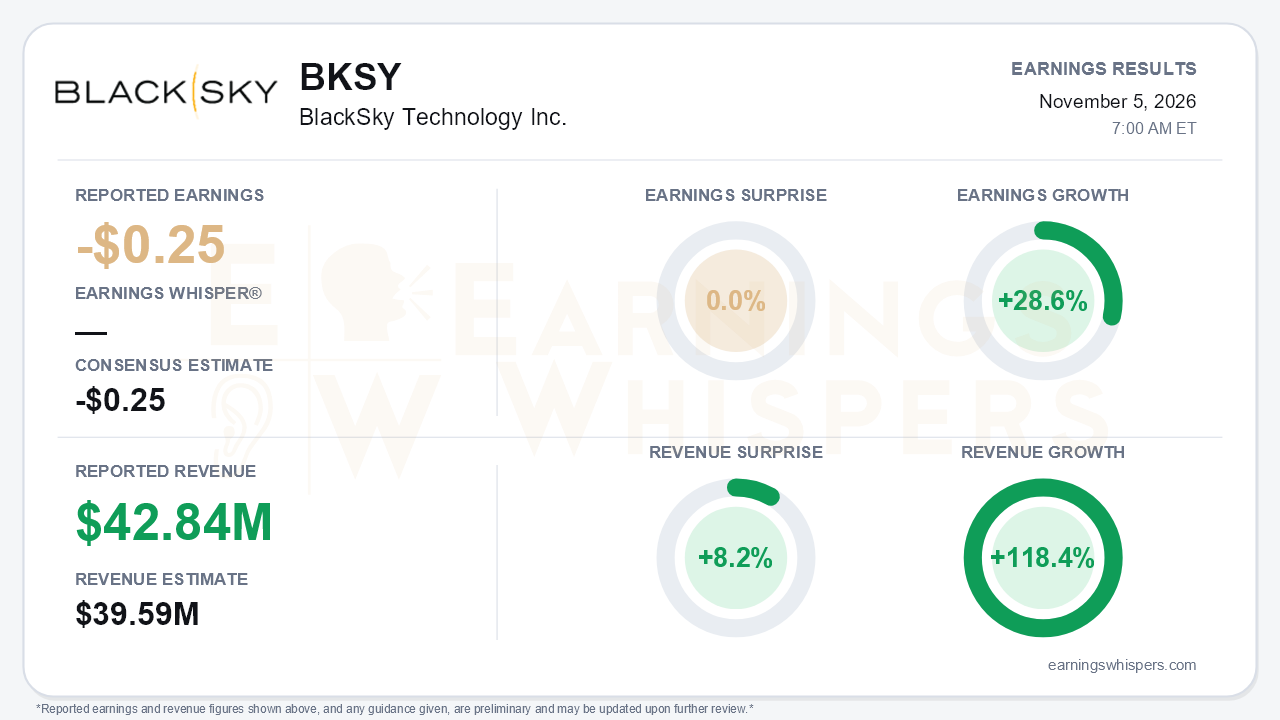
BlackSky Technology delivered its strongest operating quarter to date, though the earnings line is less clean than the revenue line. Revenue of $42.84 million rose 118.4% year over year and beat consensus by 8.2%. Earnings Whispers' normalized loss of $0.25 per share matched the consensus estimate exactly, while earnings improved 28.6% from a year ago. On a GAAP basis, the company swung to net income of $18.5 million, or $0.10 per diluted share, from a $15.3 million loss. That profit leaned heavily on a $19.7 million non-cash gain on derivatives tied to warrants and other fair-value equity instruments. GAAP operating income was just $405,000. The real story is not the bottom line. It is operating leverage finally showing up at scale as Gen-3 imagery fills the constellation.
The quality of that leverage is impressive. Space-based intelligence and AI services revenue reached a record $32.7 million, up 107% year over year and roughly 34% from $24.5 million in Q2. Cost of sales fell to 21% of revenue from 35% a year earlier. Cash operating expenses rose only $3.3 million to $21.4 million. Adjusted EBITDA hit a record $12.8 million at a 30% margin, more than double Q2's 14.2% and a sharp reversal from Q1's negative $5.1 million. Management said incremental subscription revenue carries a 90-95% contribution margin, which explains how the margin profile changed so quickly. Operating cash flow also turned positive for the first time, without relying on customer prepayments. That matters for a company that has funded its build-out through dilution, including $160 million of net equity proceeds this year.
The guidance story depends on which end of the range you focus on. Management described the outlook as a second raise of the year. Full-year revenue guidance moved to $140-150 million from $130-150 million, and adjusted EBITDA guidance moved to $18-24 million from $12-24 million. Those increases came entirely at the low end, so the ranges narrowed rather than shifted upward. The implied fourth quarter is where the debate begins. Implied revenue of roughly $43-53 million spans flat to solidly higher. Management, however, signaled that adjusted EBITDA would be flat to down sequentially, for two reasons:
- **Mix:** a shift toward lower-margin Mission Solutions satellite deliveries, including the first sovereign Gen-3 satellites.
- **Pilot lumpiness:** Q3 was flattered by a seven-figure, two-month U.S. government Gen-3 pilot, so part of the 30% margin is not a run rate.
The forward catalysts are substantial but still early. BlackSky was named exclusive provider of very-high-resolution optical satellites for a $1 billion, 50-satellite constellation backed by a consortium that includes France and the UAE. So far, though, only a small initial development contract has been received, and definitive agreements, value and timing remain undisclosed. Other developments add breadth:
- an international defense customer graduating from a Gen-2 pilot to a seven-figure Gen-3 subscription;
- a seven-figure HEO renewal in space domain awareness;
- a SkyFi pilot reaching Robinhood users.
Management described the pipeline as multi-billion dollars. Bears still have legitimate ammunition. Backlog of $355 million is roughly flat against the ~$380 million cited after Q1. The Gen-3 constellation target slipped, with seven satellites now expected by year-end and the eighth in early 2027, versus eight previously. Cash and investments declined to $231 million from $244 million in Q2, as $50-60 million of annual capex continues. There will be no 2027 guidance until Q1, though the December 2 Investor Day offers an interim window.
The market setup is far more bearish than the fundamentals. Shares entered the report at $16.77, down 34.5% from the open after the August release. They have fully reversed a post-report spike to $32.39 in mid-August and sit 38.2% below the 200-day moving average. The stock is only 4% above its late-October inter-earnings low. Investor sentiment, already negative, slipped modestly from -0.31 to -0.34. That points to slightly deeper skepticism heading into the print, not capitulation. Earnings Whispers trend signals are mixed: momentum has turned positive, while price and AVWAP trends remain negative.
The bottom line is that BlackSky delivered the quarter Gen-3 bulls have been promising: record revenue, a 30% EBITDA margin, first positive operating cash flow and higher guidance floors. The in-line normalized EPS and a derivative-inflated GAAP profit understate how much the operating model improved. The tempered Q4 margin outlook, flat backlog, satellite slippage and an undefined $1 billion award explain why a stock that has lost a third of its value is not being given the benefit of the doubt. Converting the consortium deal and pipeline into backlog is now the key test.
Read our earnings preview for BlackSky Technology Inc.: https://www.earningswhispers.com/article/BKSY/22054
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Nov-03 | |
| Oct-28 | |
| Oct-22 | |
| Oct-19 | |
| Oct-15 | |
| Oct-14 | |
| Oct-12 | |
| Oct-05 | |
| Sep-30 | |
| Sep-30 | |
| Sep-25 | |
| Sep-14 |
