Malibu Boats Misses As Saxdor Masks A Weakening Core And The Outlook Moves Lower
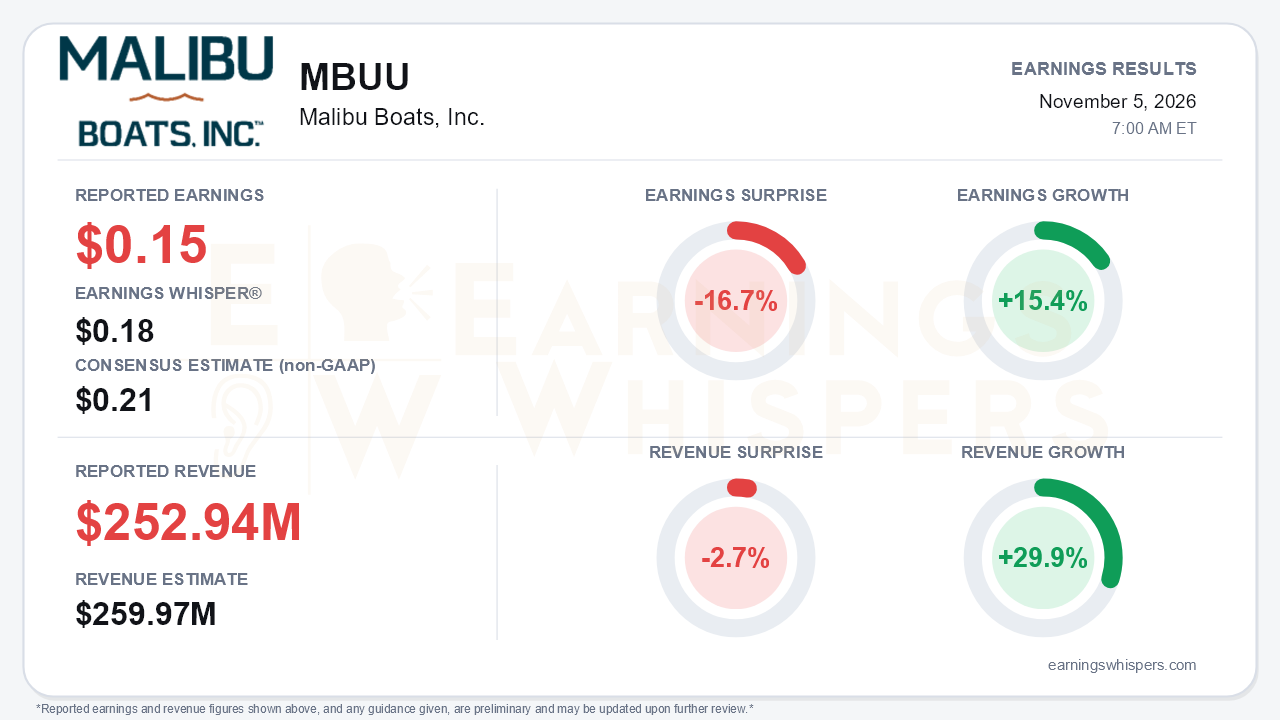
Malibu Boats (NASDAQ: MBUU) reported adjusted earnings of $0.15 per share for the quarter ended September 2026. That was 16.7% below the $0.21 consensus and short of the $0.18 Earnings Whisper number. Revenue rose 29.9% to $252.94 million but missed the $259.97 million consensus by 2.7%. It also fell below the company's own $255-265 million guidance range. Earnings Whispers shows 15.4% year-over-year earnings growth, while the company's own adjusted per-share figure was flat at $0.15 on a slightly higher share count. The headline growth looks healthy, but it was largely bought rather than built. The Saxdor acquisition contributed $51.1 million of sales, and the legacy business is slowing as the boating cycle worsens. That is the central tension of the quarter.
The quality of the reported numbers deserves scrutiny. GAAP results swung from a loss of $0.04 per share to a profit of $0.30. That swing rests heavily on a $15.0 million reduction in G&A from derecognizing a liability tied to Starr insurance proceeds, a benefit the company excludes from its adjusted figures. Strip out Saxdor and the picture is weaker. Legacy sales grew just 3.6%, down from 13.2% in the June quarter. Legacy adjusted EBITDA fell to $10.3 million from $11.8 million. Consolidated adjusted EBITDA rose 21.7% to $14.3 million, landing at the low end of the $14-16 million guide, and the margin slipped to 5.7% from 6.1%. Gross margin improved 70 basis points to 15.0%, but the company attributed that primarily to Saxdor rather than legacy improvement.
The damage is concentrated in ski/wake, Malibu's signature category. Malibu segment sales fell 9.1% on lower shipments. Net sales per unit dropped 3.2% as dealer incentives rose. Incentives also pushed Saltwater Fishing per-unit revenue lower even as its volume grew. Cobalt was the clear standout, with sales up 18.8% on volume, mix, and pricing. However, both Cobalt and Saltwater were lapping depressed shipments from a year ago, when dealer inventories were elevated. The broader demand backdrop deteriorated sharply. Industry registrations fell about 11% for July through September, compared with roughly 3% for April through June. Management now assumes a mid-to-high single-digit retail decline for the transition period, versus a "flat to down" view in August. Dealer destocking is expected to continue rather than wholesale shipments matching retail. The tone shifted from August's "strong finish" framing to describing a market "not giving us much help," with rising rates and heavy promotions cited as headwinds.
The guidance reset compounds the miss. A change to a December fiscal year-end superseded the prior $1.08-1.12 billion sales and $101-109 million adjusted EBITDA outlook. In its place, management guided December-quarter sales of $236-248 million and adjusted EBITDA of $13-15 million. Calendar 2027 guidance will not arrive until March, so investors lose a full-year anchor at precisely the moment the cycle is softening. Cash flow adds to the pressure. Free cash flow was negative $39.5 million as inventory was rebuilt by about $32 million, net leverage rose to roughly 1.5x from 1.0x, and no shares were repurchased despite the $70 million authorization. Management expects working capital to unwind seasonally, but bears have legitimate ammunition here.
The call did preserve a credible growth story around Saxdor. Fort Pierce U.S. production began in July, ahead of schedule. Serial production of the 320 GTO is underway, with room for about 200 builds a year without expansion. New MarineMax distribution broadens the brand's reach. Saxdor ran an 8% adjusted EBITDA margin, and management still targets 10-11%, while reaffirming mid-teens growth expectations through the first half of calendar 2027. There are early-stabilization signals as well. September registrations were down only 2%, Malibu's towboat brands grew that month, dealer inventory is down low double digits with little aged stock, and retail sales and ASPs at the Fort Lauderdale show beat last year.
Investors were already leaning cautious. Earnings Whispers sentiment fell from roughly neutral at -0.03 to a clearly negative -0.24 ahead of the report. Shares closed at $24.75 on November 4, down 14.4% from the $28.93 open after the August report and about 7.9% below the 200-day moving average of $26.89. Trend readings are mixed: price and AVWAP trends are negative, while momentum is positive. The setup suggests some disappointment was anticipated, though a lower outlook and a delayed full-year guide give skeptics fresh reasons to stay on the sidelines.
The bottom line is that Malibu's 29.9% revenue growth and GAAP profit swing overstate the health of the business. Underneath the acquisition contribution and a one-time insurance benefit, the core is shrinking at the margin and guidance has moved lower. Leverage and cash burn have also risen. Saxdor and Fort Pierce offer a genuine long-term catalyst, but until retail demand in ski/wake stabilizes, that story is offsetting weakness rather than driving growth.
Read our earnings preview for Malibu Boats, Inc.: https://www.earningswhispers.com/article/MBUU/22140
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| 12 hours | |
| 13 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-22 | |
| Aug-31 | |
| Aug-27 | |
| Aug-27 | |
| Aug-27 | |
| Aug-14 | |
| Jul-17 | |
| Jul-13 | |
| Jun-23 |
