Molson Coors Clears A Low Bar But Cuts All Four Guidance Metrics As Cost Inflation Outruns Horizon 2030 Progress
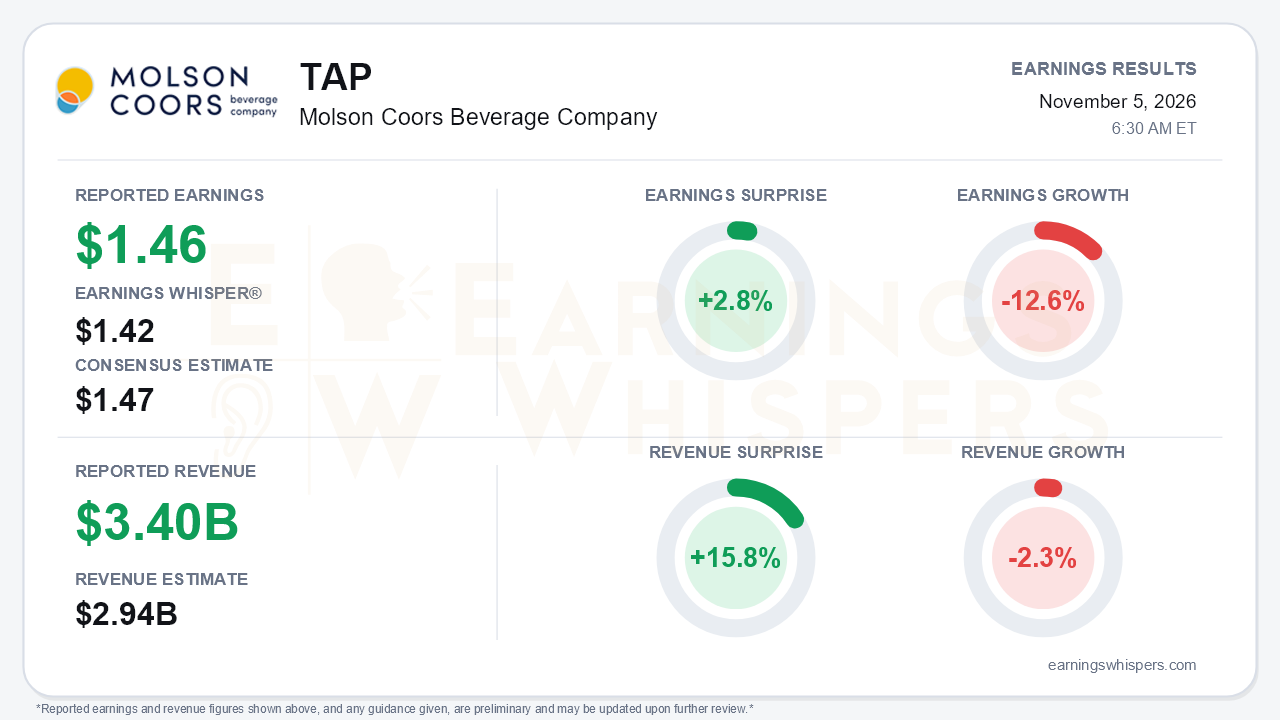
Molson Coors delivered a quarter that looks better against expectations than against its own plan. Underlying EPS of $1.46 topped the $1.42 Earnings Whisper number by 2.8%, though it came in a penny below the $1.47 consensus and fell 12.6% from a year ago. The more consequential news was the outlook: after reaffirming guidance in each of the first two quarters, management cut all four key full-year metrics. Net sales are now expected to decline 1% to 2% in constant currency, versus flat plus or minus 1% previously. Underlying pre-tax income is now seen down 21% to 24%, versus 15% to 18%. Underlying EPS is projected down 16% to 19%, versus 11% to 15%, and free cash flow guidance was trimmed to $1.0 billion from $1.1 billion. That is the central tension. The quarter was less bad than the second quarter, but the year is now worse than the company told investors it would be.
The revenue headline deserves scrutiny. The reported $3.405 billion, down 2.3%, is gross sales including excise taxes, and it produced a 15.8% surprise against a $2.94 billion consensus. Net sales, the line the company guides to, were $2.93 billion, down 1.6% reported and 1.2% in constant currency. On a comparable basis, that is roughly in line rather than a blowout. The mechanics were familiar. Financial volume fell 3.0% and brand volume dropped 4.9%, with U.S. brand volume down 5.6%. Pricing and mix added 1.8%. The real damage was below the top line. Underlying COGS per hectoliter jumped 8.1% on materials, logistics and manufacturing inflation, including roughly $30 million from the Midwest aluminum premium. As a result, gross profit fell to $1.03 billion from $1.17 billion. A 7.4% cut in underlying MG&A, driven by lower marketing and restructuring savings, cushioned the blow. Even so, underlying pre-tax income still fell 17.4%. GAAP EPS of $1.45 compares with a $14.79 loss last year, but that swing simply reflects cycling a $3.6 billion goodwill impairment and is not an operating signal.
Sequentially, the trajectory improved. Net sales declined 1.2% versus 3.6% in the second quarter. Underlying pre-tax income fell 17.4% versus 27.8%, and EPS fell 12.6% versus 22.9%. U.S. share trends improved about 20 basis points from the second quarter, with three of four regions better. Coors Light led that improvement, and Coors Banquet posted its 21st straight quarter of share growth. Monaco had its best net-sales quarter on record and is tracking ahead of acquisition expectations, which helped lift Americas net sales per hectoliter 2%. EMEA&APAC underlying pre-tax income rose 5.5% in constant currency, though that gain came from cost cuts rather than demand. U.K. volumes remained under pressure from heavy promotions. Those self-help wins are real, but management conceded that they are "not yet scaled enough" to offset the headwinds.
Those headwinds are getting broader. The U.S. beer industry fell more than 4% in the quarter, and recent trends are softer than the year-to-date average. Management now expects freight, fuel and Midwest premium inflation to persist into 2027. That is a notable retreat from earlier talk of returning to the long-term algorithm. The source material is also inconsistent on the aluminum hit. The release cites a full-year Midwest premium impact roughly $130 million above the prior year, while the call reportedly referenced about $113 million. Either way, it is a meaningful drag. New risks include litigation over brand owners seeking to terminate agreements with Coors Distributing Company in Colorado, continued Blue Moon softness, and a wide fourth-quarter range that implies a weak exit rate. Leverage of 2.53x net debt to EBITDA, up from 2.28x a year ago, remains above the sub-2.5x target even as buybacks continue. Catalysts include the national launch of Coors Zero Zero, the largest Carling refresh in more than 30 years, and EMEA restructuring benefits extending into 2027.
Investors had already been leaning bearish. Earnings Whispers sentiment deteriorated meaningfully, from -0.10 to -0.28, ahead of the report. Price action tells a more resilient story. Shares fell to a 52-week low of $35.52 in late September, then rallied 21.5% into the report. The stock closed at $43.14, about 1.9% above its 200-day moving average and only 3.1% below its post-August high. It finished essentially flat, down 1.3%, since the prior report. The trend signals are mixed, with AVWAP positive but sequential growth still negative. Bears have legitimate ammunition in a guidance cut arriving after a sharp rebound.
The bottom line is that Molson Coors cleared a modest whisper bar and showed genuine share and cost progress, but the across-the-board guidance cut and management's admission that inflation will linger into 2027 undercut the improving sequential trend. With the stock having recovered most of its inter-earnings decline, the setup now depends on whether share gains and cost savings can scale faster than a shrinking category and stubborn input costs.
Read our earnings preview for Molson Coors Beverage Company: https://www.earningswhispers.com/article/TAP/22189
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 12 hours | |
| 15 hours | |
| 15 hours | |
| 16 hours | |
| 17 hours | |
| 18 hours | |
| 20 hours | |
| Nov-04 | |
| Oct-28 | |
| Oct-06 | |
| Oct-05 | |
| Sep-25 | |
| Sep-15 | |
| Sep-08 | |
| Sep-08 |
