Peloton's Big Q1 Beat Leans On One-Time Help As Unchanged Guidance Points Back To Revenue Declines
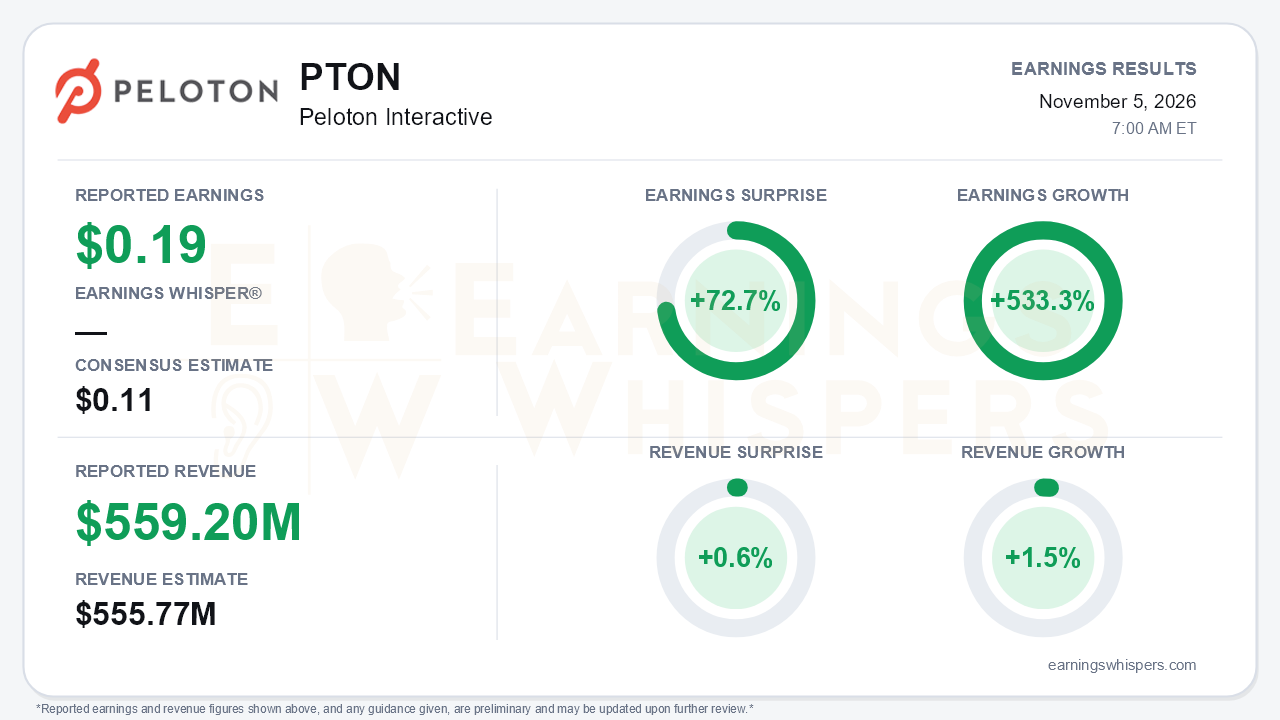
Peloton Interactive delivered a decisive headline beat for its fiscal first quarter, earning $0.19 per share against a $0.11 consensus, a 72.7% surprise, as earnings grew 533.3% year over year. Revenue of $559.2 million edged past the $555.77 million estimate by 0.6% and grew 1.5%, the third straight quarter of year-over-year growth. The central tension is that the earnings beat was far larger than the underlying improvement. A meaningful share of the upside came from items that will not repeat, and management left full-year guidance untouched, including a forecast for revenue to shrink again.
The quality of the beat deserves scrutiny. Total gross margin reached 61.3%, up 975 basis points year over year and well above the roughly 57% guide. The company acknowledged the result was partially driven by nonrecurring benefits. Connected Fitness Products gross margin jumped to 33.4% from 6.9% a year earlier, even as hardware revenue fell 3%. On the call, management tied about $25 million of the quarter to tariff and recall favorability that was already embedded in the full-year outlook. Excluding those items, adjusted EBITDA was roughly $143 million, only about $3 million above the guidance midpoint, rather than the reported $168 million that cleared the top of the range by $23 million. The bottom-line improvement is still real. GAAP net income rose to $96.2 million from $13.9 million, operating expenses fell 7%, stock-based compensation dropped to about $40 million, and free cash flow more than doubled to $143 million. Diluted share count, however, rose to 525 million from 430 million, which tempers the per-share story.
Beneath the margins, the operating trends are mixed. Subscription revenue grew 3%, helped by last October's price increase. The subscriber base kept shrinking, though:
- **Subscriptions:** paid Connected Fitness subscriptions fell 9% to 2.475 million, the top of the guided range.
- **Members:** fell 11% to 5.3 million.
- **Churn:** improved to 1.7% from 2.2% in the June quarter, and the year-over-year deterioration narrowed to roughly 11 basis points from 37. Management reiterated flat churn for the year.
- **Commercial:** revenue grew 13%, extending its low-to-mid-teens run.
- **Software:** Peloton IQ topped 1 million monthly active users.
The call was noticeably more confident than in prior quarters, as the product pipeline moved from teasers to shipped hardware. That includes the roughly $2,000 foldable Tread Flex, the computer-vision Tread lineup, and the Commercial Series, now in gym trials.
The forward guide is where the setup gets more complicated than the surprise implies. Second-quarter revenue is guided to $625 million to $650 million, down 3% at the midpoint, as the price-increase tailwind laps. Gross margin is expected near 50%, and subscriptions are projected at 2.425 million to 2.445 million. Full-year targets were only reaffirmed:
- Revenue of $2.30 billion to $2.40 billion, down about 4%
- Gross margin of roughly 54%
- Adjusted EBITDA of $475 million to $525 million
- Free cash flow of at least $350 million
In other words, the three-quarter streak of revenue growth is expected to end. Management also flagged rising year-over-year churn in the third quarter. The holiday quarter is heavily back-weighted, and management characterized the outlook as the "first inning." Commercial deals carry long trial-to-rollout cycles, and a new hardware category is not due until fall 2027.
The balance sheet is the clearest structural win. Cash of $1.34 billion exceeded total debt at quarter-end, and a $280 million voluntary term-loan paydown in October brought gross principal debt down 32% since the start of calendar 2026, to $1.048 billion. Bears still have legitimate ammunition here. The refinancing management had previously framed as the gating item for capital returns has been deferred because of credit-market volatility, with no timeline, so no buyback has been announced.
Investor sentiment entering the report remained negative but improved meaningfully, rising to -0.07 from -0.20 after the prior report. The stock has not followed. Shares closed at $5.46 the day before the release, down 7.5% from the $5.90 open after the August report. That leaves them about 9% below the $6.00 inter-earnings high set on that same day. The stock rebounded 16.4% off its late-September low of $4.69 and sits about 4.8% above its 200-day moving average. The Earnings Whispers trend signals remain mostly negative on price, sequential growth and AVWAP, consistent with a stock still working through a soft top line.
The bottom line is that Peloton's quarter showcased a leaner, cash-generative company with a net-cash balance sheet and a refreshed product lineup. The size of the beat overstates the change in trajectory, however. Strip out roughly $25 million of one-time favorability and results were essentially in line. Guidance still calls for declining revenue and a shrinking subscriber base. The next leg of the story depends on whether the new treads, commercial traction and stabilizing churn can turn efficiency gains into renewed growth.
Read our earnings preview for Peloton Interactive: https://www.earningswhispers.com/article/PTON/22174
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 8 hours | |
| 9 hours | |
| 10 hours | |
| Oct-28 | |
| Oct-22 | |
| Oct-06 | |
| Sep-23 | |
| Sep-23 | |
| Sep-22 | |
| Sep-22 |
Peloton is pushing beyond the bike and into 'human-centric' AI: CEO explains
PTON
Yahoo Finance Video
|
| Sep-22 | |
| Sep-22 | |
| Sep-22 | |
| Sep-22 |
