Onterris Beats On Margin Discipline And Unveils Bold 2030 Targets, But Flat Guidance And Sliding Sentiment Temper The Story
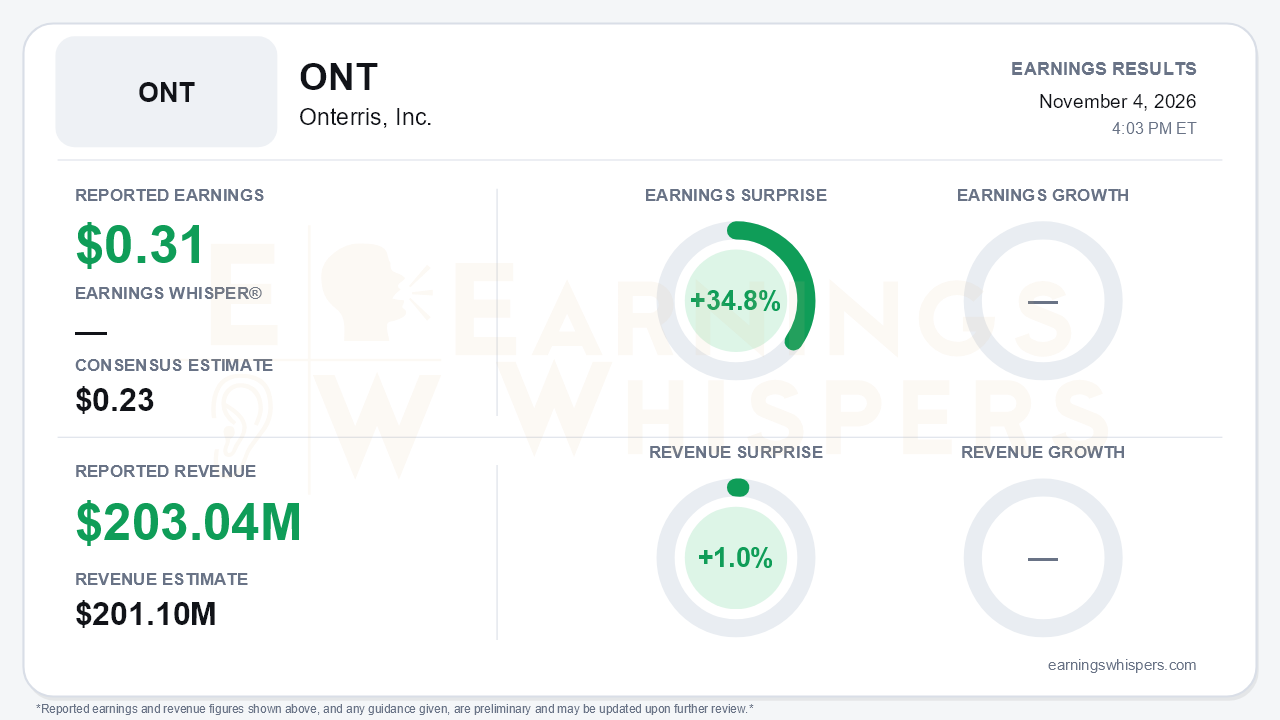
Onterris (NYSE: ONT) cleared expectations in the third quarter. Earnings Whispers puts EPS at $0.31, against a $0.23 consensus, a 34.8% surprise. Revenue of $203.04 million topped the $201.1 million estimate by 1.0%. Investors will see three different per-share figures. The company reported GAAP diluted EPS of $0.24 (up from $0.21) and adjusted EPS of $0.56 (up from $0.36), while the normalized $0.31 sits between them. The headline matters less than what management did with it. The quarter showed record margins and much stronger cash generation, and management attached aggressive 2030 targets. Full-year guidance, however, stayed exactly where it was cut in Q2. Ambitious long-term promises sitting on top of unchanged near-term numbers is the central tension.
The quality of the beat deserves scrutiny. Reported revenue fell from $224.9 million, but that comparison is distorted by a single prior-year environmental recovery event worth $45.4 million. Excluding it, revenue grew about 13.1%. Net service revenue, the cleaner measure of labor-driven work, rose only modestly to $162.5 million from $160.5 million.
Consolidated adjusted EBITDA reached a record $35.9 million at a 17.7% margin, up 270 basis points. That landed at the top of the 17-18% range management had guided. The source of the gain matters, though. Combined segment adjusted EBITDA actually dipped to $46.8 million from $47.1 million, so much of the consolidated improvement came from lower corporate and other costs rather than broad operating leverage.
The GAAP line also had help. Income tax expense fell to $2.3 million from $7.3 million, and other income included a $3.7 million insurance settlement gain. The adjusted figures strip that gain out.
Beneath the surface, the two segments are moving in opposite directions.
- **Consulting and Treatment:** Margin expanded to 21.7% from 18.4%. Core revenue excluding emergency response rose $15.3 million, and emergency response revenue climbed to $17.0 million from $11.5 million.
- **Measurement and Analysis:** This segment continues to soften. Revenue slipped to $61.1 million from $63.0 million, and margin eased to 26.1% from 27.5%, extending the erosion seen in Q2. Field services revenue also declined.
Management's tone was notably more confident than on the defensive Q2 call. It pointed to water treatment broadening beyond PFAS into industrial wastewater and municipal drinking water. It also cited proposed EPA methane-rule changes that could expand recurring optical gas imaging work.
The forward-looking upgrade is substantial. Management introduced 2030 targets of roughly 15% revenue CAGR and roughly 25% adjusted EBITDA CAGR. It also raised its organic growth expectation to about 10%, up from the prior high-single-digit framework, and laid out a path to high-teens/low-20% EBITDA margins.
Bolt-on M&A resumed with three tuck-ins totaling about $14 million. Even so, management held its year-end leverage target near 2.5x, down from 2.9x now and 3.2x in Q2.
Bears have legitimate ammunition on several fronts:
- The 2030 figures are aspirations, not guidance.
- Year-to-date reported revenue is down 12.4%.
- Full-year guidance remains $740-790 million in revenue and $117-120 million in EBITDA.
- Year-to-date operating cash flow of $35.4 million trails last year's $55.5 million, largely because of $16 million in catch-up bonus payments. The full-year 60% conversion goal depends on delivering $30-40 million in Q4.
- The roughly $20 million air-permitting headwind cited in Q2 was not updated.
The strategic review adds another layer. Evercore, AEC Advisors and Kirkland & Ellis are engaged, and the company has held discussions with multiple strategic and financial parties. Still, there is no timetable and no assurance of a transaction.
The market setup is more complicated than the surprise implies. Shares have gained 5.6% since the open following the August 5 report, the same day the strategic review was announced. At $16.13, the stock sits about 43.7% above its 200-day moving average, so considerable optimism is already in the price. Investor sentiment, meanwhile, deteriorated sharply, falling from roughly neutral at -0.07 to -0.49. That gap between firm price action and souring sentiment suggests skepticism about whether the 2030 framework, or a deal, will materialize. The internal trend readings are mixed, with sequential growth positive while AVWAP remains negative.
The bottom line is that Onterris delivered a clean operational quarter: record margins, a big cash quarter, lower leverage and a credible core growth rate once the prior-year emergency event is stripped out. But the improvement leaned heavily on corporate cost cuts and Consulting and Treatment while Measurement and Analysis kept slipping, and management chose not to raise 2026 numbers. With shares well above their long-term average and sentiment turning decidedly negative, the next leg likely depends on two things: a strong Q4 cash delivery that validates guidance, and clarity from a strategic review that has no deadline.
Read our earnings preview for Onterris, Inc.: https://www.earningswhispers.com/article/ONT/21900
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Oct-27 | |
| Oct-21 | |
| Oct-16 | |
| Oct-12 | |
| Oct-06 | |
| Sep-29 | |
| Sep-24 | |
| Sep-14 | |
| Aug-13 | |
| Aug-06 | |
| Aug-05 |
