Zoetis Clears A Lowered Bar And Lifts EPS Guidance, But Shrinking Companion Animal Sales Make This A Stabilization Quarter, Not A Recovery
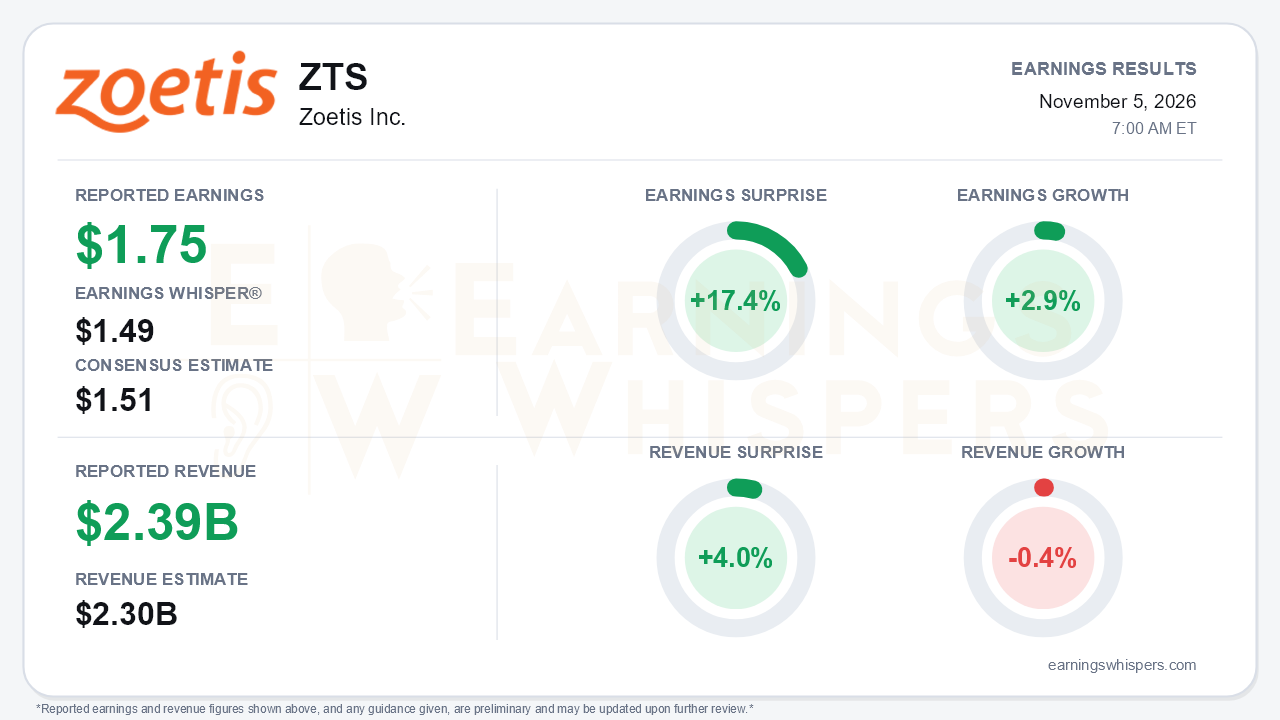
Zoetis delivered a headline beat that looks far stronger than the business beneath it. Adjusted earnings of $1.75 per share topped the $1.51 consensus and the $1.49 Earnings Whisper number by 17.4%, and revenue of $2.391 billion beat the $2.30 billion estimate by 4.0%. Profit guidance moved up for the first time after two consecutive cuts. But earnings grew only 2.9% year over year, and revenue slipped 0.4% by Earnings Whispers' measure; the company cites a 1% decline on both a reported and an organic operational basis. CEO Kristin Peck called the quarter "in line with our expectations." That framing is the central tension. The beat says more about how far expectations had fallen than about any turn in demand.
The quality of the beat deserves scrutiny. Adjusted net income fell 5% reported and 7% organic operationally to $720 million. Adjusted EPS rose only because diluted shares fell to 411.6 million from 443.2 million a year earlier. On a GAAP basis, net income dropped 18% to $591 million and diluted EPS fell 12% to $1.44. The gap reflects $133 million of certain significant items, including $89 million of impairment charges, most of it tied to in-process R&D acquired from PetMedix, plus $30 million of restructuring under a cost and productivity program. Margins also slipped. Adjusted cost of sales rose to 29.0% of revenue from 28.7%, and U.S. segment gross margin fell a full point to 82.2%.
The damage remains concentrated in Companion Animal, which fell 5% overall and 8% in the U.S.
- **Dermatology:** U.S. key derm fell 13%, and international key derm fell 20% on European Apoquel volume losses.
- **OA pain:** U.S. OA pain declined 12%, with management acknowledging safety-perception headwinds around Librella.
- **Parasiticides:** U.S. Simparica slipped 2% as heartworm visits declined.
- **Pricing:** Price turned negative at -1%, with volume flat. Management has steadily walked down its price assumption from 2-3% at the start of the year.
The call did offer evidence that the bleeding is slowing. Gross-to-net promotional programs cut U.S. derm share loss to roughly 4 points from about 7 points in the second quarter, and generic erosion on Convenia and Cerenia moderated to its lowest level since entry. Those programs come at a cost, however, pressuring price and operational gross margin by 60 basis points. Livestock, the portfolio's cushion, still grew 7%, but that is down from 11% in the second quarter and 12% in the first. Diagnostics grew 13% with help from acquisitions.
The guidance raise is real but modest, and it leans on below-the-line help. Adjusted EPS guidance rose to $6.25-$6.35 from $6.15-$6.25, and revenue was narrowed to the high end at $9.22-$9.32 billion. That improvement was aided by a lower expected tax rate (about 20% versus 20.5%) and a $15 million reduction in the R&D outlook. Reported EPS guidance actually edged down to $5.50-$5.60 as special items grew. The updated range also implies roughly a 3% organic decline in the fourth quarter. For perspective, the adjusted EPS guide started the year at $7.00-$7.10.
Looking ahead, the new CFO/COO, Jay Saccaro, said 2027 planning will assume no macro recovery, persistent competition and limited contribution from new launches. Guidance metrics will be revisited on the fourth-quarter call, and a long-acting injectable dermatology competitor, Befrena, is expected in 2027. The pipeline is the counterweight:
- **Long-acting Cytopoint:** U.S. approval expected in the fourth quarter, with launch in the first half of 2027.
- **Simparica Duo:** Approval anticipated by year-end, ahead of schedule.
- **Convenia RTU for Dogs:** FDA approval already secured, with veterinary availability expected in the first quarter of 2027.
- **Lenivia:** U.S. approval expected in 2027.
- **Cost savings:** A cost-of-goods and SG&A savings program is targeted for 2027.
- **Pipeline update:** A comprehensive review is planned for the JPMorgan conference.
The market had already begun pricing in stabilization. Investor sentiment remained negative but improved meaningfully, moving to -0.43 from -0.67. Shares rose 13.2% from the post-August open to $89.20, rallying nearly 30% off a 52-week low of $68.77 set on October 2. The stock entered the report essentially at its inter-earnings high but still about 4% below its 200-day moving average of $93.09. The Earnings Whispers trend signals remain mostly negative, with sequential growth and momentum still deteriorating even as AVWAP has turned positive. That combination suggests a relief rally running ahead of a fundamental inflection.
The bottom line is that Zoetis delivered the stabilization quarter investors needed, but not the recovery the stock's rebound may be anticipating. Slowing share losses, a rare guidance raise and an accelerating approval calendar give the call a credible floor. Bears still have legitimate ammunition: shrinking revenue, negative pricing, decelerating Livestock, a buyback-driven EPS gain and a deliberately cautious 2027 outlook. With shares near their quarterly high and sentiment still negative, the next leg likely depends on whether launches such as long-acting Cytopoint and Simparica Duo can return U.S. Companion Animal to growth.
Read our earnings preview for Zoetis Inc.: https://www.earningswhispers.com/article/ZTS/22219
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 9 hours |
Zoetis Adds To 21% Monthlong Run, Barking Up A Third-Quarter Beat
ZTS -7.95%
Investor's Business Daily
|
| 10 hours | |
| 11 hours | |
| Oct-28 | |
| Oct-20 | |
| Oct-20 | |
| Oct-13 | |
| Oct-08 | |
| Oct-07 | |
| Oct-07 | |
| Sep-24 | |
| Sep-21 | |
| Sep-11 | |
| Sep-10 |
