Viatris Edges Past The Whisper And Raises Guidance Again, But Margin Gains Are Carrying A Stalled Top Line As Nashik Escalates
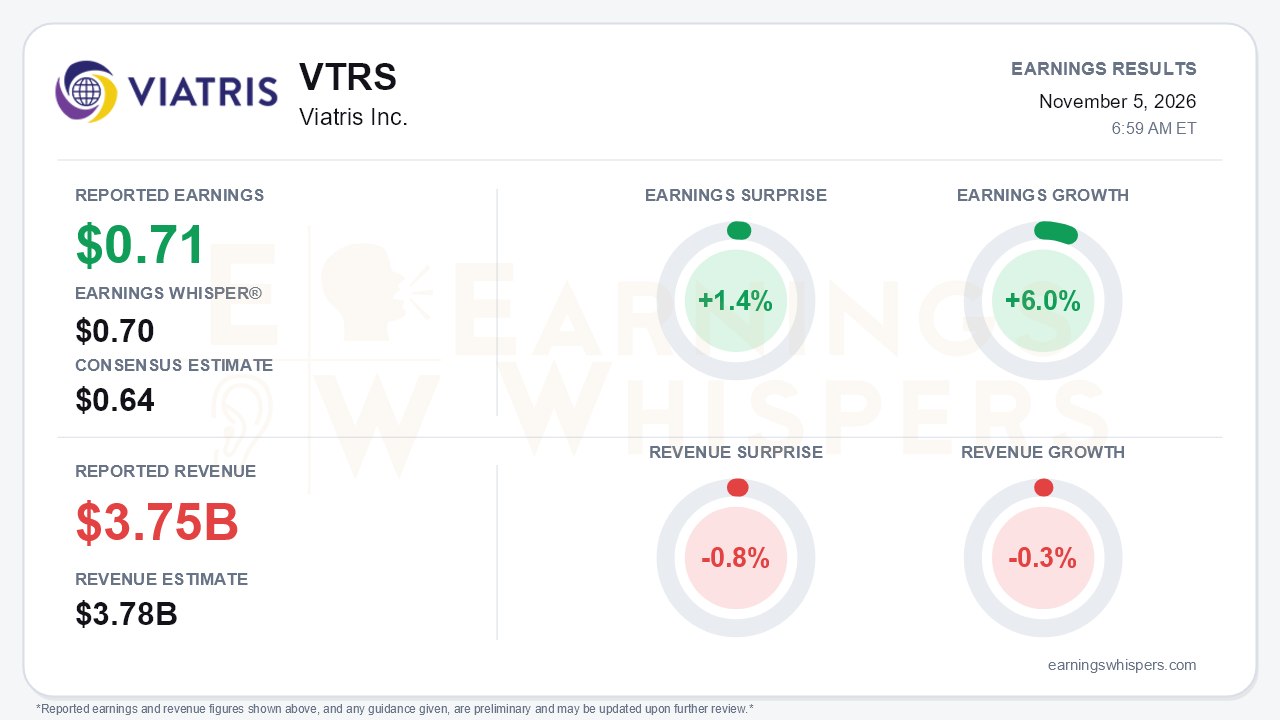
Viatris (NASDAQ: VTRS) delivered the kind of quarter that keeps an earnings-momentum story intact without fully resolving its revenue problem. Adjusted EPS of $0.71 cleared the $0.64 consensus and edged the $0.70 Earnings Whisper number, a 1.4% beat. Earnings grew 6.0% year over year, and management raised the midpoints of every 2026 guidance metric for the second straight quarter. Revenue, however, came in at $3.75 billion, missing consensus by 0.8% and slipping 0.3% from a year ago. That is the central tension. Mix, cost discipline and buybacks are producing earnings growth, while the top line remains stuck, constrained by supply problems and a narrowing set of growth regions.
The quality of the beat deserves scrutiny. Adjusted gross margin expanded to 58.0% from 56.0% a year ago, and adjusted SG&A was essentially flat at $826 million. Most of the earnings leverage therefore came from mix rather than volume. On a constant-currency basis, however, adjusted EPS rose only 3% and adjusted EBITDA just 1%, well below the 12% and 9% reported growth for the first nine months. Earnings growth is decelerating even as it continues to beat expectations. GAAP results look worse still. Pre-tax income swung to a $128 million profit from a small loss, but a $453 million tax provision tied to losses in jurisdictions with minimal realizable benefit widened the GAAP net loss to $0.28 per share from $0.11. Cash generation was the cleanest positive. Free cash flow reached $814 million, or $895 million excluding transaction and restructuring costs, up from $348 million in the first quarter.
The call explained where the business is diverging. North America was the standout, with net sales up 7%. Management lifted its full-year outlook for the region to high single-digit growth after describing it as flat in February and expecting a slight decline as recently as the second quarter. Complex generics now exceed 65% of North American generics, and estradiol patch volumes roughly doubled as capacity moved toward 24/7 operation. Elsewhere, the trend is moving the wrong way:
- **Europe:** The outlook was cut from +4% in February to flattish.
- **Emerging Markets:** Guidance fell from +6% to a low single-digit decline.
- **JANZ:** The region is now expected to decline at a low single-digit rate.
- **Greater China:** The region was still up 10% at constant currency, but growth slowed from 16–17% in the first half. Management expects Q4 growth below 10% and only low-to-mid single-digit growth in 2027 as hospital procurement policy bites.
Full-year revenue growth of roughly 2% remains below the roughly 3% operational view cited at the start of the year. The revenue guidance range was narrowed to $14.7–$14.9 billion, which lifted the midpoint but trimmed the top end.
The Nashik situation is the risk that changed most. A fire-related disruption that management framed in the second quarter as a shorter-term $100–150 million second-half issue has escalated. The FDA classified the plant Official Action Indicated, and Viatris voluntarily suspended production in October. The company estimates a roughly $100 million revenue hit in each of Q3 and Q4 and does not expect production to resume until the first quarter of 2027. Bears have legitimate ammunition here, along with additional U.S. competition in Q4 and 2027 loss-of-exclusivity headwinds from Amitiza in Japan and isosulfan blue.
The offset is a forward catalyst slate that is more substantial than a generics-heavy company usually offers:
- **Pacira BioSciences:** The $1.65 billion acquisition is expected to close by the end of November. Management called it immediately accretive to all 2027 metrics, with more than $50 million in synergies. It should push U.S. innovative medicines revenue above $1 billion in 2027 with minimal impact on leverage, which stands at 2.9x.
- **Fast-acting meloxicam:** The FDA review is described as substantially complete, with a December 27 PDUFA date and launch targeted for early 2027.
- **Recent launches and approvals:** Gwyn Lo has launched, and RYZUMVI (presbyopia) and WAKIX (Japan) have been approved.
- **Generics pipeline:** Viatris has first-to-file status on generic semaglutide tablets.
The CEO also suggested roughly $5 billion in EBITDA could be achievable well ahead of 2030 targets. That is aspiration, not guidance.
The market had already priced in much of the momentum. Shares entered the report at $19.22, up 5.9% since the open after the August release and about 21% above the mid-August low. The stock sat roughly 20% above its 200-day moving average and only 1.5% below the 52-week high of $19.51 set October 30. Investor sentiment stayed positive and improved only marginally, from 0.24 to 0.25. Most Earnings Whispers trend signals are positive, though the sequential-growth reading remains negative, consistent with a business whose earnings are outrunning its revenue.
The bottom line is that Viatris met the bar a near-high stock required: a modest beat, another guidance raise and a credible pipeline-and-M&A narrative. However, the improvement is concentrated in North America and margins, while Europe, Emerging Markets, JANZ and now China are fading and Nashik has become a regulatory problem rather than a temporary disruption. Until the top line turns, the setup depends heavily on Pacira, meloxicam and continued margin execution.
Read our earnings preview for Viatris Inc.: https://www.earningswhispers.com/article/VTRS/22211
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 8 hours |
Top 8% Drugmaker Hikes Guidance On The Back Of Its Mixed Third Quarter
VTRS
Investor's Business Daily
|
| 10 hours | |
| 11 hours | |
| Nov-04 | |
| Oct-30 | |
| Oct-30 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-19 | |
| Oct-16 | |
| Oct-16 | |
| Oct-12 | |
| Oct-09 |
