Radian's EPS Beat Rests On A Benign Catastrophe Quarter As Mortgage Profits Slip And Revenue Misses
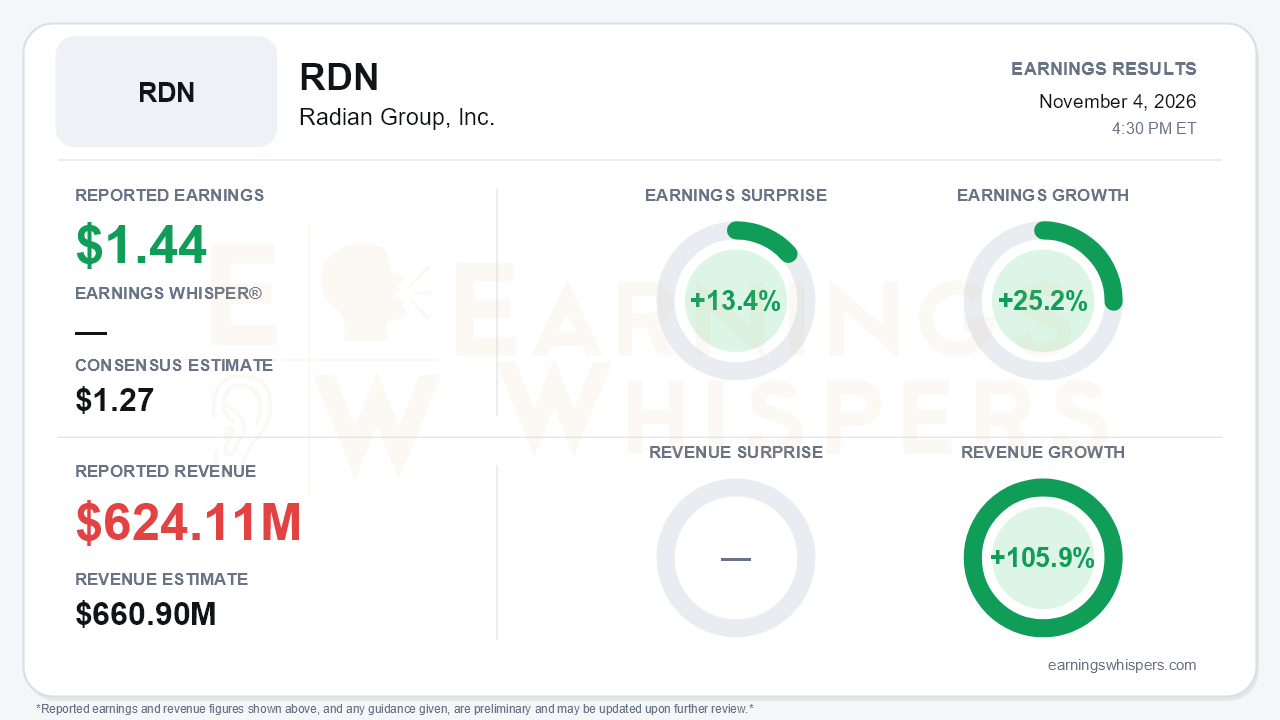
Radian Group delivered a clean earnings beat. Adjusted earnings of $1.44 per share topped the $1.27 consensus by 13.4% and grew 25.2% year over year. The top line was weaker. Revenue of $624.11 million more than doubled, up 105.9%, but missed the $660.9 million consensus by 5.6%. The quality of the beat deserves scrutiny. Nearly all of the sequential improvement came from the Specialty segment, which Radian built through its Inigo acquisition and which benefited from a quiet catastrophe quarter and sizable reserve releases. The legacy Mortgage franchise kept drifting lower. That is the central tension: the acquisition is producing earnings, but the most flattering part of this quarter is also the least repeatable.
Specialty swung sharply. Its combined ratio improved to 80.4% from 97.7% in the second quarter, and adjusted pretax income roughly tripled to $86 million from $29 million. Two factors drove it.
- The current-period loss ratio fell to 61.3% from 72.3%, which management attributed to a benign catastrophe quarter.
- Favorable prior-year development reached $43 million, worth 13.7 points of the loss ratio, up from 9.0 points last quarter.
Neither factor is a structural improvement. On the August call, management had guided the Specialty combined ratio to the low 90s after a second quarter weighed down by roughly $30 million of Middle East and inflation reserves. A low-80s result is therefore a favorable outcome against that guidance, not a new run rate. Gross premiums written of $310 million fell from a seasonally heavy $504 million in the second quarter, though they were up from Inigo's $285 million in the year-ago period. The release explicitly flags a "softening premium rate environment" in Specialty, which caps how much top-line help investors should expect from that side of the business.
Beneath the consolidated growth, Mortgage is the weaker story. Segment adjusted pretax income of $206 million was down from $225 million a year ago, and the segment has declined every quarter over the past year. The combined ratio rose to 36.6% from 27.0%, driven by several pressures.
- **Higher loss ratio:** the loss ratio climbed to 13.5% from 7.5%.
- **Smaller reserve releases:** favorable development shrank to $26 million from $35 million.
- **Rising defaults:** the default rate rose to 2.68% from 2.47% last quarter and 2.42% a year ago.
- **Slower new business:** new insurance written fell 5% year over year to $14.7 billion and declined sequentially from $16.3 billion.
There are offsets. Insurance in force reached a record $286 billion, persistency held near 83%, and new business continues to skew toward borrowers with credit scores of 740 or higher. Still, a steady earned-premium base of about $237 million against rising credit costs points to slow margin erosion, not collapse. Corporate costs add to the drag. Acquisition-related interest pushed the corporate loss to $39 million from $19 million a year ago.
The conference-call materials available for this review largely restated commentary from earlier in the year and offered little genuinely new third-quarter disclosure. The forward picture therefore rests on the release and the guidance management gave in August. That guidance included a Specialty combined ratio in the low 90s, an expected second-half lift in Specialty earned premium, softening Specialty pricing, and mortgage claim severity drifting higher.
Capital return is the clearest positive. Year-to-date repurchases total $379 million, or 8% of shares outstanding, including $117 million in October. That pace already exceeds the $200 million to $250 million range discussed in August, and $484 million of authorization remains. Radian Guaranty expects to pay more than $650 million of ordinary dividends to the parent in 2026, subject to regulatory approval. The trade-off is a thinner cushion. Holding company liquidity is $376 million versus $995 million a year ago, although the $500 million revolver is undrawn. Book value per share also slipped to $35.78 from $36.00 last quarter as unrealized investment losses widened.
Investors entered the report noticeably cooler. Earnings Whispers sentiment swung from a modestly positive 0.23 after the August report to a slightly negative -0.08. The stock has gone essentially nowhere, down 1.5% since the post-August open at $36.56. It still sits 3.7% above its 200-day moving average of $35.24. The trend readings are mixed, with price trend negative while AVWAP remains positive. Overall, the market appears to be treating the Inigo-driven growth with caution rather than conviction.
The bottom line is that Radian's beat was real but flattered by catastrophe luck and reserve releases in Specialty. Meanwhile, the core Mortgage business shows rising defaults, slipping new business, and a fourth straight quarter of lower segment profit. Aggressive buybacks and strong subsidiary dividends support per-share growth. Durable upside, however, requires Specialty to hold margins near its low-90s guidance through a softening pricing cycle and Mortgage credit to stabilize. Bears have legitimate ammunition until both happen.
Read our earnings preview for Radian Group, Inc.: https://www.earningswhispers.com/article/RDN/21920
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 12 hours | |
| Nov-04 | |
| Nov-04 | |
| Oct-28 | |
| Oct-27 | |
| Oct-23 | |
| Oct-09 | |
| Sep-10 | |
| Aug-13 | |
| Aug-12 | |
| Aug-10 | |
| Aug-05 | |
| Aug-05 | |
| Aug-03 | |
| Jul-17 |
