Shift4 Beats On Q3 EPS, But Lower Guidance And Falling Profits Keep The Bar Low
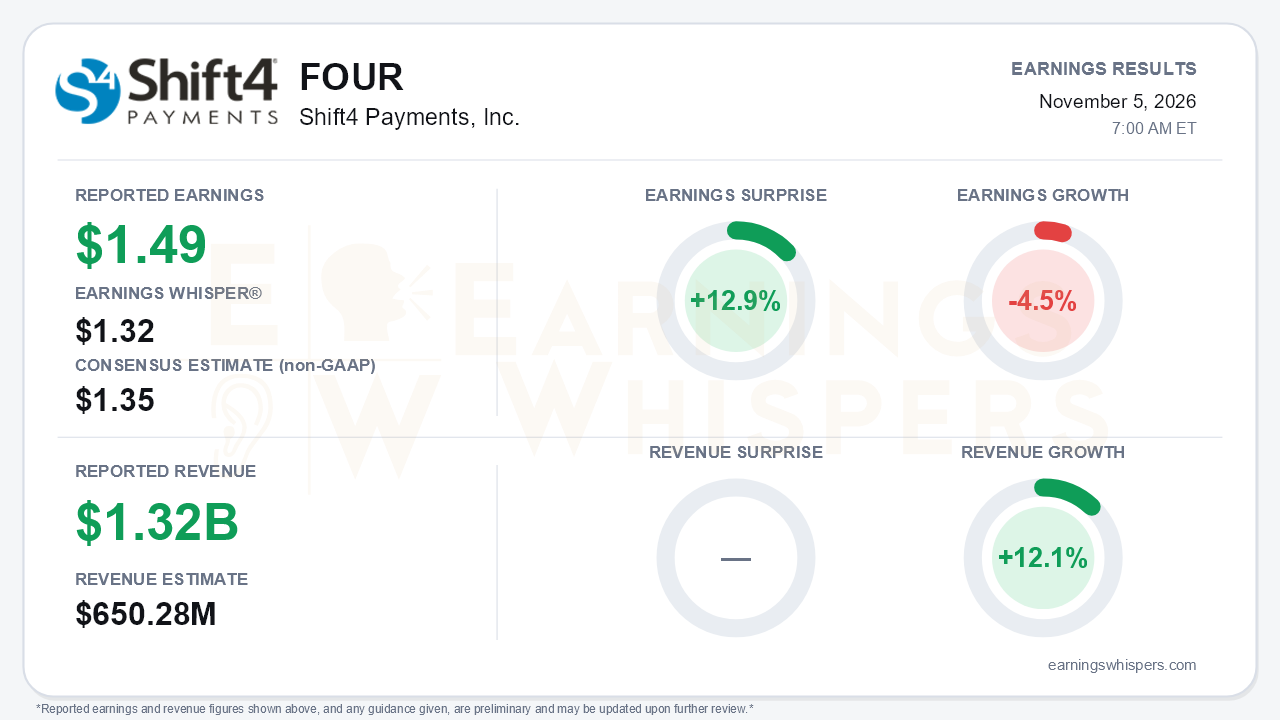
Shift4 Payments (NYSE: FOUR) cleared a low bar in the third quarter. Non-GAAP earnings of $1.49 per share beat the $1.35 consensus by 12.9% and topped the $1.32 Earnings Whisper number. That is a solid beat in absolute terms, yet earnings still fell 4.5% from a year ago. The company also lowered guidance again. That is the central tension: Shift4 keeps outperforming near-term estimates while the full-year earnings outlook keeps moving down.
The headline revenue figure needs context. Shift4 reported $1.319 billion in revenue, up 12.1% year over year, against a $650.28 million consensus. The resulting 102.8% surprise appears to compare two different revenue measures. Shift4's gross revenue was $1.29 billion in the second quarter, while gross revenue less network fees (GRLNF) was $624 million. The consensus figure looks aligned with the net measure, so the surprise should not be read as Shift4 doubling expectations. The more telling number is the 12.1% growth rate. It is a sharp slowdown from the 51% GRLNF growth reported in Q2, which was inflated by the Global Blue acquisition. Management said tax-free shopping (TFS), the Global Blue business, would roll into the organic growth calculation starting next quarter, which suggests the acquisition comparison is now being lapped. Earnings falling while revenue grows in double digits points to the cost pressures management had already flagged.
The filing supplied here is only a link to the shareholder letter, and the available call analysis comes from the August second-quarter call rather than this report. Third-quarter operating detail is therefore limited. The August call still sets the framework for this quarter, and it was mixed:
- **Demand was strong.** Worldwide payments-based growth reached 53% and Americas payments grew 19%, both ahead of plan. TFS pro forma growth doubled to 8%, and the blended spread widened to 65 basis points from 57 basis points two quarters earlier.
- **Margins were moving the wrong way.** Adjusted EBITDA margin slipped to 46% from 50% in Q4 2025. Management attributed the decline to record product investment and the Global Blue sales build-out, and pushed synergies to 2027.
- **Guidance was already cut once.** The full-year non-GAAP EPS outlook fell to $5.15–$5.35 from $5.50–$5.70, and EBITDA and free-cash-flow targets also came down.
- **Q3 was expected to absorb specific headwinds.** These included roughly $25 million of Middle East travel disruption, about $20 million of currency headwind for the full year and higher interest expense from the new $1 billion term loan.
That backdrop explains the EPS beat alongside year-over-year earnings decline. The quarter was guided conservatively, but the cost structure and financing burden are real.
The forward debate centers on whether the current investment phase pays off before the balance sheet becomes a constraint.
- **Catalysts:**
- Shift4One expansion toward 15-plus countries by year-end.
- SkyTab launches in Spain and Australia.
- Luxury-retail TFS wins including Ralph Lauren and Burberry.
- Dynamic currency conversion going live with U.S. customers.
- The CEO's suggestion of a path to 50% EBITDA margins.
- **Risks:**
- Pro forma net leverage had climbed to 3.7x, close to the company's 3.75x ceiling, and buybacks were slowed.
- The August Q4 outlook assumed no Middle East impact, leaving downside if disruption persists.
- Management expected subscription revenue to moderate to low single digits.
- Another guidance reduction raises questions about how firm the 2027 synergy story is.
Investor sentiment was negative heading into the report but had improved meaningfully, rising to -0.39 from -0.58 at the prior release. That shift suggests some of the guidance damage was already absorbed. The stock tells a similar story of a bruised but recovering name. Shares traded at $44.82 the day before the report, down 5.5% from the $47.45 open following August's results. They sat about 2.7% below the 200-day moving average. The inter-earnings range was wide: a high of $51.07 in late August, then a slide to $35.27 on October 1. The stock entered the report about 27% off that low but still roughly 12% below the high. The Earnings Whispers price and AVWAP trend readings remain negative, while sequential growth and momentum are neutral.
The bottom line is that Shift4 delivered a credible earnings beat against modest expectations, but the report did not resolve the core problem. Profits are shrinking year over year, growth is decelerating as the Global Blue comparison laps, and guidance is moving lower rather than higher. Demand and spread trends from the prior call remain encouraging. The near-term story, however, depends on margin recovery, deleveraging and 2027 synergies that investors have not yet seen.
Read our earnings preview for Shift4 Payments, Inc.: https://www.earningswhispers.com/article/FOUR/22095
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-22 | |
| Oct-15 | |
| Oct-02 | |
| Aug-26 | |
| Aug-25 | |
| Aug-25 | |
| Aug-25 | |
| Aug-11 | |
| Aug-06 | |
| Aug-06 |
