MACOM Delivers An Accelerating Beat-And-Raise As Data Center Surges, But A Steep Pre-Report Sell-Off Shows The Market Is Weighing Capex And Order Cadence
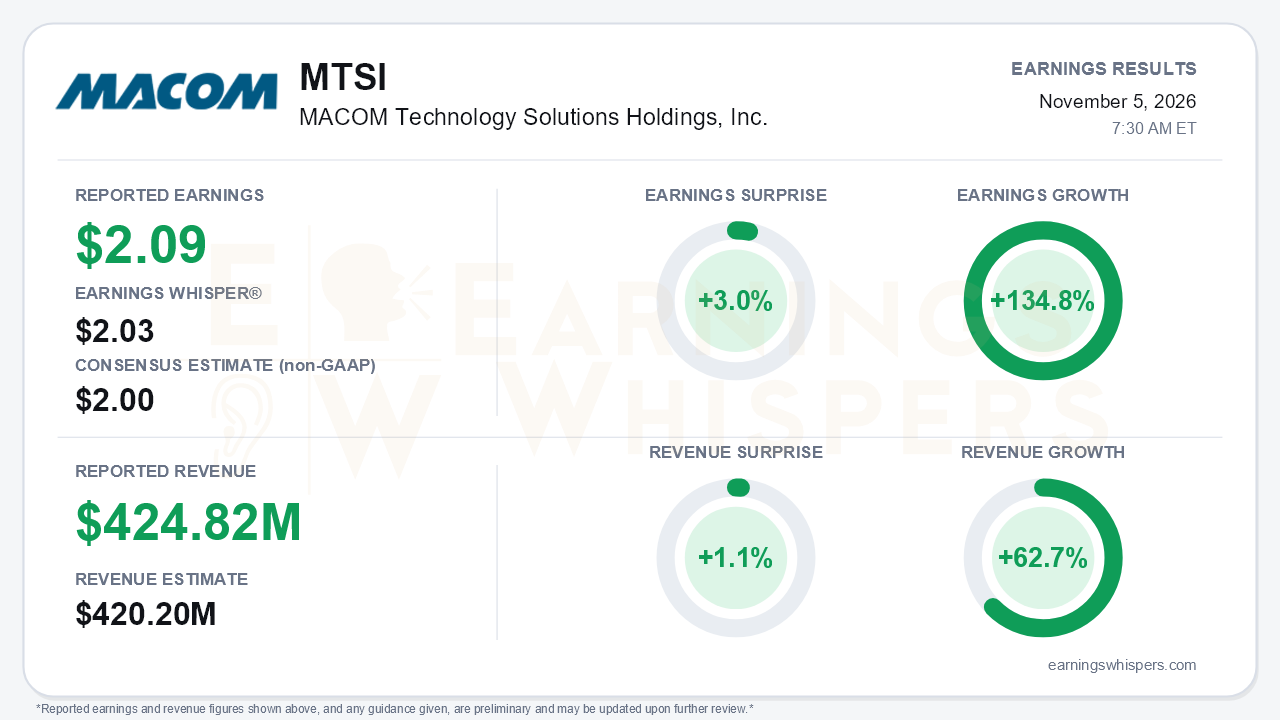
MACOM closed fiscal 2026 with its strongest quarter yet. Fiscal fourth-quarter adjusted earnings of $2.09 per share beat the $2.00 consensus by 3.0% and cleared the $2.03 Earnings Whisper number. Revenue of $424.8 million topped the $420.2 million estimate by 1.1%. Growth accelerated: earnings rose 134.8% year over year and revenue rose 62.7%, with sales up 24.1% from the July quarter. The beat itself was modest, landing at the top of management's $415-$425 million revenue guide. The bigger story is the forward setup. First-quarter guidance came in above estimates, and management lifted its fiscal 2027 data center growth base case to roughly 80%. The central tension is that fundamentals are accelerating while the stock has been sold hard.
The quality of the quarter holds up well. Adjusted gross margin reached 61.3%, up 160 basis points sequentially and 420 basis points from a year ago. Adjusted operating expenses rose only about $1.5 million from the July quarter while revenue climbed $82.6 million. That leverage pushed adjusted operating margin to 38.2%, up from 31.5% in the prior quarter and 25.6% a year earlier. GAAP net income of $139.4 million, or $1.78 per share, included a $19.4 million unrealized gain on investment fair value. The non-GAAP figure strips that gain out, so the adjusted beat is not flattered by mark-to-market income. Operating cash flow reached $357 million for the year, well above the more than $300 million target. Net cash rose to $451.7 million, even with $340.7 million of convertible notes now classified as short-term debt. One watch item is working capital: receivables grew about 41% and inventory added $46 million during the year.
Data center is the engine. Segment revenue hit $188.1 million, up 37% sequentially and nearly double the $98.2 million reported two quarters earlier. Management repeatedly raised its fiscal 2026 data center outlook, from 20% early in the year to an actual 74%. The new roughly 80% base case for fiscal 2027 compares with about 50% framed on the prior call. Industrial and defense grew 27.8% in fiscal 2026, well ahead of the 15-20% initially expected, and is targeted to grow more than 30%. Telecom is the soft spot. It grew just 1% sequentially, faces PON and broadband softness, and is guided flat to slightly down in the December quarter, with 5G ramps weighted toward the back half.
The catalyst list lengthened considerably:
- a 3.2T front-end chipset;
- co-packaged optics engagements with multiple hyperscalers;
- a 200G linear equalizer expected to generate revenue in the second half of fiscal 2027;
- a CW laser facet breakthrough supporting merchant entry in 2028;
- a new LEO constellation win worth about $20 million starting in early 2028;
- a CHIPS Act agreement expected within one to two quarters.
Management also framed roughly $2 billion of fiscal 2027 revenue, about $10 in EPS, and a $5 billion revenue aspiration by 2030. These are management ambitions, not guidance. Bears still have legitimate ammunition. Book-to-bill eased to 1.4 from 1.6 in the prior quarter and 1.5 the quarter before, though backlog is at a record. Capex is stepping up to $100-$110 million from the roughly $60 million range signaled earlier, and R&D is heading toward about $300 million. The non-GAAP tax rate doubles to about 6%, and gross margin gains are expected to slow to 25-50 basis points per quarter. SiGe foundries are demanding firm capacity commitments, and management flagged input-cost inflation, competition from integrated CMOS approaches in co-packaged optics, and execution risk on second-half ramps.
The market setup is more complicated than the surprise implies. Shares peaked at $353.54 on October 6. They then fell to an inter-earnings low of $209.51 on November 4, the day before the report. The latest snapshot of $233.13 sits 34.1% below that high, 13.7% below the $270 open after the August report, and 17.7% under the 200-day moving average. Investor sentiment nonetheless improved moderately, from 0.54 to 0.63. The Earnings Whispers trend readings are split, with sequential growth and momentum positive while price and AVWAP remain negative. That split mirrors the gap between the operating story and the tape.
The bottom line is that MACOM delivered an accelerating, high-quality quarter and a guide that lifts both revenue and margins: December-quarter EPS of $2.21-$2.29 implies further growth despite a heavier tax rate. The beat was not large, though, and the slower order cadence, heavier capex, telecom softness and decelerating margin gains give skeptics specific concerns to point to after a 34% drawdown from the October peak. Fundamentals are clearly moving in the right direction. Whether the market re-rates the stock likely depends on data center bookings and evidence that the capacity spend converts into the second-half ramps management is promising.
Read our earnings preview for MACOM Technology Solutions Holdings, Inc.: https://www.earningswhispers.com/article/MTSI/22148
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-22 | |
| Oct-06 | |
| Sep-29 | |
| Sep-18 | |
| Sep-17 | |
| Sep-15 | |
| Aug-06 | |
| Jul-23 | |
| Jun-26 | |
| Jun-09 | |
| Jun-08 | |
| Jun-05 |
