ARKO Misses On EPS As Fuel-Margin Windfall Masks Accelerating Gallon Declines
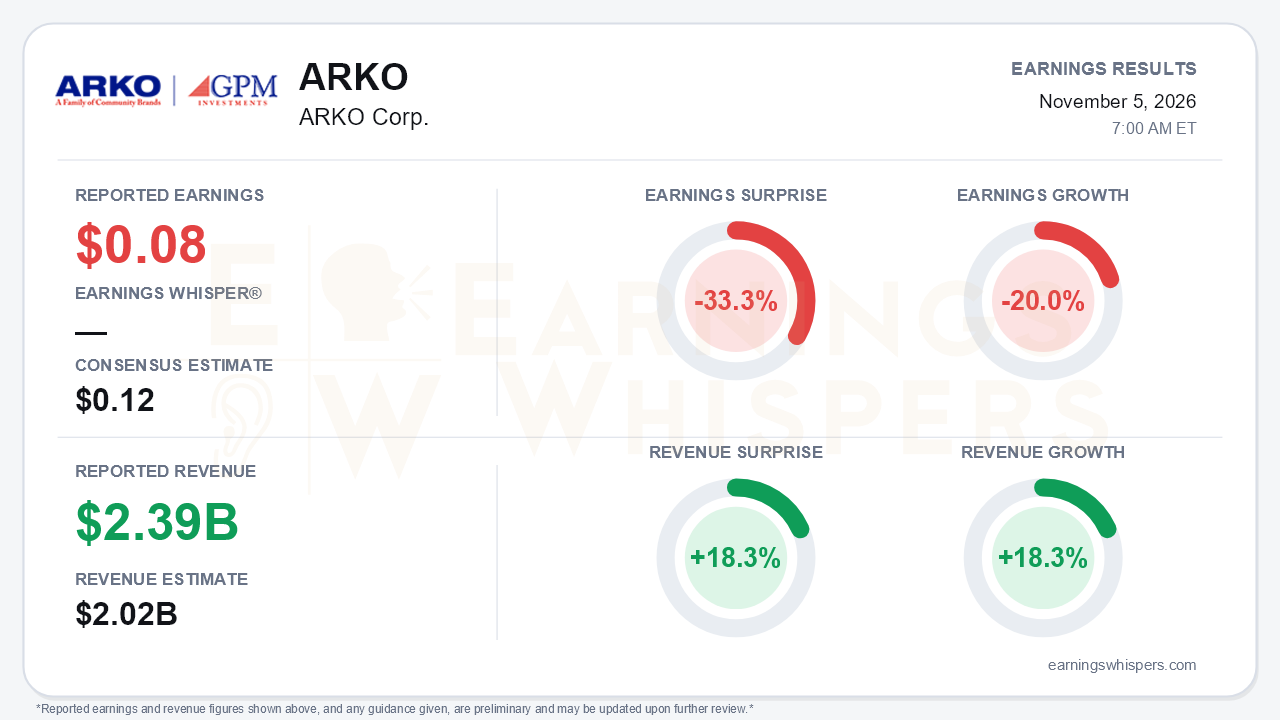
ARKO Corp. reported third-quarter earnings of $0.08 per share, missing the $0.12 consensus by 33.3%. Earnings fell 20.0% from a year ago. Revenue of $2.39 billion beat the $2.02 billion consensus by 18.3% and grew 18.3% year over year, but that top-line strength says almost nothing about demand. Fuel revenue jumped to $2.01 billion from $1.60 billion on sharply higher pump prices. Retail gallons sold actually fell to 205.6 million from 238.6 million, and merchandise revenue shrank. The central tension is that ARKO is earning more per gallon on a shrinking base of gallons. Elevated, geopolitically driven fuel margins are currently strong enough to paper over a deteriorating volume trend.
The quality of the quarter deserves scrutiny at both ends of the income statement. Adjusted EBITDA of $75.7 million edged past last year's $75.2 million, a return to growth after the second quarter's decline. Consolidated GAAP net income also rose to $14.3 million from $13.5 million. Per-share results fell, however, for two reasons:
- Following the February IPO of ARKO Petroleum Corp. (APC), $3.6 million of net income now belongs to non-controlling interests.
- Income tax expense climbed to $9.8 million from $2.4 million.
Net income attributable to common stockholders dropped to $9.2 million from $12.0 million. Pre-tax results were also helped by a $4.9 million gain from repurchasing senior notes below par.
On the operating side, margin is doing the heavy lifting. Same-store retail fuel margin rose 4.6 cents to 48.8 cents per gallon, which lifted same-store fuel contribution 2.7%. The company attributes that improvement primarily to fuel-market volatility. Merchandise margin expanded 110 basis points to 34.8%, the 12th straight quarter of year-over-year improvement. Wholesale and fleet operating income rose 7% and 8.9%, respectively, partly on prompt-pay discounts tied to higher fuel costs.
Demand is moving the wrong way. Same-store gallons fell about 7%, worsening from roughly -3.2% in the first quarter and -5.7% in the second. Same-store merchandise sales declined 1.4%, and sales excluding cigarettes were flat, down from +0.4% in the first quarter. Promotional spend rose roughly 16% to defend traffic. High fuel prices also cut the other way: same-store operating expenses rose 4.0%, including $3.1 million of incremental credit card fees, following $3.3 million in the second quarter.
Management emphasized the retained-store portfolio. Merchandise sales excluding cigarettes grew 0.8% in those stores, which have been positive every quarter this year. Management said these roughly 900 stores generate about 98-99% of retail operating profit. That is a credible core, but it is a narrow one.
Guidance was raised, though with caveats:
- **EBITDA range:** The low end of full-year adjusted EBITDA guidance rose to $250 million, giving a range of $250-265 million.
- **Fuel margin:** The retail fuel margin outlook moved up for a second time, to 47-49 cents per gallon, explicitly to offset lower volumes.
- **Acquisition dependence:** Management cited the expected fourth-quarter close of the USPP acquisition as one basis for the raise. USPP adds about 280 million gallons and about $30 million of annualized EBITDA to APC for $205 million in cash plus inventory.
- **Fourth-quarter outlook:** The implied fourth quarter still points to a year-over-year decline against a strong prior-year period.
Bears also have execution ammunition. The dealerization program's completion target slipped from the end of 2026 to the end of 2027, though about 55 more sites are committed. Cardlock openings total seven through October against a 20-unit target for 2026.
The balance sheet shows capital being deployed aggressively:
- Cash fell to $184 million from $246 million in the second quarter.
- Operating cash flow slipped to $33.2 million from $49.4 million as receivables and inventory swelled with fuel prices.
- Capital expenditures rose to $41.4 million from $24.9 million.
- The company repurchased $62.1 million of 5.125% notes for $56.8 million.
Net debt of about $441 million and roughly $1.0 billion of liquidity leave room for the USPP deal, but free cash generation was thinner this quarter.
The market had already priced in considerable pessimism. Shares stood at $4.04 heading into the report, down 40.2% from the $6.76 open after the August release. That leaves them 32.3% below the 200-day moving average of $5.97. The stock set a 52-week low of $3.61 on October 29 and sat only about 12% above that level. Investor sentiment nonetheless swung meaningfully, from -0.21 to +0.38, suggesting expectations had shifted toward a better outcome than the price action implied. The Earnings Whispers trend signals remain mostly negative, with price, sequential growth and AVWAP all pointing lower.
The bottom line is that ARKO delivered an EPS miss wrapped in a revenue beat that is largely a fuel-price artifact. Fuel margins, merchandise mix and an acquisition not yet closed are holding EBITDA steady while gallons and traffic erode at an accelerating pace. The retained-store core and the APC growth platform give the story a credible foundation. However, the raised outlook leans heavily on fuel-margin conditions management attributes to market volatility, and the transformation timeline has stretched. Improved sentiment around a depressed stock may reward stabilization, but the volume trend is the variable that will determine whether this margin-driven quarter proves durable.
Read our earnings preview for ARKO Corp.: https://www.earningswhispers.com/article/ARKO/22044
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-26 | |
| Aug-17 | |
| Aug-12 | |
| Aug-10 | |
| Aug-07 | |
| Aug-07 | |
| Aug-06 | |
| Jul-30 | |
| Jul-22 | |
| May-18 | |
| May-08 |
