Tanger Raises Guidance A Third Time As Same-Center NOI Accelerates, But Core FFO Growth Decelerates And Misses The Whisper
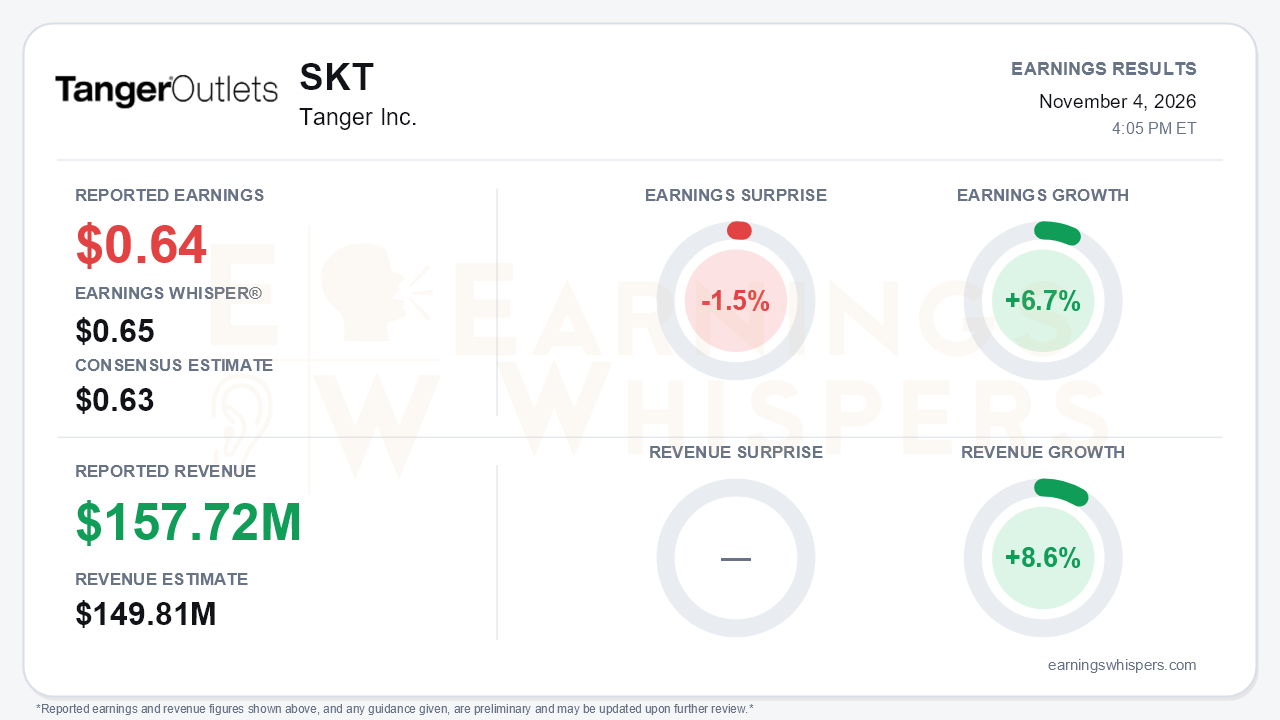
Tanger (NYSE: SKT) reported third-quarter core FFO of $0.64 per share, a penny above the $0.63 consensus but short of the $0.65 Earnings Whisper number, a 1.5% miss against the higher bar. Revenue was much stronger: $157.72 million, 5.3% above the $149.81 million consensus and up 8.6% year over year. Earnings grew 6.7% from $0.60 a year ago. The headline lands well short of a clean beat, yet management raised full-year guidance for the third straight time. That is the central tension. Property-level fundamentals are accelerating, while per-share earnings growth is slowing and some leading indicators are cooling.
The deceleration in the bottom line is real. The 6.7% core FFO growth follows roughly 10% in the second quarter and 11% in the first. The release points to several causes. Consolidated interest expense rose to $19.3 million from $16.4 million. G&A climbed about 10%. Depreciation also stepped up as recent acquisitions joined the portfolio. Cash-flow quality also deserves scrutiny. Second-generation tenant allowances and leasing costs reached $32.1 million through nine months, versus $12.2 million a year earlier. As a result, the year-to-date FAD payout ratio rose to 64% from 58%, and FAD itself declined even as FFO grew. Management attributed the higher Q3 allowances to new leases that carry higher starting rents and longer terms, which is a reasonable trade but not a free one. On a GAAP basis, net income rose modestly to $0.29 per share from $0.28.
Beneath that, the operating story improved. Same-center NOI grew 4.2%, accelerating from 3.5% in Q2 and 2.6% in Q1. The base-rent contribution to that growth jumped to 2.9% from 1.3%. Occupancy recovered 70 basis points sequentially to 97.3% after the Saks-related dip in the prior quarter, with three Saks boxes temp-leased and two held for new tenants. Blended trailing-twelve-month cash spreads ticked up to 11% from 10.5%, driven by re-tenanting spreads of 28.6%. Renewals executed or in process covered 73% of 2026 expirations, up from 70% in Q2. Management also said it is further ahead on 2027 renewals than it was a year ago and has started 2028 conversations. Other revenue, including advertising, EV charging and sponsorships, rose 11%. The tone on the call was confident but measured rather than more exuberant.
The guidance raise reflects that improvement. Core FFO guidance moved to $2.49-$2.53 from $2.45-$2.52, and from $2.41-$2.49 at the start of the year. The low end of same-center NOI guidance rose to 3.5% from 2.75%, with the 4.25% high end unchanged. Against the $1.87 already earned, however, the range implies roughly $0.62-$0.66 for Q4. Q4 will also lose interest income on roughly $200 million of cash used to retire the $350 million of September notes. The raise was in line with estimates, so it reduces uncertainty without resetting the bar.
Bears have legitimate ammunition on the forward indicators. Tenant sales per square foot were $487, flat sequentially. Year-over-year sales growth slowed to 2.5% from about 5% in Q2 and 7% at the end of 2025, as management cited July-August consumer inflation worries before a Labor Day rebound. Trailing-twelve-month leasing volume fell to about 2.6 million square feet from 3.3-3.4 million. Children's Place was flagged as a credit watch item. Bond-market volatility is widening bid-ask spreads and slowing acquisitions, with nothing announced since Levis Commons. Analysts also pressed on multi-year deceleration in full-year same-center NOI growth. On the other side, the balance sheet gives Tanger flexibility. Net debt to Adjusted EBITDAre improved to 4.6x, floating-rate debt is about 7% of the total, and management plans to prepay a $115 million Kansas City mortgage in December. The dividend was raised 7% to $0.3125.
Investors entered the report with tempered expectations. Earnings Whispers sentiment fell to 0.02 from 0.17 at the prior report, slipping to roughly neutral. Shares closed at $38.46, down 5.5% from the $40.69 open after the August report, even though guidance was raised in the interim. The stock still sits about 4.7% above its 200-day moving average of $36.73. Momentum and AVWAP readings remain positive, while the price trend has turned negative, which fits a stock that has drifted lower within a longer-term uptrend.
The bottom line is that Tanger's property engine is strengthening, with accelerating same-center NOI, recovering occupancy, firmer spreads and a third guidance raise. Per-share growth, however, is decelerating under heavier interest, G&A and leasing-capital costs, and tenant sales and leasing volume are cooling. A narrow miss against the whisper and fading sentiment suggest the market wants evidence that the NOI acceleration can outrun those headwinds into 2027.
Read our earnings preview for Tanger Inc.: https://www.earningswhispers.com/article/SKT/21938
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Oct-27 | |
| Oct-15 | |
| Sep-09 | |
| Aug-28 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-31 | |
| Jul-15 |
