Palvella's Narrow Miss Is A Sideshow: Priority Review Sets A February 2027 Verdict As Launch Spending Accelerates
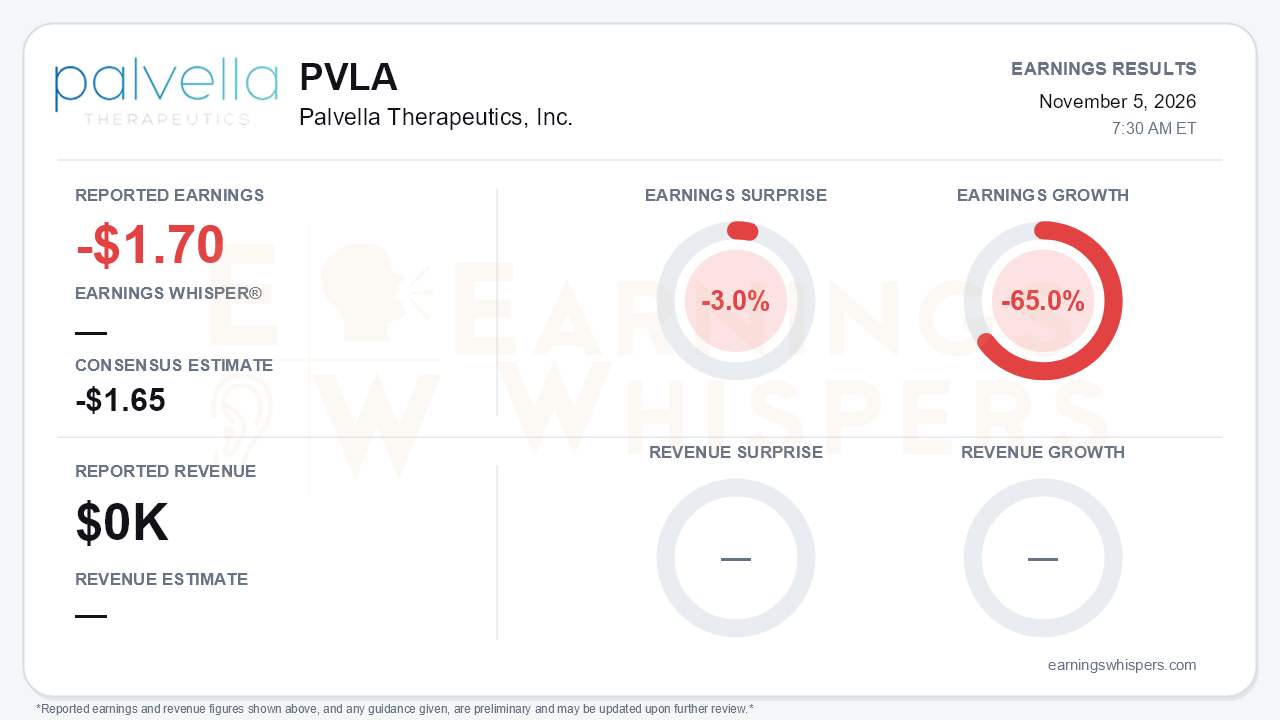
Palvella Therapeutics reported a third-quarter loss of $1.70 per share, missing the consensus estimate of -$1.65 by 3.0%. Earnings fell 65.0% year over year, from a loss of $1.03 per share a year earlier. As a pre-revenue company, Palvella reported no sales. The miss matters far less than the regulatory news that came with it. The FDA accepted the NDA for QTORIN rapamycin in microcystic lymphatic malformations (LMs) and granted Priority Review, with a PDUFA target action date of February 28, 2027. Palvella is no longer pitching a vague first-half 2027 approval target. It now has a dated binary event and a six-month review clock, and the quarter's numbers are best read as the cost of preparing for that date.
That cost is rising quickly. Net loss more than doubled to $24.6 million from $11.3 million. General and administrative expense more than tripled to $11.9 million from $3.6 million as the company hired its commercial organization. R&D climbed to $10.8 million from $6.5 million on manufacturing, the angiokeratoma program and completion of the NDA. The per-share loss also absorbed a weighted share count of roughly 14.5 million, up from 11.1 million, a reminder that the company's $236.7 million cash position was built partly through dilution. Cash fell about $14 million from roughly $251 million at the end of the second quarter. Management guided the fourth quarter to be the largest spending quarter yet. 2026 cash spend is now tracking below the $85-95 million guidance, but management characterized those savings as deferred into early 2027 rather than eliminated.
The call showed a company moving from development into pre-launch, and the commercial build has stepped up at each update. Rep targets went from 20-40 late last year to about 40 last quarter. Palvella now has a field team of roughly 70, including about 40 reps, plus in-house patient services, mostly in place about two months before PDUFA. Management also presented new demand evidence:
- More than 70% of over 150 surveyed physicians said they expect to prescribe within three months of approval, often starting several patients at once.
- Payer testing indicated no step-through requirement and support for orphan pricing of $100,000-$200,000 per patient per year.
- An LLM-based chart-note analysis suggested upside to the 30,000-plus diagnosed patient estimate.
Peak sales are still framed at more than $1 billion. In the pipeline, new claims work lifted the diagnosed DSAP population to about 155,000 from the more than 50,000 previously cited, and 24-week TOIVA data in cutaneous venous malformations (VMs) improved on the 12-week readout.
Bears still have legitimate ammunition. Management deliberately tempered launch expectations. It called the early launch a "wiring period" in which revenue lags demand, said Medicaid access could take one or more quarters, said no initial bolus of patients is expected, and declined to provide 2027 revenue guidance. The cutaneous VM Phase 3 design has not been finalized with the FDA, and initiation is still guided for the current quarter, leaving almost no room before the timeline slips. Breakthrough designation was denied earlier, and the promised fourth rapamycin indication and third QTORIN product candidate remain unannounced late in the year. Runway language also shifted from "through cash flow breakeven" to "deep into the commercial launch." Management said its runway view has not changed, but the wording is softer.
The market setup is more complicated than the small miss implies. Shares closed at $162.28 on the eve of the report. That is up 19.9% from the open after the August report and 27.2% above the 200-day moving average. The stock had rallied about 37% from an October 16 low of $118.23 to a 52-week high of $163.75 on November 4, so it entered earnings within 1% of that peak. Investor sentiment remained negative but improved meaningfully, rising to -0.29 from -0.42. Momentum and AVWAP trend readings are positive while the price trend is neutral. Much of the Priority Review optimism was likely priced in during the run-up, which leaves less cushion if launch commentary disappoints.
The bottom line is that Palvella's third quarter was about regulatory progress, not the EPS miss. A firm February 2027 PDUFA date, a staffed commercial team and encouraging physician and payer research give the microcystic LM opportunity a more credible shape. However, rising spending, cautious guidance on early revenue, unresolved cutaneous VM trial design and overdue pipeline announcements mean execution risk is increasing even as the regulatory picture clears. Shares entered the report near their highs, so investors are already paying for a successful approval.
Read our earnings preview for Palvella Therapeutics, Inc.: https://www.earningswhispers.com/article/PVLA/22451
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-03 | |
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-15 | |
| Oct-13 | |
| Oct-12 | |
| Sep-28 | |
| Sep-17 | |
| Sep-09 | |
| Sep-02 | |
| Aug-31 |
