Onity's Servicing Rebound Lifts Results, But Fading Originations And Low-End Guidance Keep The Recovery Narrow
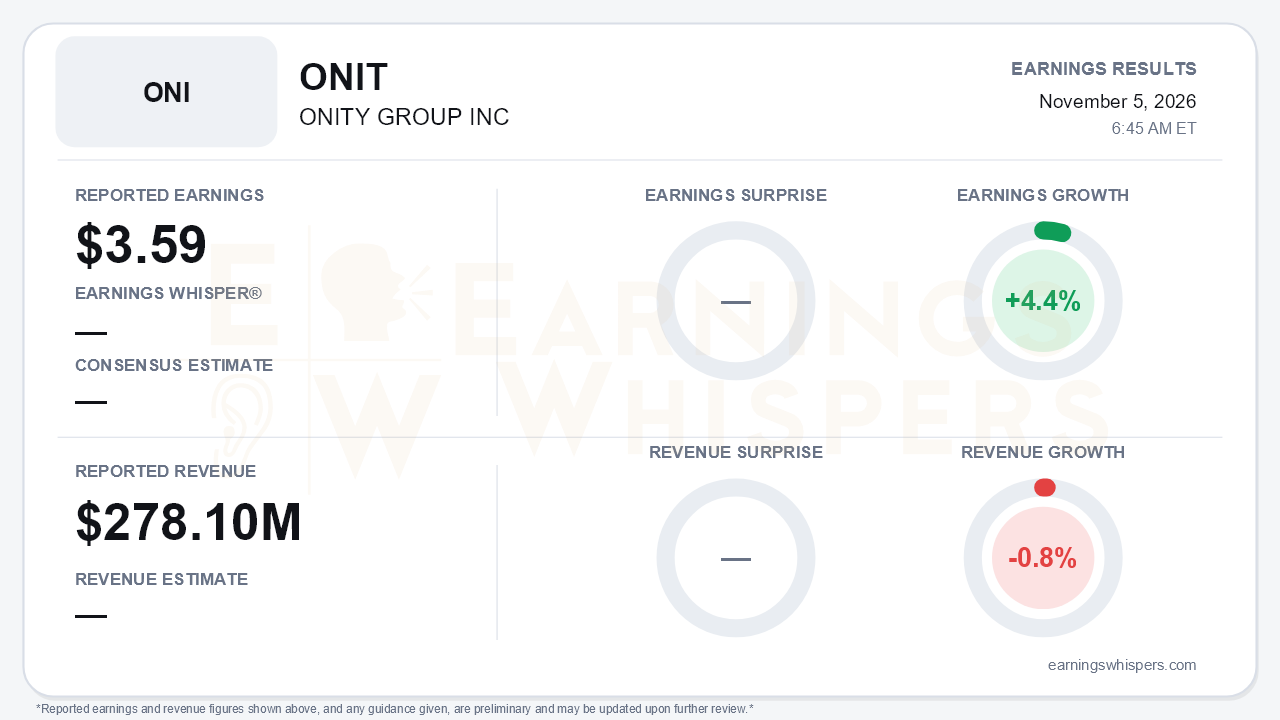
Onity Group (NYSE: ONIT) reported third-quarter earnings of $3.59 per share on an Earnings Whispers normalized basis, up 4.4% from a year ago, on revenue of $278.1 million, down 0.8%. No consensus estimate was available, so there is no surprise to measure. The more useful question is whether the quarter showed real progress, and the answer is mixed. The servicing business recovered sharply from a weak first half. Originations, the engine that carried the second quarter, is now losing momentum, and full-year guidance still points only to the low end of a range that has already been cut once.
The gap between the normalized EPS and GAAP results is wide and needs explaining. GAAP diluted EPS was $0.41, against a $1.53 loss in the second quarter and $2.03 a year ago. Net income to common holders was just $3.5 million, and GAAP ROE was 2%. Management attributed $11 million of pre-tax pressure, about $0.95 per share after tax, to market volatility in hedge costs and Agency loan sales compared with the second quarter. Adjusted pre-tax income more than doubled sequentially to $30 million, for an annualized adjusted ROE of 19%. That figure is still below the $34 million earned a year ago.
The quality of the improvement also deserves scrutiny. Beginning in the second quarter, Onity changed how it calculates MSR valuation adjustments, now excluding non-UPB collateral changes such as delinquency status and loan aging. Under the old method, second-quarter adjusted pre-tax income would have been a $5 million loss rather than a $14 million profit. The adjusted framework has therefore become more forgiving. Investors should weigh it alongside a GAAP line that remains thin.
The operating story beneath the numbers is a handoff from originations to servicing.
- **Servicing:** Adjusted pre-tax income reached $29 million, up more than 2.4x from the second quarter as runoff eased. This reverses the first-quarter runoff hit that produced the segment's first loss in 16 quarters.
- **Costs:** Operating expenses fell to $117.9 million from $139.0 million, driving a record 51% efficiency ratio. Part of the drop in compensation came from a $5 million LTIP benefit tied to stock-price changes.
- **Originations:** Adjusted pre-tax income slipped 15% to $24 million, and gain on loans held for sale fell to $26.6 million from $34.1 million a year ago.
- **Interest costs:** Interest expense climbed to $115.5 million from $82.9 million a year earlier, a structural drag that partly offsets higher interest income.
The forward picture contains real catalysts and real headwinds.
On the positive side:
- Subservicing additions of $53 billion year to date already exceed the roughly $50 billion full-year target.
- Business-purpose and commercial subservicing UPB growth accelerated to 46% year over year from 25% in the second quarter.
- The refinance recapture rate rose 18 points to 57%.
- Management outlined a targeted cut of more than $50 million (over 10%) in 2027 operating expenses from a roughly $500 million base.
- The company has retired about 6% of its shares and flagged possible repurchases of discounted bonds.
- Book value per share rose $12 year over year to $74.
Bears have legitimate ammunition, however:
- Consumer Direct locks fell about 23% from September to October.
- MBA data cited on the call show refinance applications down 60%, and the 2027 origination market is projected to be about 5% smaller.
- Total servicing UPB growth has slowed from 11% to 10% to 9% over the past three quarters.
- Management said MSR purchases will become more selective.
- Combined MSR and corporate debt-to-equity sits at the upper end of the target range.
That leverage constraint and the planned rightsizing of the originations platform suggest the next leg of growth will lean heavily on cost cuts and capital-light subservicing rather than balance-sheet expansion.
Market context is limited. Current price and sentiment readings were not available. Shares opened at $36.09 after the August report, slightly below the 200-day moving average of $37.66 and at roughly half of the then-reported book value. That suggests investors were already discounting the durability of earnings. The first-ever Investor Day on November 19 gives management a near-term venue to make its case on 2027 costs and capital returns.
The bottom line is that Onity proved its two businesses can offset each other, with servicing restoring profitability just as originations rolled over. The recovery is narrow, however. GAAP returns are minimal, the adjusted figures benefit from a friendlier methodology, servicing growth is decelerating, and 2026 adjusted ROE guidance sits at the low end of 10-15%. The credibility of the $50 million-plus cost program and subservicing momentum will matter more than this quarter's rebound.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-26 | |
| Oct-20 | |
| Sep-15 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-28 | |
| Jul-01 | |
| Jun-16 | |
| Jun-10 | |
| Jun-02 | |
| May-05 |
