NACCO Earnings Fall 19% On A Tax Swing, But The Contract Mining Ramp Lifts The 2026 Outlook As Solar Cleanup Lingers
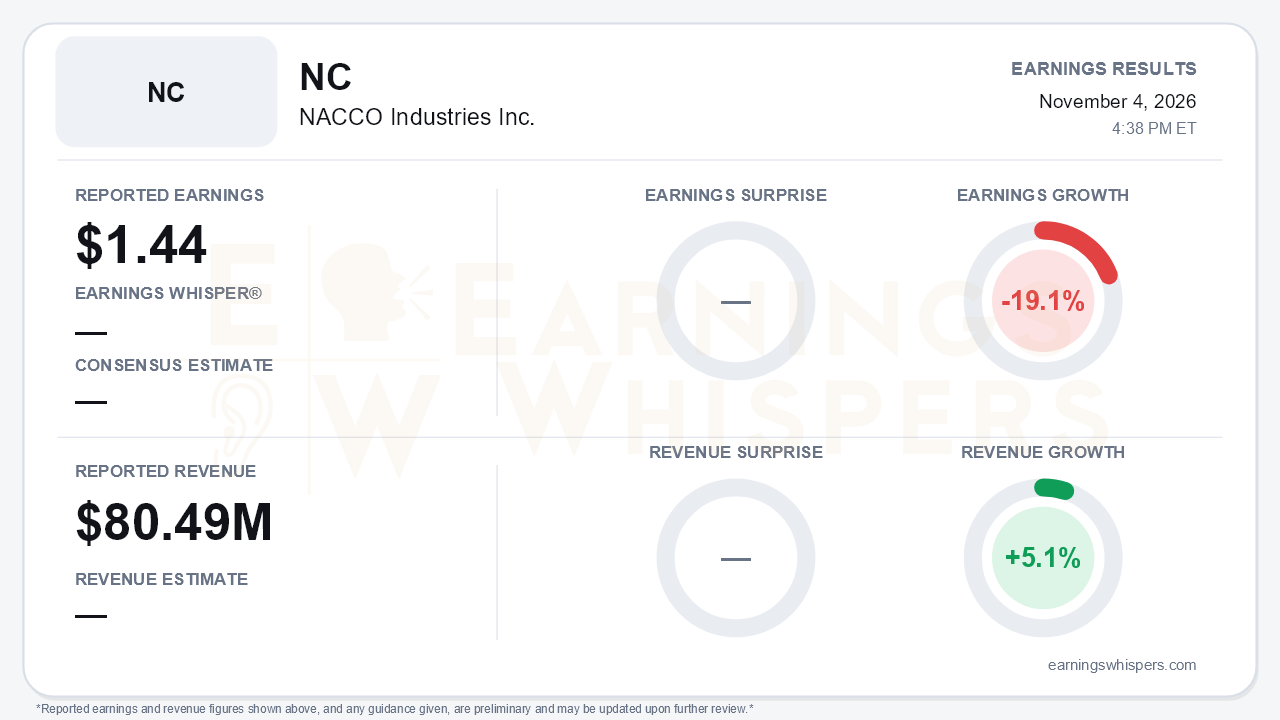
NACCO Industries (NYSE: NC) reported third-quarter earnings of $1.44 per share, down 19.1% from a year earlier, on revenue of $80.49 million, up 5.1%. The EPS decline reflects taxes rather than operations. Income before taxes more than doubled to $12.5 million from $6.0 million. Last year's quarter, however, carried a $7.3 million income tax benefit, while this quarter recorded a $1.6 million provision. That swing pushed net income down to $10.9 million from $13.3 million. The central tension is that the headline points down while nearly every operating line and the full-year outlook point up. Some of that improvement, though, came from sources investors should not extrapolate.
The quality of the beat in pre-tax profit deserves scrutiny. Consolidated Adjusted EBITDA rose 63% to $20.4 million, the best quarter of the year, up from $15.9 million in Q2 and $16.4 million in Q1. NACCO's definition does not strip out the $4.5 million gain from settling an excess pension funding liability, and that gain sits inside both pre-tax income and the EBITDA figure. Segment-level Adjusted EBITDA is a cleaner gauge. It rose to $15.6 million from $13.0 million, solid growth but well short of the 63% headline. On the other side of the ledger, operating profit of $9.3 million (+37%) absorbed $3.4 million of solar curtailment costs. Underlying operating performance was therefore better than the GAAP line shows, even though the EBITDA headline flatters it. Interest expense roughly doubled to $2.2 million, and debt edged up to $124.8 million from $120.1 million in Q2.
Contract Mining is where the business is visibly changing. Revenue excluding reimbursable costs jumped 75% to $22.2 million, an acceleration from the 34% growth posted in Q2. Operating profit climbed to $4.9 million from $1.9 million as the Palm Beach County dragline contract with the U.S. Army Corps of Engineers ramped. Management said a fourth dragline there is coming online within months. A new Arizona limestone quarry contract running more than a decade began operations in October. That growth is masking softness in the Florida limestone business, where customers are reducing inventory amid rate and election uncertainty.
Utility Coal Mining also improved:
- Operating profit rose to $6.6 million from $5.0 million on better contractual pricing at Mississippi Lignite.
- Inventory impairments were lower.
- Collections improved as the customer's plant ran more consistently.
Minerals and Royalties was the weak spot. Royalty revenue fell to $6.1 million from $9.3 million on lower natural gas volumes and prices, and operating profit held flat at $7.7 million only because equity earnings, largely from Eiger Resources, jumped to $4.3 million from $1.1 million. That flat result follows 29% growth in Q2. Management guided the segment below 2025 for Q4 and the full year, with further moderation in 2027.
Guidance is the most important development. After guiding full-year operating profit and net income below 2025 last quarter, management now expects operating profit to be comparable to 2025 despite roughly $15 million of year-to-date solar charges. It also now expects income before taxes and net income to rise. It went further and called for meaningful year-over-year improvement in 2027 operating profit, net income and consolidated EBITDA. Those gains are expected to be driven by full-year contributions from Palm Beach and Arizona, a profitable Mitigation Resources, and better results at Coteau and Falkirk offsetting the loss of Sabine reclamation income. Thacker Pass remains the longer-dated option. Lithium Americas is targeting Phase 1 mechanical completion in late 2027, and NACCO plans about $16 million of Sawtooth equipment spending in 2027 that the customer will reimburse over five years.
Bears have legitimate ammunition for the near term:
- Management warned that Q4 consolidated operating profit and Adjusted EBITDA could fall below the prior-year quarter, depending on the timing of solar costs.
- Utility Coal is guided lower in Q4 on weaker Mississippi Lignite demand, higher diesel costs and the end of Sabine reclamation fees on October 1.
- The solar exit is unresolved, with a $3.4 million PPA termination adding to Q4 revolver borrowings and further costs possible over a year or more.
- Cash flow before financing remains negative in 2026, with up to $56 million of capital spending planned for 2027.
Limited market data is available for this report. Shares opened at $46.42 after the August report, almost exactly at the current 200-day moving average of $46.66. Without a current price, it cannot be determined how the stock has traded since. Management's tone did shift noticeably, from the defensive, capital-discipline framing of Q2 to more confident language about newer contracts contributing.
The bottom line is that the 19.1% EPS decline understates the quarter. A tax-benefit comparison masked a sharp improvement in pre-tax earnings, led by an accelerating Contract Mining ramp and a recovering Utility Coal business. The headline EBITDA gain leaned on a one-time pension settlement gain, Minerals and Royalties is fading, and Q4 is guided soft with solar costs still trailing. Still, the upgraded 2026 outlook and an explicit 2027 growth call give the layering-of-contracts thesis more substance than it had a quarter ago. The test now is whether the new contracts can outrun the drag from royalties and solar in 2027.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Aug-20 | |
| Aug-19 | |
| Aug-12 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-29 | |
| May-18 | |
| May-14 | |
| May-05 | |
| May-05 |
