International Seaways Beats Handily, But The Story Is A Q4 Rate Spike That Dwarfs A Flat Q3
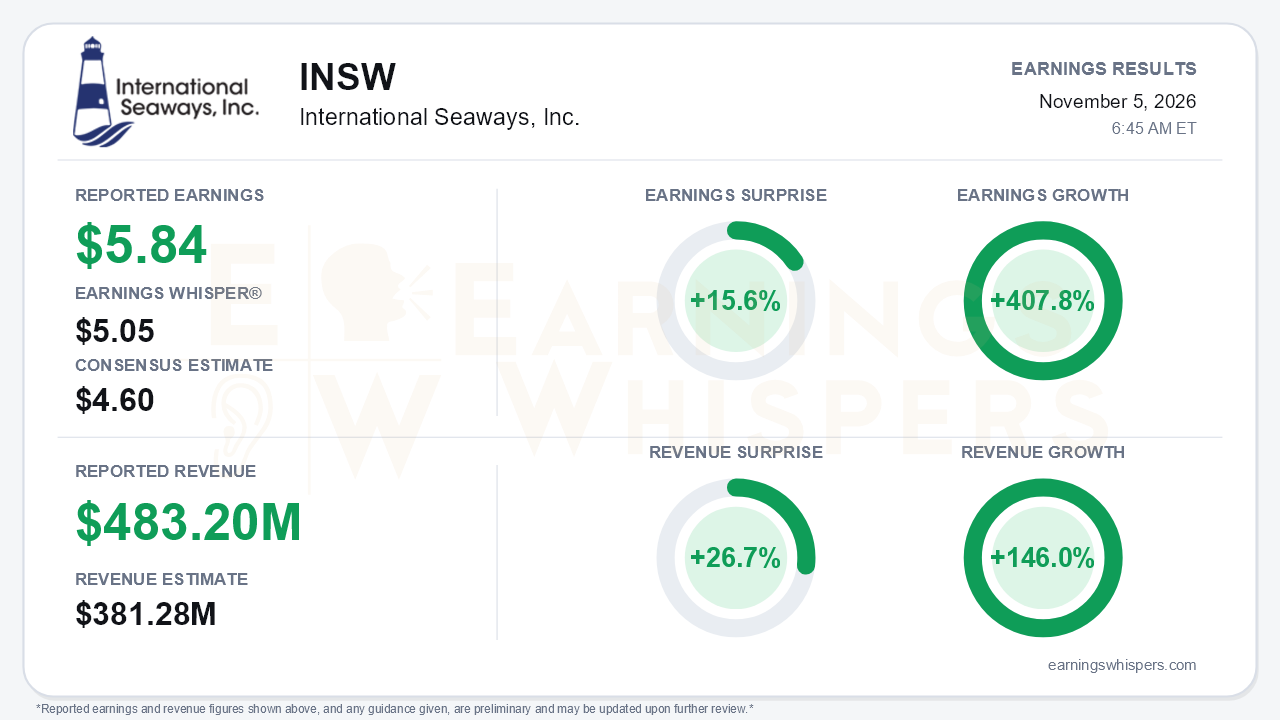
International Seaways delivered a decisive beat for the third quarter. Adjusted earnings of $5.84 per share topped the $4.60 consensus by 15.6% and cleared the $5.05 Earnings Whisper number. Revenue of $483.2 million beat the $381.28 million consensus by 26.7%. Year over year, earnings grew 407.8% and revenue grew 146.0%. GAAP net income was a record $344 million, or $6.90 per share, which includes a $53 million gain on the sale of a 2012-built Suezmax. The headline comparison is spectacular, but it is not the most important part of the report. Sequentially, Q3 was essentially a plateau. Management's fourth-quarter bookings point to a step change far larger than anything this quarter delivered. That is the central tension: a flat quarter sits underneath a record print, and the forward setup is extraordinary.
The quality of the beat deserves some scrutiny. Adjusted net income of $291 million slipped from $295 million in Q2. Free cash flow of $234 million fell from a record $261 million. Blended spot TCE realized dropped to about $67,700 per day from $79,000. What carried the quarter was crude, and specifically profit sharing on VLCC time charters. Crude TCE revenue hit a record $321 million versus $253 million in Q2, and roughly $77 million of that was VLCC profit share, up from $51 million. Fixed VLCC days earned an average of $315,258 per day, while spot VLCCs earned $154,597. That is a real earnings stream, but it is lumpy and directly tied to the rate spike. Revenue days also fell to 5,840 from 6,245 a year ago as the company continued culling older tonnage, so per-day economics did the heavy lifting.
The call is where the story improved materially. Management said fourth-quarter blended spot TCE is booked at more than $172,000 per day on over half of revenue days. That is more than double Q3's realized level and dwarfs the roughly $61,000 per day it had flagged for Q3 on the prior call. Management described VLCC rates as nearly four times the prior 35-year peak. MR rates are near $56,000 per day, up from about $35,000 cited last quarter, helped by strong U.S. Gulf refinery exports and Russian refinery outages. Management also framed an eventual resolution of the Middle East conflict as constructive rather than purely negative. Its argument is that OECD inventories are down roughly 250 million barrels to about 20-year lows, which would create a restocking need.
Capital allocation is shifting toward growth while preserving payouts. The Bruton acquisition adds four modern dual-fuel VLCCs, paid for primarily with about three million shares, and lowers fleet age below nine years. Two of those ships are already fixed at $95,000 and $107,000 per day. The dividend was held at a record $5.05, the fourth straight quarter with a payout of at least 85% of adjusted net income. The buyback authorization was raised to $100 million and extended through 2028. Liquidity stands near $964 million and net loan-to-value is below 6%, so the balance sheet can absorb the remaining $279 million of Bruton installments and the $244 million LR1 order. Bears still have legitimate ammunition:
- The share issuance dilutes existing holders.
- Working capital use rose to $64 million from $49 million.
- Management acknowledged a growing orderbook as high rates and easy financing spur newbuild ordering.
- Earnings at these levels depend heavily on a geopolitical disruption that could normalize.
The market has treated that dependence with caution. Shares spiked to a 52-week high of $126.27 on October 14, as rates surged late in the quarter. They have since given back much of that move and enter the report at $99.36, 21.3% below the peak. The stock is still up 6.6% since the open after the August report and sits about 15% above its 200-day moving average of $86.33. Investor sentiment remains negative but improved modestly, from -0.25 to -0.19. Expectations entering the print were skeptical rather than euphoric, even with Q4 bookings already strong. The Earnings Whispers trend signals lean positive on price, momentum and AVWAP, while sequential growth reads neutral. That neutral reading fits a Q3 that matched Q2 rather than surpassing it.
The bottom line is that International Seaways beat comfortably on a quarter that was more of a plateau than an acceleration. The release and call nonetheless reset the near-term earnings power sharply higher, with Q4 spot bookings above $172,000 per day and a reaffirmed 85%-plus payout implying outsized distributions. The pullback from October's high shows investors are already weighing how long conflict-driven rates can last against a swelling orderbook and new share issuance. That durability question, not the size of the Q3 beat, is what will define the stock from here.
Read our earnings preview for International Seaways, Inc.: https://www.earningswhispers.com/article/INSW/22120
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 11 hours | |
| 16 hours | |
| 18 hours | |
| Oct-28 | |
| Oct-21 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Sep-28 | |
| Sep-10 | |
| Sep-03 | |
| Aug-14 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 |
