FRP Holdings Posts Its Best Leasing Quarter Since 2021, But A Third Straight Outlook Cut And Tightening Liquidity Overshadow It
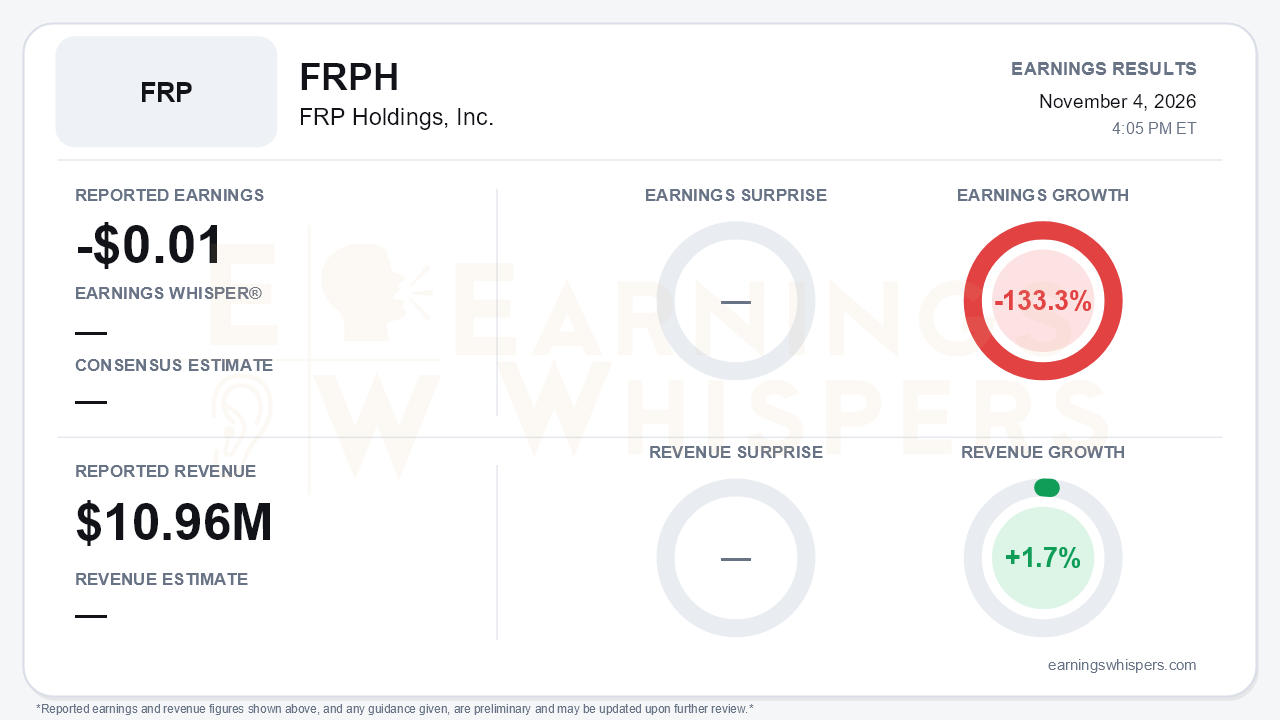
FRP Holdings swung to a small loss in the third quarter, reporting -$0.01 per share against a $0.03 profit a year earlier. That is a 133.3% year-over-year decline in earnings, on revenue that edged up 1.7% to $10.96 million. No consensus estimate was available, so the quarter has to be judged on its own trajectory. That trajectory is the central tension. Operationally, FRP finally delivered the industrial leasing inflection investors have been waiting for. Financially, the bridge to that payoff got longer, more expensive and more dependent on a shrinking cash pile.
The headline revenue gain deserves scrutiny. Growth came almost entirely from mining royalties, which rose 9.5% on higher volume (+6.9%) and pricing (+3.0%), plus $49,000 of Altman management fees. Lease revenue fell 3%. Pro rata NOI declined 5% to $9.0 million, and mining is now carrying the portfolio. Mining NOI of $4.1 million (+10%) essentially matched the multifamily segment's $4.0 million, which fell 12%. Industrial and commercial NOI dropped 28% to $651,000, reflecting the expired Vulcan land lease and Maryland vacancies. Below the property level, the drags were structural rather than one-off. G&A rose $1.0 million, or 43%, on post-Altman personnel, legal and integration costs. Investment income fell $1.0 million as cash was deployed into construction and lending-venture balances ran off. Consolidated operating expenses fell 29%, but that largely reflects the absence of last year's Altman acquisition costs in the development segment, not a leaner cost base.
The multifamily weakness is concentrated and worsening in Washington, DC. Bryant Street alone accounted for more than half of the segment's NOI decline, as occupancy slipped 240 basis points to 91.0%. Dock 79's NOI fell despite higher occupancy because concessions and operating costs rose. On the call, management indicated DC trade-outs were running around -10%, and DC renewal increases averaged just 2.5%. Greenville remained steady above 95% occupancy. Portfolio occupancy of 93.0%, flat year over year, masks the margin erosion. Segment NOI margin fell from 54% to 49%.
The genuine positive is industrial leasing. FRP signed about 127,000 square feet in the quarter, versus roughly 20,700 in Q2, including 61,000 square feet of new leases and renewals at +4.1%. Management said this activity represents about $1.1 million of new annual base rent. Maryland same-store occupancy ended at 74.3%, up from 70.6% cited last quarter. Lakeland and Davie are slated for Q4 delivery and Camp Lake for Q1 2027. Together with Chelsea, that is roughly 1 million square feet that management estimates can generate about $12 million of stabilized pro rata NOI and $7 million of FFO. Management also introduced a broader framing of roughly $50 million of NOI and $20 million of FFO potential at stabilization. Those are targets, not forecasts, and their timing depends entirely on lease-up and rent commencement.
Bears have legitimate ammunition on the near-term outlook. The 2026 pro rata NOI forecast was cut for the third consecutive call to about $35.8 million, down from $37.1-$37.7 million in Q4, about $37 million in Q1 and $36.2 million in Q2. That compares with $37.9 million in 2025. FFO is guided to about $15.6 million versus $22.1 million last year. Management warned of roughly $7.1 million of 2027 FFO drag as buildings deliver empty and interest and operating costs stop being capitalized, with only about $2.5 million of identified offset. Camp Lake also slipped from 2026 into 2027.
The balance sheet is where the setup has changed most:
- **Cash:** Cash, including restricted cash, fell to $73.2 million from about $101 million in Q2, and $12 million is drawn on the credit line.
- **Debt:** Notes payable rose to $231.7 million from $192.6 million at year-end, while projects under construction more than doubled to $112.8 million.
- **Upcoming obligations:** Ahead lie roughly $166 million of FRP-share debt maturities within 24 months, a $20.5 million Opportunity Zone tax bill in 2027 and about $57 million of 2027-28 capex.
- **Capital return:** Management again rejected buybacks until roughly 2029, despite shareholder pressure, though insiders have bought nearly 500,000 shares this year.
The call's tone was noticeably more defensive, with the CEO asking for patience. Market context is thin. Shares opened at $22.54 after the August report, almost exactly at the current 200-day moving average of $22.35. No current price or sentiment reading was available to gauge the reaction.
The bottom line is that FRP's quarter validated the leasing thesis while weakening the financial path to it. The 127,000 square feet of signed leases is real progress. But a third straight guidance cut, a deeper 2027 earnings trough, DC multifamily deterioration and a rapidly declining cash cushion mean investors are being asked to fund a longer wait. The investment case now hinges on converting leasing momentum into rent commencement before refinancing and tax obligations force harder choices.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Oct-22 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-22 | |
| May-13 | |
| May-12 | |
| May-12 | |
| May-06 | |
| Apr-11 | |
| Apr-10 | |
| Apr-10 |
