DTE Energy Beats On Vantage Strength, Then Sells Vantage To Fund A Higher-Growth, Lower-Base Utility Plan
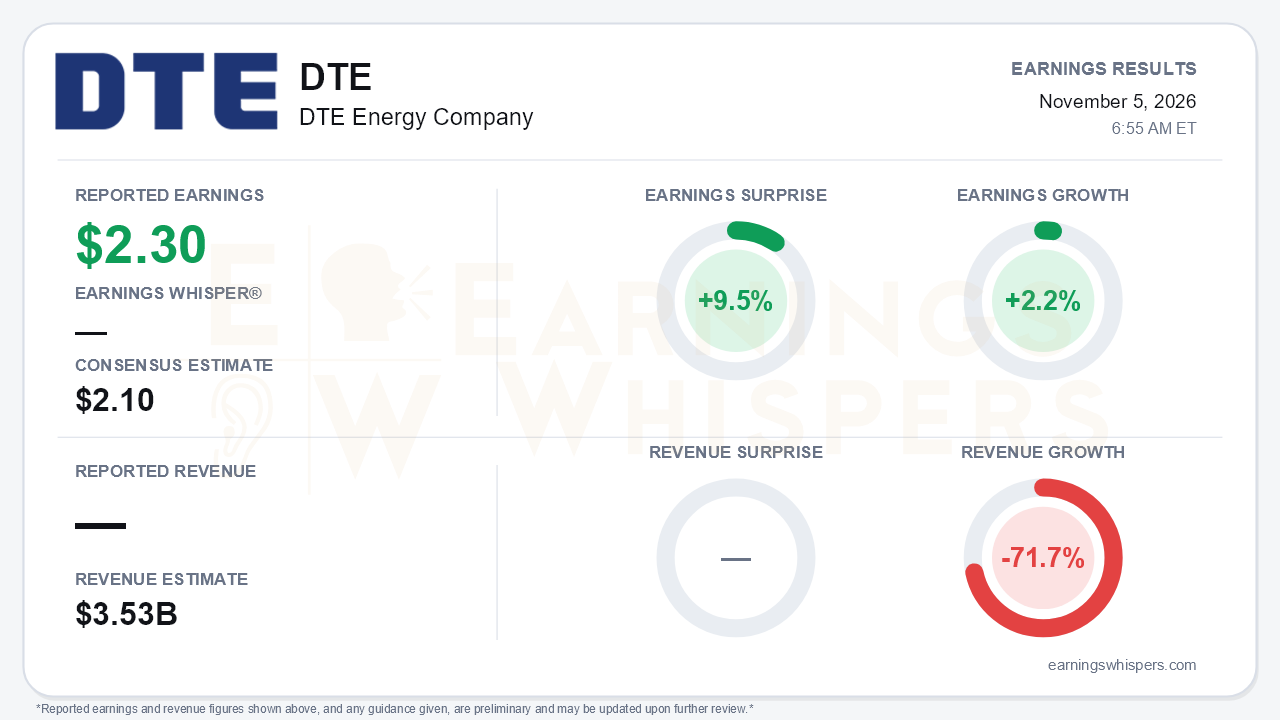
DTE Energy delivered third-quarter operating earnings of $2.30 per share, beating the $2.10 consensus by 9.5% and growing 2.2% from a year ago. On a GAAP basis, reported EPS rose to $2.25 from $2.01. The beat, however, was not the story of the quarter. DTE agreed to sell its non-utility DTE Vantage business for about $3 billion. It also raised its five-year utility capital plan to roughly $44 billion and lifted its long-term operating EPS growth target to more than 9%. That growth comes off a reset 2027 baseline that is flat with 2026. That is the central tension: a faster growth rate starting from a lower launch point.
The quality of the beat deserves scrutiny, because the business being sold produced it. DTE Electric operating earnings fell to $468 million ($2.24 per share) from $541 million ($2.60) a year earlier. That $73 million decline reflected tax timing, storm costs and costs tied to rate base growth. DTE Vantage, meanwhile, nearly tripled to $110 million ($0.53) from $41 million ($0.19), lifted by renewable natural gas and investment tax credit benefits. Energy Trading added $34 million versus $23 million, and the seasonal gas loss narrowed. Strip out Vantage and the core utility went backward this quarter. Through nine months, operating EPS of $5.58 still trails last year's $5.71. Management nonetheless reaffirmed 2026 operating EPS guidance of $7.59 to $7.73 and said the year is tracking toward the high end of its 6-8% growth range. Vantage is expected to finish above its own guidance.
The call recast DTE as a pure-play regulated utility with a much bigger investment runway. The Michigan Public Service Commission approved the 1-gigawatt Google data center contract in October. That deal had been pending through the first half and is now in the plan, adding roughly $5 billion of renewables. Combined with Oracle's 1.4 gigawatts, DTE now has 2.4 gigawatts contracted. The broader pipeline remains 5-6 gigawatts, with about 2 gigawatts in advanced talks, and management still targets another deal by year-end. Capex rose from $36.5 billion to about $44 billion, including roughly $39 billion at DTE Electric. Management now expects EPS growth well above 9% in 2028-29 and at least 9% in 2030-31, and the 2027 dividend will rise 7%. The tone shifted noticeably, from describing "upside to plan" to a "once-in-a-generation" opportunity and a "higher growth premium utility."
Bears have legitimate ammunition in the cost of that pivot. The 2027 pro forma baseline of $7.59 to $7.73 sits about $0.50 below the roughly $8.20 implied by the prior trajectory, reflecting lost Vantage and RNG earnings. Management does not expect to catch back up to the old path until around 2029. Average annual equity needs roughly double to about $1 billion for 2027-2031, from $500-600 million. That increase comes even with about $2 billion of parent debt being retired and the 2026 forward equity settlement deferred into 2027. There is also an internal inconsistency worth flagging. The 2027 baseline assumes the Vantage deal closes by year-end 2026, yet the release says closing is expected in the first half of 2027 and still requires regulatory approvals. Regulatory execution adds further risk:
- An electric rate case order is due in February 2027, with more than 30 intervenors making settlement unlikely.
- The stay-out mechanism and large-load tariff still need approval.
- A new governor and legislature make multi-year rate plan legislation unlikely before late 2027.
The market setup is more complicated than the surprise implies. Investor sentiment entered the report notably more negative, sliding to -0.36 from -0.10 after the prior release. Shares were at $137.53 heading into the print, down 6.3% since the open following the July report and 2.4% below the 200-day moving average. The stock set a 52-week low of $119.68 on September 29 and has since rebounded nearly 15%, yet it remains about 9% below its post-July high. Most Earnings Whispers trend readings are positive, with sequential growth and momentum improving, but the price trend itself remains negative. Investors have been bidding the stock off its lows without yet re-rating it.
The bottom line is that DTE used a Vantage-driven beat as the backdrop to sell Vantage and reset its earnings path. The trade is a flat 2027 and heavier equity issuance in exchange for a credible >9% growth story backed by contracted data center load and a nearly $10 billion capex increase. Whether that earns the premium multiple management is seeking depends on a closing timeline, a contentious rate case and an unsigned third data center deal. Skeptical investors will want proof on those points before fully crediting the higher growth rate.
Read our earnings preview for DTE Energy Company: https://www.earningswhispers.com/article/DTE/22085
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 11 hours | |
| 11 hours | |
| 11 hours | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-22 | |
| Oct-15 | |
| Oct-01 | |
| Oct-01 | |
| Sep-21 | |
| Aug-19 | |
| Aug-19 | |
| Aug-16 |
