Carriage Services Misses Badly And Cuts Guidance Again As Cemetery Sales Unravel, Offsetting A Real Funeral Rebound
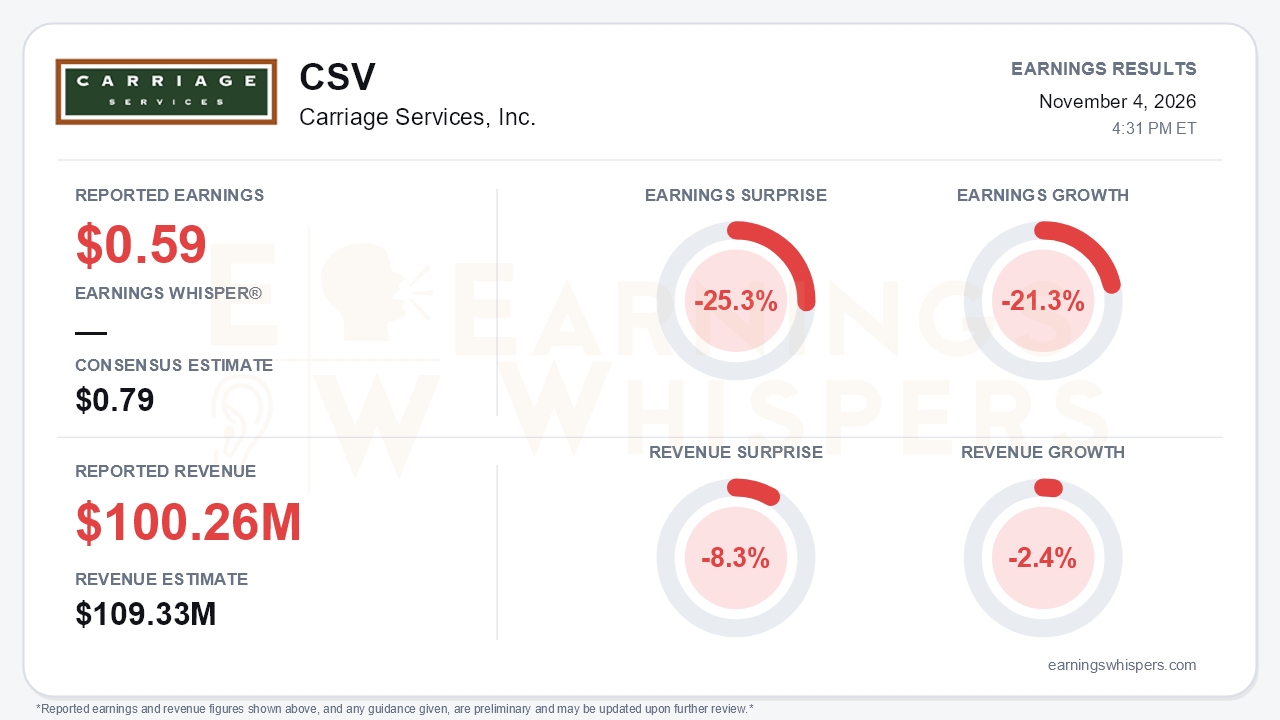
Carriage Services (NYSE: CSV) delivered a third quarter in which the improving parts of the business were overwhelmed by the deteriorating ones. Adjusted EPS of $0.59 fell 25.3% short of the $0.79 consensus and declined 21.3% from a year ago. Revenue of $100.26 million missed expectations by 8.3% and slipped 2.4% year over year. Management also cut full-year guidance for the second consecutive quarter. Funeral volumes finally turned positive, which is the development bulls had been waiting for. Cemetery preneed sales, however, broke down at the same moment, and that is the central tension of the report.
The headline GAAP figures flatter the quarter. GAAP diluted EPS rose to $0.56 from $0.41, and net income grew 35.2%. That improvement came almost entirely from a $6.9 million favorable swing in divestiture and impairment charges against a weak prior-year base. Excluding that swing, gross profit fell $5.0 million and adjusted consolidated EBITDA dropped to $27.7 million from $33.0 million. Adjusted EBITDA margin compressed to 27.6% from 32.1% a year ago and 32.3% in the second quarter. Roughly $2.5 million of that damage came from trust taxes tied to the sale of MLP investments held in the company's trusts, which cut financial revenue to $6.2 million from $9.0 million. That charge is discrete, but it accounts for only part of the shortfall.
The larger problem is cemetery execution. Comparable cemetery revenue fell 7.8% to $32.5 million, and comparable preneed sales production declined 4.8%. A year ago the same line grew 21.4%, and it was still growing in the first half of 2026. Consolidated interment rights sold dropped 7.3%. Cemetery comparable EBITDA margin collapsed to 41.8% from 48.3%. Management said the weakness was concentrated in California contracts under $20,000, but it also acknowledged broader lapses in recruiting, training and lead management, with sales headcount below last year. The tone shifted noticeably. Last quarter management talked about operating leverage and a foundation "stronger than ever." This quarter it conceded that results "fell short" and "have not met our standards." The company has rolled out a sales performance dashboard and AI-powered tools and is targeting a full cemetery recovery by the first quarter of 2027. That target should be treated as an aspiration until the data shows it.
Funeral is the genuine bright spot. Same-store funeral contracts rose 2.3%, a sharp reversal from declines of 5.8% in the first quarter and 3.5% in the second. Average revenue per contract grew 1.9%, and comparable funeral revenue climbed 3.6% to $56.8 million. Insurance-funded preneed funeral contracts sold rose 7.0%. Profit did not keep pace with the volume, though. Funeral comparable EBITDA barely moved to $20.4 million, and margin slipped to 35.9% from 36.9% on salary and benefit pressure that management expects to persist into the fourth quarter. Management guided fourth-quarter funeral contracts flat to up 1%, which points to stabilization rather than acceleration.
The revised outlook calls for:
- revenue of $415 million to $420 million, down from $435 million to $445 million;
- adjusted EBITDA of $125 million to $130 million, down from $135 million to $140 million;
- adjusted EPS of $2.90 to $3.05, down from $3.35 to $3.55.
Against $2.23 of adjusted EPS through nine months, the guidance implies a meaningful fourth-quarter step-up from the third quarter's $0.59. The forward-looking catalysts are real. More than $14 million of annual acquisition revenue across five deals is under contract or letter of intent, and a new $300 million credit facility adds $50 million of capacity. Even so, deal closings have slipped to December and early 2027, which limits their 2026 contribution. Year-end leverage guidance also rose to 4.0x–4.1x, and the Trinity ERP rollout is under third-party review following the CIO's departure.
The market had already been skeptical. Earnings Whispers investor sentiment was negative heading into the report and weakened modestly, from -0.30 to -0.36. Shares at $35.98 are down 5.3% since the open following the August report and sit about 10% below the 200-day moving average of $39.99. The stock has been treated as a show-me story, and this quarter offered bears legitimate ammunition rather than relief.
The bottom line is that Carriage's funeral turnaround appears to be taking hold, but it arrived just as the cemetery business stumbled badly. A second consecutive guidance cut undercuts management's credibility on near-term forecasting. Over the next two quarters, investors will need evidence of three things: cemetery sales actually recovering, acquisitions closing on the revised schedule, and funeral margins stabilizing. Until then, a promising M&A pipeline is not enough to offset an earnings base that keeps moving lower.
Read our earnings preview for Carriage Services, Inc.: https://www.earningswhispers.com/article/CSV/21814
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-23 | |
| Oct-15 | |
| Sep-30 | |
| Sep-30 | |
| Aug-05 | |
| Aug-05 | |
| Aug-03 | |
| Jul-22 | |
| Jul-16 | |
| May-27 | |
| May-06 |
