CrossAmerica Misses Badly As Pump Prices Erode Fuel Volumes; Fuel-Price-Driven Revenue Beat And Merchandise Gains Can't Offset A Stalled Second Half
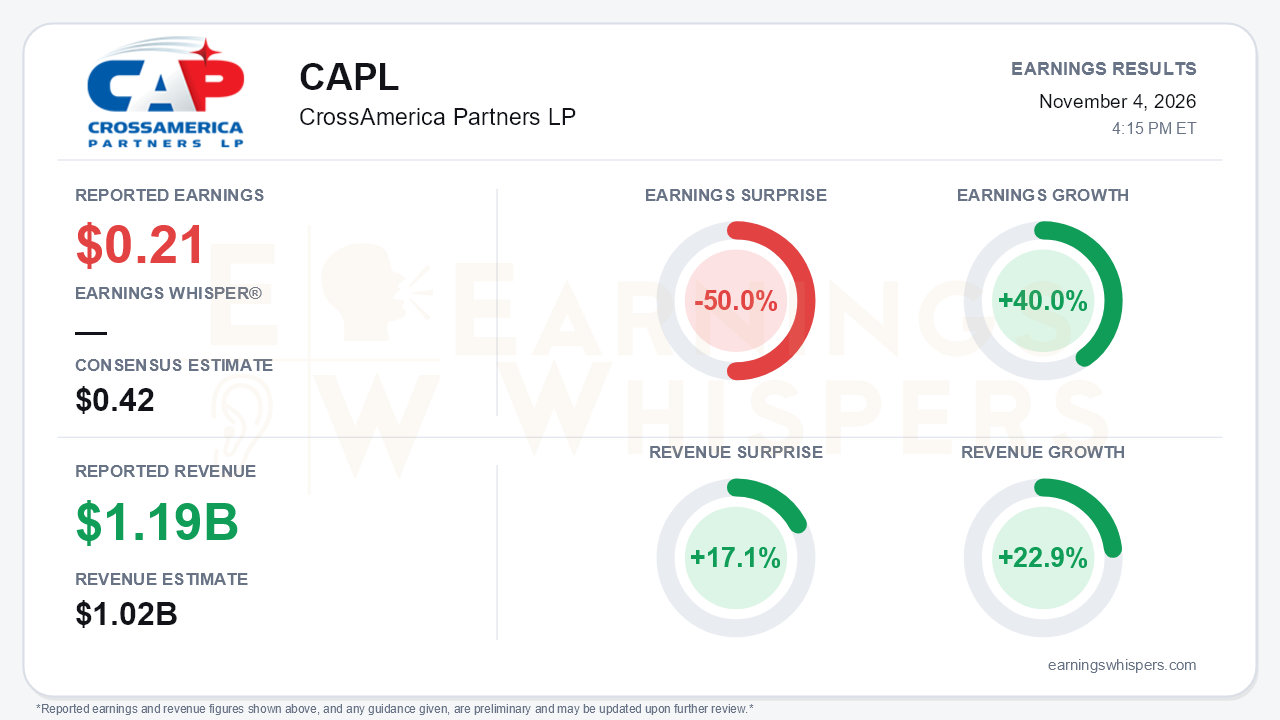
CrossAmerica Partners (NYSE: CAPL) reported third-quarter earnings of $0.21 per unit, 50.0% below the $0.42 consensus. Revenue of $1.195 billion beat the $1.02 billion estimate by 17.1% and grew 22.9% year over year. The revenue figure is misleading. The top line rose because fuel prices rose, not because the business grew. Gallons fell sharply in both segments, consolidated gross profit slipped to $101.1 million from $104.8 million, and Adjusted EBITDA declined 6% to $38.7 million. That is the central tension: a partnership that spent the first half posting strong double-digit EBITDA growth saw that momentum stall once elevated pump prices began suppressing demand.
The growth figures need context. Earnings Whispers' normalized data show earnings up 40.0% year over year. The press release, however, reports GAAP net income of $8.8 million, or $0.21 per unit, versus $13.6 million, or $0.34, a year ago. Investors should recognize that the two comparison bases differ.
On the release's own numbers, the quarter weakened. Lower real estate gains explain part of the net income decline: $2.4 million of net gains versus $7.4 million last year. The operating story is weaker too. Distributable Cash Flow fell to $21.8 million from $27.8 million. Quarterly distribution coverage dropped to 1.09x from 1.39x as sustaining capex rose to $5.3 million from $1.9 million and current taxes increased. The $0.5250 distribution remains covered, and trailing twelve-month coverage improved to 1.32x from 1.00x. The cushion this quarter, though, was thin.
The call showed a clear split between what management controls and what it does not.
**Controllable levers held up:**
- Merchandise gross margin reached 30.3%, up 140 basis points year over year and higher than 29.7% in the first quarter.
- Merchandise gross profit grew 2% despite 7% fewer company-operated stores.
- Total operating expenses fell 2%, and wholesale opex dropped 16%.
**Fuel, the core profit driver, weakened:**
- Retail same-store gallons fell 7%, with company-operated sites trailing industry trends.
- Wholesale same-store volume worsened to -7% from -2% in the first quarter.
- Retail fuel margin of 40.4 cents per gallon was up 5% year over year but well below the 43.7 cents earned in the first quarter and 44.9 cents in the fourth quarter of 2025.
Same-store inside sales slipped to -1% from +2% in the first quarter. Same-store retail opex turned up about 1% after running -3% earlier in the year. Management's tone shifted accordingly, from being "positioned for continued success" last quarter to describing a business "challenged by fuel volume."
The forward picture offers modest encouragement but plenty of risk. Management said September volumes improved materially versus earlier in the quarter. October was softer than September but still ahead of the third-quarter average. That suggests the worst of the demand pressure may have peaked, though it depends on gasoline prices, which neared $4.50 per gallon in late September. Wholesale margin held at 8.8 cents, helped by larger payment-terms discounts on elevated fuel costs, a benefit that would fade if prices fall.
The balance sheet is moving the wrong way. Leverage rose to 3.72x, up from 3.57x in the second quarter and 3.35x in the first. Management reaffirmed a target of roughly 4x, and the credit facility runs to 2031 with about $237 million of availability. Even so, the asset-sale pipeline is thinner than in 2025, so real estate gains are unlikely to cushion results as they did last year. No formal guidance was offered.
Investors grew more cautious heading into the report. Earnings Whispers sentiment fell from roughly neutral at -0.03 to -0.19, a meaningful but not extreme move into negative territory. The units have lost 5.5% since opening at $21.44 after the August report and now trade at $20.27, about 7.9% below the 200-day moving average of $22.01. The trend readings are mixed: momentum is positive, while sequential growth and AVWAP remain negative. That fits a quarter in which year-to-date strength is colliding with deteriorating recent results.
The bottom line is that CrossAmerica's third quarter exposed how dependent the partnership remains on fuel volume and margin. Merchandise execution and cost discipline are real, but they are too small to offset a 7%-plus same-store gallon decline and fuel margins normalizing from first-half peaks. Year-to-date Adjusted EBITDA (+22%) and DCF (+30%) still look healthy, and the distribution is covered on a trailing basis. However, quarterly coverage, leverage and management's tone all moved in the wrong direction. The improvement in late-quarter volumes is the key variable to watch. Until fuel demand stabilizes, the burden of proof has shifted back to the bulls.
Read our earnings preview for CrossAmerica Partners LP: https://www.earningswhispers.com/article/CAPL/22014
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Oct-28 | |
| Oct-21 | |
| Oct-16 | |
| Sep-03 | |
| Aug-05 | |
| Aug-05 | |
| Aug-03 | |
| Jul-23 | |
| Jul-21 | |
| Jul-17 | |
| Jun-15 | |
| May-22 |
