PENN Beats Big As Retail Margins Widen And Interactive Nears Profitability, But Same-Store Growth Is Slowing
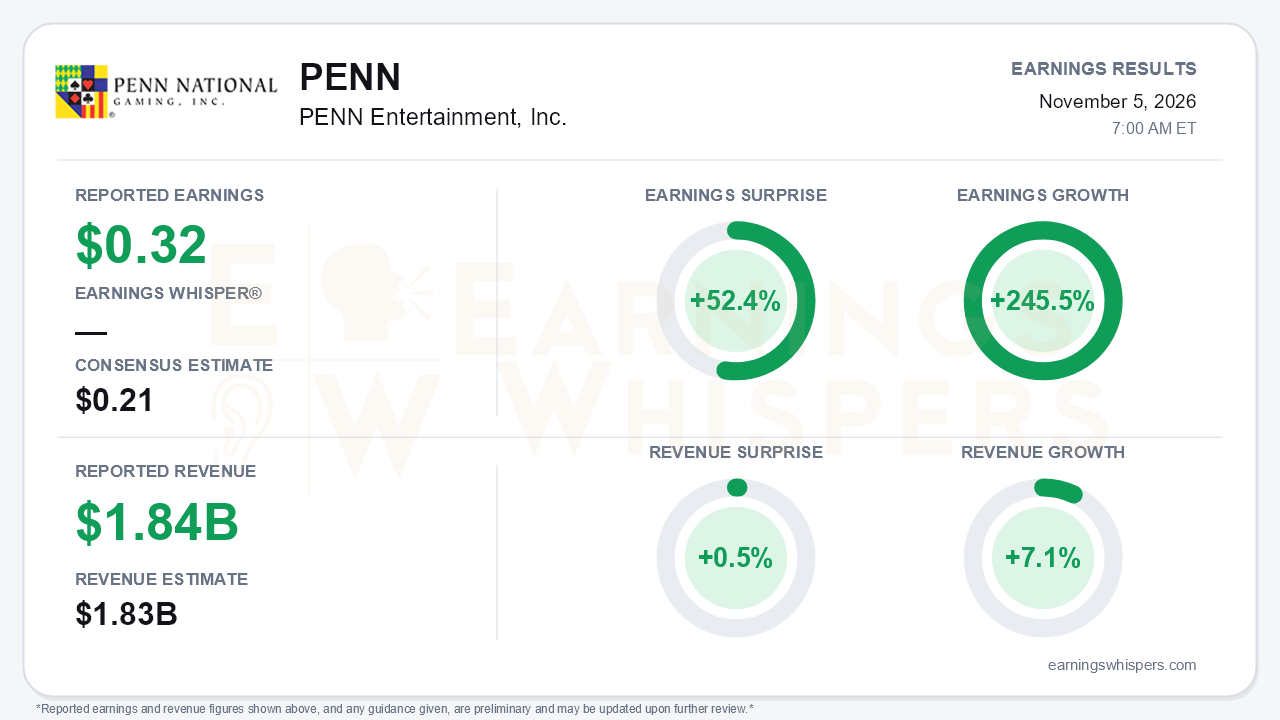
PENN Entertainment delivered a clean third-quarter beat. Adjusted EPS of $0.32 topped the $0.21 consensus by 52.4% and swung from a $0.22 adjusted loss a year ago, which works out to 245.5% earnings growth. Revenue rose 7.1% to $1.84 billion, only 0.5% above consensus. GAAP diluted EPS was $0.24 versus a $6.03 loss, although the prior-year figure was distorted by an $825 million Interactive impairment. The more useful comparison is Consolidated Adjusted EBITDA, which climbed to $284.0 million from $194.9 million. That jump came from three sources: wider retail margins, a much smaller digital loss, and leaner corporate costs. The central takeaway is that PENN is now converting modest top-line growth into outsized profit growth. The question is how much organic momentum sits underneath that leverage.
The quality of the beat holds up better than most, but it deserves scrutiny. Retail revenue reached a third-quarter record of $1.5 billion. Segment Adjusted EBITDAR rose to $501.8 million, and margin expanded to 33.7%. That margin gain was 84 basis points year over year, an acceleration from 55 basis points in the second quarter and the third straight quarter of improvement. Flow-through was roughly 50%. Much of the growth, however, is coming from new assets rather than the existing base. Midwest revenue jumped about 15% on the Aurora and Joliet projects, and food, beverage, hotel and other revenue rose roughly 20%. Per-share results also got help from a weighted diluted share count that fell to 135.4 million from 143.5 million. Same-store retail revenue growth slowed to about 1% from about 2% in the second quarter, even as same-store EBITDA grew about 5%. That is the central tension: margin discipline and development returns are carrying a portfolio whose organic growth is cooling.
Interactive showed similar quality-of-revenue nuances. The segment loss narrowed to $18.3 million from $76.6 million, and that figure includes start-up spending in Alberta. Reported revenue of $348.4 million, however, included $191.4 million of tax gross-up versus $139.5 million last year. Net of that gross-up, digital revenue was essentially flat at roughly $157 million. That fits with management's acknowledgment of continued declines in U.S. online sports betting and integrated iCasino volumes, while standalone Hollywood iCasino, Ontario and Alberta drive the growth. Management guided fourth-quarter Interactive EBITDA to +$18.7 million and said October was already profitable. Its stance on profitability in 2027, "you can take that to the bank," was firmer than its tone earlier in the year. Full-year Interactive guidance stayed at a $20 million loss, and the skin-tax gross-up outlook was cut by about $25 million.
Guidance moved up for a third consecutive quarter, though only modestly:
- Full-year retail revenue guidance is now $5.89 billion.
- Retail EBITDA guidance is now $1.973 billion, about $10 million above the prior midpoint.
- The implied fourth quarter shows a sequential slowdown, with management citing weather and construction disruption at Council Bluffs.
The catalyst list has also grown more concrete:
- The Pennsylvania skill-game shutdown helped make October the state's strongest year-over-year gaming month of 2026, with VGT route revenue up more than 30%.
- PENN owns two of Texas's three Class 1 tracks, which gives it optionality if the state legalizes gaming.
- M Resort's 2027 group pace is up 55%.
- Hollywood New Orleans has been added to the pipeline for 2029.
Bears have legitimate ammunition on taxes. Colorado has proposed raising brick-and-mortar gaming tax rates, and the Illinois properties are moving into higher tax tiers. Other pressures include Las Vegas softness that compressed West margins and prediction markets inflating sports-betting acquisition costs.
The balance sheet may be the most underappreciated change. Traditional net debt fell to $1.76 billion from $2.22 billion at year-end, and traditional net leverage dropped to 2.3x from 4.5x. Liquidity stands at $2.0 billion. Third-quarter capex fell to $59.2 million from $172.7 million, and full-year project capex guidance was trimmed to $170 million. That frees cash ahead of a $400 million note maturity in January 2027. Management said buybacks are explicitly on the board's 2027 agenda, citing a roughly 20% free-cash-flow yield.
Investor sentiment improved meaningfully into the report, moving from modestly negative (-0.14) to modestly positive (+0.22). Price action was less forgiving. At $17.44, shares were down 12.8% from the open after the August report. They sat 15.3% below the inter-earnings high of $20.59, which was set the day after that release. The stock did rebound 23.4% from its October 1 low of $14.13 and closed about 3.6% above its 200-day moving average. The trend readings are mixed: momentum is positive, while price and AVWAP trends remain negative.
The bottom line is that PENN's quarter showed a business shifting from a cash-burning digital story to a margin-and-deleveraging story. The evidence includes record retail profitability, an Interactive segment on the verge of breakeven, sharply lower leverage and buybacks coming into view. The offsets are real: same-store growth of about 1%, flat digital revenue net of gross-up, rising tax risk and a soft implied fourth quarter. Even so, the stock entered the report well below its post-August peak, and the call gave investors firmer profitability commitments than they had three months ago.
Read our earnings preview for PENN Entertainment, Inc.: https://www.earningswhispers.com/article/PENN/22164
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 6 hours | |
| 6 hours | |
| Oct-30 | |
| Oct-28 | |
| Oct-15 | |
| Oct-14 | |
| Oct-09 | |
| Oct-06 | |
| Oct-06 | |
| Oct-05 | |
| Oct-02 | |
| Sep-24 | |
| Sep-18 | |
| Sep-10 |
