Phibro Matches EPS On A Revenue Beat, But Core Animal Health Slows To 3% And Guidance Stays Put
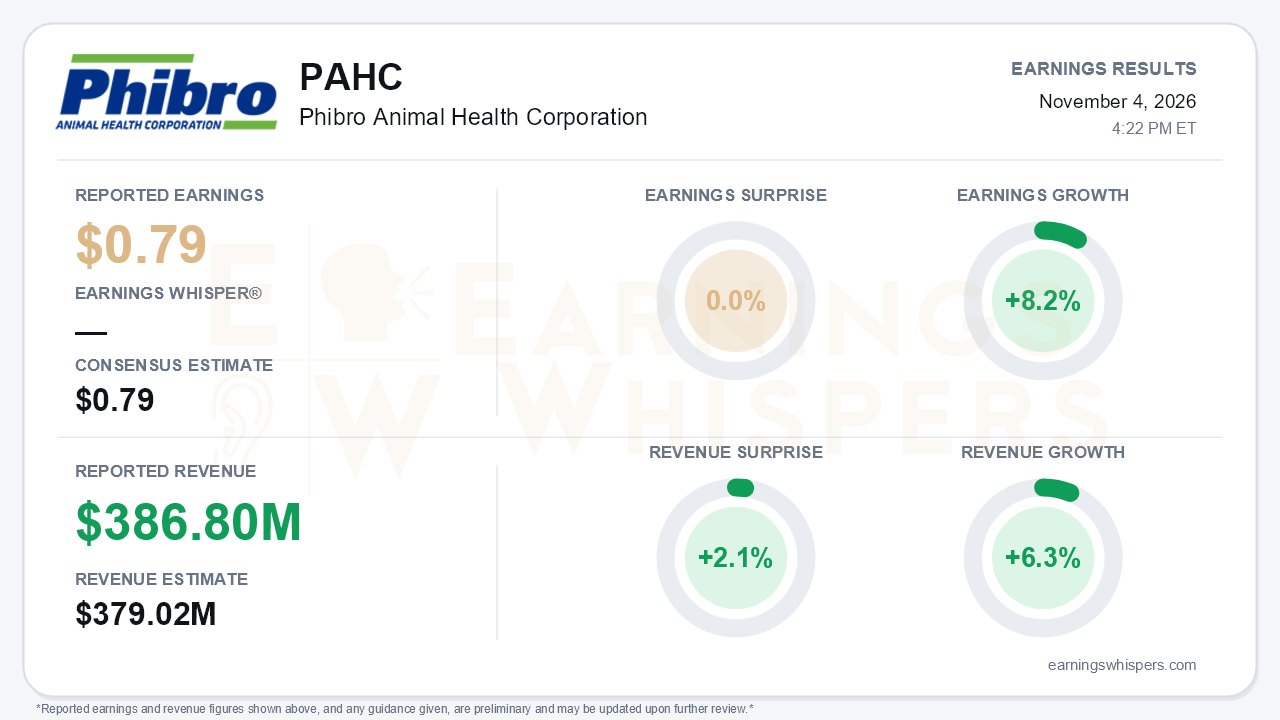
Phibro Animal Health (NASDAQ: PAHC) opened fiscal 2027 with adjusted EPS of $0.79, exactly matching consensus, on revenue of $386.8 million that topped the $379.02 million estimate by 2.1%. Earnings grew 8.2% year over year and revenue grew 6.3%. Management said results beat its internal plan. The quality of that outperformance deserves scrutiny. The upside came mainly from the lower-margin Mineral Nutrition and Performance Products segments and from costs that slipped into the second quarter. The core Animal Health franchise, which drives the investment case, grew just 3%, and its adjusted EBITDA declined. That is the central tension: a clean headline sitting on top of a decelerating core.
The segment detail makes the point. Mineral Nutrition sales rose 17% to $73.6 million on higher demand and pricing for zinc oxide, copper and trace minerals. Performance Products grew 16% to $20.2 million, helped by copper-based and fluoride demand and by IEEPA tariff recoveries. Together they added $2.8 million of the $2.4 million increase in total adjusted EBITDA. Animal Health EBITDA fell $1.0 million, and its segment margin slipped to 25.2% from 26.4% as employee-related SG&A rose $5.9 million. On a GAAP basis, diluted EPS rose 11% to $0.72, but operating income fell 3% and operating margin compressed to 12.8% from 14.1%. The prior-year quarter did include $3.8 million of insurance proceeds that flattered that comparison. The GAAP bottom line was lifted by below-the-line items: a swing from $2.9 million of foreign-currency losses to a $0.4 million gain, lower interest expense aided by interest on tariff recoveries, and a lower tax rate. Adjusted gross margin held flat at 34.0%, so pricing offset higher input and distribution costs but did not expand margins.
The call marked a noticeable tonal shift from the upbeat protein backdrop of the fiscal 2026 calls. Animal Health growth has decelerated from 26% in fiscal Q2 2026 (when results were aided by the Zoetis MFA acquisition) to 13% in Q3 and now 3%. Within that, MFAs grew 6% on North American and Asian demand, the acquired Zoetis portfolio and ethanol processing aids, despite a $5.2 million drop in Brazil virginiamycin sales. Nutritional specialties and vaccines each fell 2%, compared with full-year fiscal 2026 growth of 9% and 14%. Management tied those declines to poultry destocking in North America and Brazil. It now describes producer profitability as likely to stay soft near term. Poultry is squeezed by U.S. chicken supply running ahead of demand, swine margins are also pressured, feedlots face negative closeouts through February, and dairy is near breakeven. That is a sharp departure from last quarter's framing of record animal values.
The forward picture contains real offsets. Corn has dropped roughly $1 per bushel, easing customer feed costs into 2027. Management projects Mexican cattle imports rising toward about 1 million head next year. The second quarter laps roughly $13 million of prior-year product returns, an easy comparison. However, management warned that costs shifted out of Q1 will make Q2 EBITDA growth trail revenue growth. Brazil remains a binary item: the virginiamycin transition period ended in October without approval and without renewed regulator contact. Guidance excludes further Brazil sales, so an approval would be pure upside, but the timing is unclear. Cash conversion is the most actionable improvement. Trailing free cash flow rose to $22 million from $10 million last quarter. Even so, the CEO said he is not satisfied with inventory levels and made working capital a top priority, with net leverage at 2.6x.
Guidance requires a note of caution. Earnings Whispers' normalized data characterizes the outlook as an earnings guidance raise in line with estimates. The company's release and call, however, describe fiscal 2027 guidance as maintained: sales of $1.55-1.60 billion, adjusted EBITDA of $258-268 million and adjusted EPS of $3.41-3.59. The ranges are unchanged from August. That steadiness contrasts with the raises Phibro delivered at fiscal 2026's Q2 and Q3, and it suggests management is absorbing the Q1 upside rather than extrapolating it.
Investors appear more forgiving than the call's tone. Earnings Whispers sentiment moved from roughly neutral (-0.02) to modestly positive (0.247). The stock, however, has gone nowhere: at $39.43 it is up just 0.1% since the open following the August report and sits 4.4% below its 200-day moving average of $41.23. Price action remains neutral, though the AVWAP reading is positive, a sign that buyers since the last report are roughly even rather than under water.
The bottom line is that Phibro delivered a respectable quarter on paper, but the beat was built on minerals, performance products, cost timing and below-the-line gains, while core Animal Health slowed sharply and management turned more cautious on producer economics. Improving cash flow, lower feed costs and optional Brazil upside give bulls something to hold, yet bears have legitimate ammunition until nutritional specialties and vaccines stabilize.
Read our earnings preview for Phibro Animal Health Corporation: https://www.earningswhispers.com/article/PAHC/22430
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Oct-28 | |
| Oct-28 | |
| Sep-09 | |
| Aug-27 | |
| Aug-26 | |
| Aug-26 | |
| Aug-19 | |
| Jul-28 | |
| May-21 | |
| May-07 | |
| May-06 |
