Marex Beats On Volatility-Fueled Market Making As Growth Accelerates, But Prime And Solutions Show The Limits Of The Record
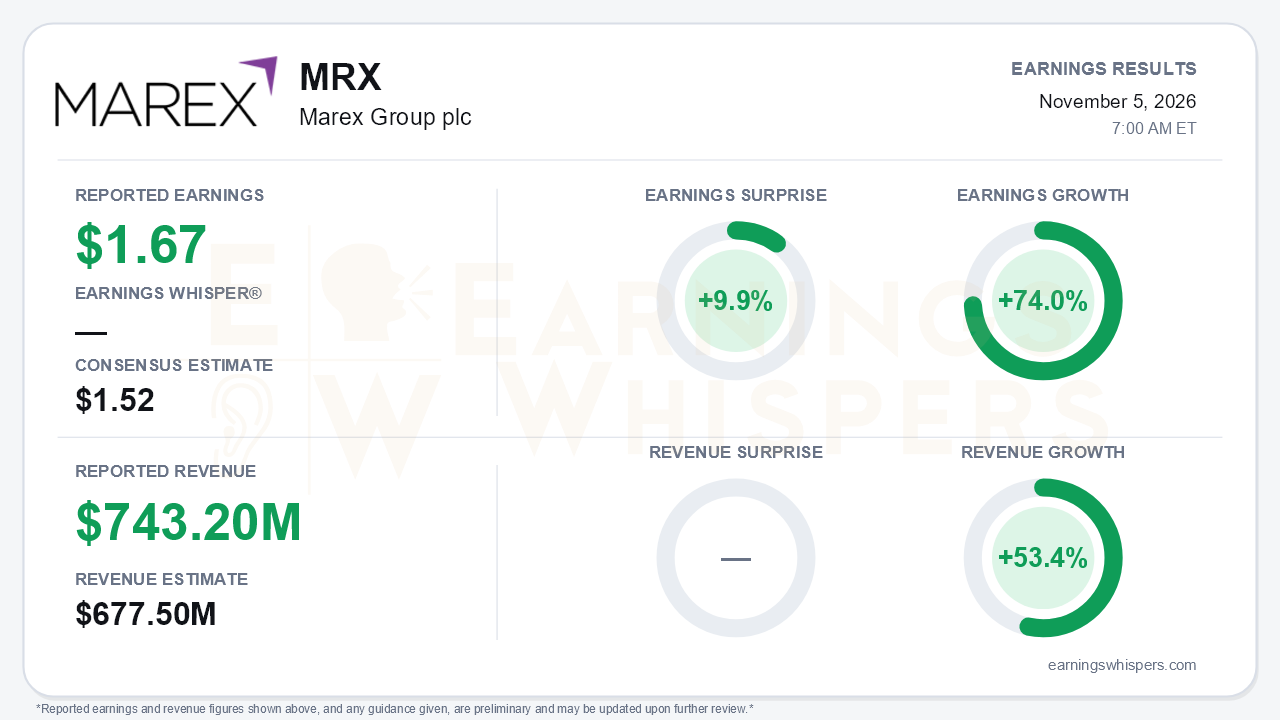
Marex Group (NASDAQ: MRX) delivered its third consecutive record quarter and an acceleration that turnaround-style skeptics would struggle to dismiss. Adjusted earnings of $1.67 per share beat the $1.52 consensus by 9.9% and grew 74.0% year over year. Revenue of $743.2 million topped the $677.5 million estimate by 9.7% and rose 53.4%. Both growth rates ran ahead of the year-to-date pace, which was 47% for revenue and 63% for adjusted profit before tax. Adjusted PBT reached $176.1 million, up 75%, and margin expanded 300 basis points to 23.7%. The central tension is that the quarter's acceleration leaned heavily on a favorable trading environment in metals. Two of the businesses investors had treated as structural growth engines, Prime and Solutions, stepped back sequentially.
The quality of the beat deserves scrutiny. Market Making revenue more than tripled to $150.8 million and segment PBT rose from $7.0 million to $57.9 million. Metals alone jumped from $23.6 million to $91.0 million on elevated prices and volatility in precious and base metals. Acquisitions also helped: Levmet, Webb Traders and Winterflood broadened the franchise, and Levmet and Webb Traders together contributed low-teens millions of PBT. The release itself concedes a comparatively low prior-year base. Agency and Execution was the more durable story. Segment margin widened to 31.8% from 25.6% as FX revenue more than doubled to $59.1 million on the scaling of Hamilton Court, while Energy revenue slipped 4%. Below the operating line, the picture was less clean:
- Net interest income fell to $35.7 million from $38.5 million despite average balances of $25.2 billion versus $18.6 billion, because funding costs from the April senior notes and structured note growth outran the benefit of higher balances.
- Stage 1 credit provisions rose to $6.7 million. Management attributed this to portfolio growth rather than credit deterioration.
- On an IFRS basis, diluted EPS was $1.45, up from $0.92.
- Sequentially, adjusted basic EPS edged up only to $1.75 from $1.72, partly because hybrid coupons attributable to note holders tripled after the June issuance.
The call showed where momentum is building and where it is fading:
- **Prime:** Revenue slipped to $115 million from a record $120 million in Q2 after the AI-stock repricing hit leveraged ETF balances. Management signaled Prime growth will moderate because on-balance-sheet expansion consumes capital.
- **Solutions:** PBT fell to $14 million at a 23% margin, down from $25 million at 35% in Q2 and $33 million in Q1, as equity volatility eased.
- **Clearing:** Average balances dipped to $18.7 billion from $19.1 billion in Q2, though revenue rose to $170 million and clearing net interest income grew 35% to $83 million.
- **Liquidity:** Headroom fell to $1.3 billion from $1.8 billion in Q2.
- **Client franchise:** Clients generating $5 million-plus rose to 82 from 77 last quarter and 49 in 2025. Treasury cross-margining doubled to six live clients, with 15 in the pipeline.
The forward-looking narrative improved more than the quarter's mix did. Management lifted its long-term adjusted PBT margin aspiration to roughly 30%, up from a 'mid-20s over three years' framing in Q1. It also said it was 'very comfortable' with 10–20% adjusted PBT growth in 2027 off a record 2026 base. That range, however, includes Bright Point and full-year acquisition effects. In Q2, management had suggested growth at or above the top end of that range on a historical basis, so the new framing is arguably more measured than the headline confidence implies. The M&A pipeline is now quantified at four deals with agreed commercial terms, mostly clearing- and prime-leaning in Asia and Latin America, plus four to six further out, backed by roughly $300 million of deployable capital. Newer optionality includes a live Kalshi FCM with six institutional clients and an elevated compute-futures initiative, although regulatory approval for compute futures appears to be slipping. Management said October is tracking at the year's average.
Investor expectations rose sharply heading into the report. Earnings Whispers sentiment climbed to 0.75 from 0.49, a meaningful shift toward optimism. Price action has been choppier. Shares hit a 52-week high of $79.11 on September 8, then slid to $62.46 on October 30, essentially back to the $62.60 opening after the August report. The stock rebounded to $70.34 ahead of this release. That leaves it up 12.4% since the prior report, 22.4% above its 200-day moving average, and still 11.1% below the September peak. Trend readings are mixed, with momentum positive but AVWAP negative, consistent with a stock that has been repeatedly re-tested after a strong run.
The bottom line is that Marex produced an accelerating, broad-based beat and raised its long-term ambitions, while the M&A and new-product pipeline remains a credible growth driver. Bears still have legitimate ammunition. The quarter's upside leaned on metals volatility, Prime is now capital-constrained, Solutions earnings have more than halved since Q1, and net interest income keeps eroding under heavier funding costs. With sentiment already elevated, the burden now shifts to showing that the 30% margin aspiration and the 2027 growth target can hold if trading conditions normalize.
Read our earnings preview for Marex Group plc: https://www.earningswhispers.com/article/MRX/22146
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 11 hours | |
| 16 hours | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-22 |
Financial Exchanges CME, Cboe, ICE, Nasdaq Benefiting From Sector Rotation Out Of AI Stocks
MRX
Investor's Business Daily
|
| Oct-13 | |
| Oct-13 | |
| Oct-09 | |
| Oct-07 | |
| Aug-14 |
IPO Stock Of The Week: Marex Attempts Breakout With Rally To Record Highs
MRX
Investor's Business Daily
|
| Aug-12 | |
| Aug-10 | |
| Aug-10 | |
| Aug-05 |
