MetLife Posts Record Quarter On A Variable Investment Income Surge, But The Beat Leans Heavily On Private-Market Marks
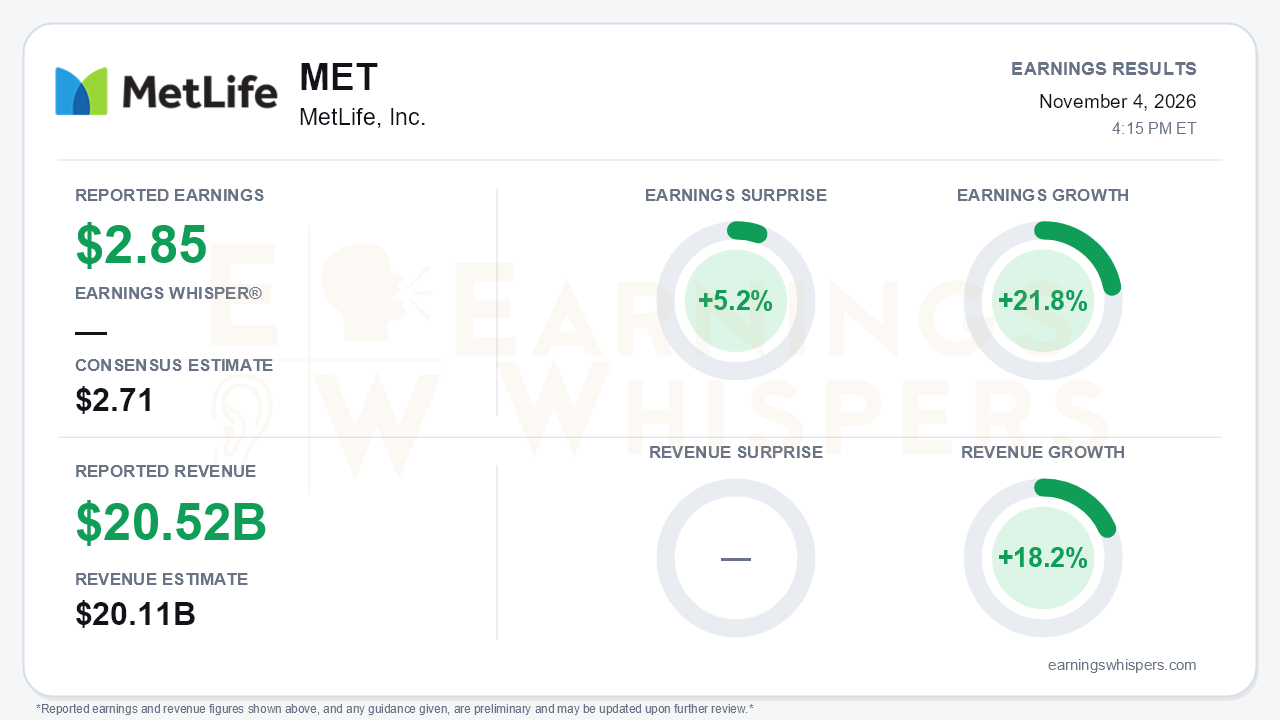
MetLife delivered the highest adjusted EPS quarter in its history, earning $2.85 per share excluding notable items. That beat the $2.71 consensus by 5.2% and rose 21.8% from a year ago. Revenue of $20.522 billion topped the $20.11 billion estimate by 2.0% and grew 18.2%. GAAP net income nearly tripled to $2.4 billion, or $3.67 per share. The central takeaway is that the core franchise is growing on a broad front, but this particular quarter was powered disproportionately by variable investment income (VII), and management itself assumes that tailwind fades in the fourth quarter.
The quality of the beat deserves scrutiny. VII jumped to $720 million, up 49% year over year and roughly $320 million above the company's ~$400 million quarterly run rate. Private equity returned 4.2% and venture capital topped 8%, a sharp swing from $231 million in VII in the second quarter. The headline revenue figure is also flattered by accounting. Net derivative gains of $698 million replaced a $929 million loss a year earlier, while adjusted premiums, fees and other revenues excluding pension risk transfer grew a more measured 8%. GAAP results were similarly lifted by derivative gains tied to higher rates. Per-share growth also benefited from buybacks, with diluted shares down about 4% year over year. Reported book value per share fell 22% on unrealized investment losses, although adjusted book value rose 5% to $59.41. None of this undermines the quarter, but it means the 22% EPS growth overstates the underlying earnings trajectory.
Still, the operating story is better than a pure mark-to-market sugar high. Every one of the six segments grew top-line revenue. Group Benefits earned $523 million, up 14%, on favorable underwriting, and year-to-date sales accelerated to 12% from 9% at midyear. RIS earnings excluding notables rose 12%, compared with 2% in the second quarter. Retained liabilities grew 7%, well above the 3-5% outlook. EMEA was a standout, with earnings up 30% to $114 million against a $90-100 million run rate, and the region gained a new multi-market embedded insurance partnership with Revolut. MIM earnings improved for a third straight quarter. The direct expense ratio of 11.9% stayed inside the 12.1% target.
Management leaned into the strength and nudged several targets higher:
- Full-year VII is now expected to exceed the ~$1.6 billion guide.
- RIS full-year earnings are seen slightly above the midpoint of $1.6-1.8 billion.
- Japan's solvency ratio came in at 192%, above the 170-190% range.
- U.S. statutory capital rose 3% sequentially to about $17 billion.
- Adjusted ROE of 19.6% sits well above the 15-17% target.
The tone was more emphatic, with the CEO describing the company as "firing on all cylinders."
Bears have legitimate ammunition, however:
- Asia sales fell 6% in constant currency, a sharp turn from gains of 17% in the second quarter and 22% in the first.
- Latin America earnings excluding notables dropped 5% in constant currency on a negative encaje return.
- MIM assets under management slipped $25 billion sequentially on public fixed income outflows, and MIM remains guided toward the low end of its range.
- U.S. pension risk transfer volumes are light after a record 2025, which management frames as timing.
- The core RIS spread eased to 99 basis points.
- In Group, disability severity and mental/nervous claims ticked up, and the favorable 79.5% life mortality ratio is expected to normalize seasonally.
Taken together, the fourth quarter faces a tougher setup on VII, mortality and potentially disability.
Investor expectations shifted meaningfully into the report. Earnings Whispers sentiment swung from -0.23 after the prior report to +0.10, moving from skeptical to modestly positive. Shares were up 4.4% from the opening price following the August report, trading at $102.89, nearly 20% above the 200-day moving average of $86.01. The Earnings Whispers trend signals are largely positive, with sequential growth, momentum and AVWAP all constructive while price trend is neutral. This is a stock that entered the print with improved expectations rather than deep pessimism. As a result, the bar for upside surprise was higher than the consensus numbers alone suggest.
The bottom line is that MetLife produced a genuinely strong quarter with broad volume growth, rising guidance in RIS and VII, ample capital and returns comfortably above target. A meaningful share of the record, however, came from private-market marks that management does not expect to repeat at this pace. The New Frontier execution story looks credible. Even so, decelerating Asia sales, softer Latin America results, MIM outflows and normalizing group claims are the details that will determine whether the stock's run above its long-term average reflects durable compounding or a peak-VII quarter.
Read our earnings preview for MetLife, Inc.: https://www.earningswhispers.com/article/MET/21872
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-29 | |
| Oct-27 | |
| Oct-25 | |
| Oct-23 | |
| Oct-16 | |
| Oct-16 | |
| Oct-14 | |
| Oct-14 | |
| Oct-07 | |
| Oct-07 | |
| Oct-06 |
