Kinetik's EPS Miss Hides A Stronger Quarter: Record Volumes, High-End Guidance And A Faster Growth Cadence
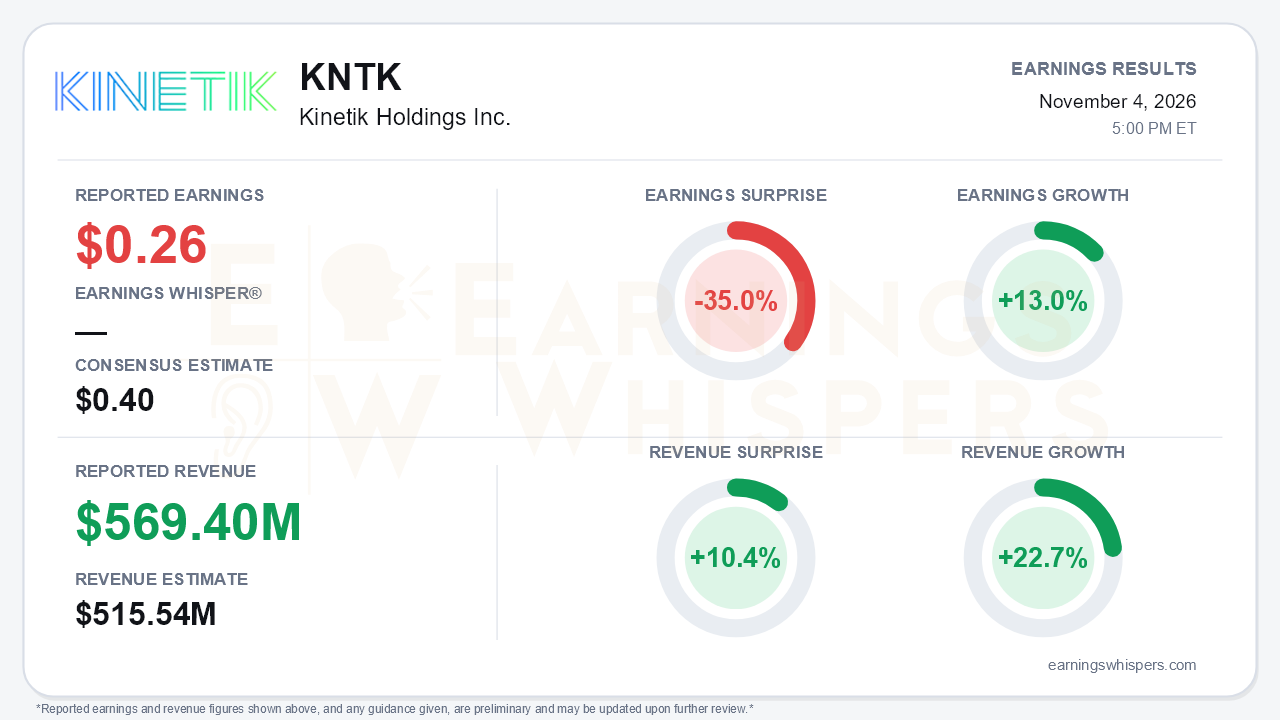
Kinetik Holdings (NYSE: KNTK) missed badly on the headline. It reported third-quarter earnings of $0.26 per share against a $0.40 consensus, a 35.0% shortfall. Even so, earnings still grew 13.0% year over year. Revenue of $569.4 million beat the $515.54 million consensus by 10.4% and rose 22.7%. The miss is real, but it is a poor guide to how the business performed. Adjusted EBITDA was $278.1 million, up from $242.6 million a year ago and above the $260-270 million second-half quarterly cadence management had laid out earlier in the year. That is the central tension: the EPS line disappointed, while the cash-generating engine had its best quarter yet.
The quality of the miss deserves scrutiny, and much of it traces to non-cash and non-operating items. GAAP results absorbed a $27.8 million unrealized commodity hedging loss, versus $6.5 million a year earlier. Litigation costs, share-based compensation and higher depreciation also weighed on the line. Equity earnings from pipeline affiliates fell to $47.2 million from $58.3 million after the EPIC Crude divestiture. The share count also rose sharply, with diluted weighted shares of 81.0 million versus 62.4 million. Still, GAAP net income including noncontrolling interest more than tripled to $50.9 million from $15.5 million.
The revenue beat needs context. Product revenue jumped to $447.9 million from $357.6 million, but cost of sales rose in tandem, so the top-line upside overstates margin capture. The cash metrics are more telling:
- Distributable cash flow rose to $213.7 million from $158.5 million.
- Free cash flow climbed to $87.5 million from $13.9 million.
- Dividend coverage reached 1.61x.
Beneath the headline, the operating story improved on nearly every front management controls. Processed volumes hit a record 1.94 Bcf/d and October averaged 2.14 Bcf/d, leaving the roughly 2.2 Bcf/d fourth-quarter target within reach. Waha-related shut-ins fell to about 25 MMcf/d from roughly 170 MMcf/d earlier in the year. Midstream Logistics EBITDA rose 34% to $203.6 million.
Management now expects full-year Adjusted EBITDA at the high end of guidance. The release cites a $1.04-$1.1 billion range, while the call analysis references $950 million-$1.05 billion. Investors should anchor to the release figure, but the direction is unambiguous.
The tone shift was notable. Earlier in the year management spoke of reestablishing credibility; it now says progress is exceeding expectations and calls 2027 a "step change." Coverage at 1.6x triggered guidance for a January dividend increase at the high end of 3-5%. Leverage improved to 3.7x, with a target of 3.5x or below by year-end.
The forward catalysts are substantial:
- **KL2 upsized.** Kings Landing II grows by more than 25% to 380 MMcf/d at an unchanged ~$260 million cost.
- **Faster expansion cadence.** Management reframed growth as a 400 MMcf/d plant every 18-24 months and is already procuring long-lead equipment for the next one. It says this cadence doubles its volume growth expectations.
- **New dedications.** More than 30,000 gross acres were added, including Woodford-prospective acreage and a minimum volume commitment.
- **NGL recontracting.** Expiring Lone Star NGL contracts should deliver a 2027 uplift more than 50% above the prior ~$40 million annual illustration.
Bears still have legitimate ammunition:
- **Capacity bridge.** The system is expected to be full by end-2027, ahead of KL2's mid-2028 start, so ECCC's phase 1 expansion must bridge the gap.
- **Fading marketing gains.** Gulf Coast marketing contributions are shrinking as Waha normalizes and will be lower in 2027.
- **Weaker pipeline segment.** Pipeline Transportation EBITDA fell 18% to $78.5 million.
- **Capex timing.** The roughly 5% capex underrun partly reflects spending deferred into 2027, and growth capex stays elevated.
- **Commodity exposure.** Management concedes that activity beyond a largely "baked" 2027 is sensitive to crude prices.
- **Execution.** Kinetik has come up short in a competitive M&A market.
Investor sentiment remained mildly positive but softened slightly, slipping from 0.09 to 0.064 ahead of the report. That is a modest cooling, not a capitulation. The stock has moved little since the August report, up 2.3% from the post-report open to $51.17. Shares sit about 4.6% above the 200-day moving average of $48.92. Price and AVWAP trend readings are positive while momentum is neutral. That fits a stock grinding higher rather than one pricing in the improved 2027 outlook.
The bottom line is that Kinetik's EPS miss is largely an artifact of hedging marks, lost equity income and a larger share count. The operating quarter was its strongest yet: record volumes, rising cash flow, falling leverage and a materially more ambitious growth cadence. The debate now shifts from whether the turnaround is real to whether Kinetik can execute through a capacity crunch in late 2027 while marketing tailwinds fade.
Read our earnings preview for Kinetik Holdings Inc.: https://www.earningswhispers.com/article/KNTK/21858
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 11 hours | |
| Nov-04 | |
| Oct-27 | |
| Oct-13 | |
| Oct-13 | |
| Oct-02 | |
| Sep-09 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-29 | |
| Jul-29 | |
| Jul-14 | |
| Jun-24 | |
| May-20 |
