BGC's In-Line EPS Undersells A Reaccelerating Quarter As FMX Gains Traction, But Investor Sentiment Sours
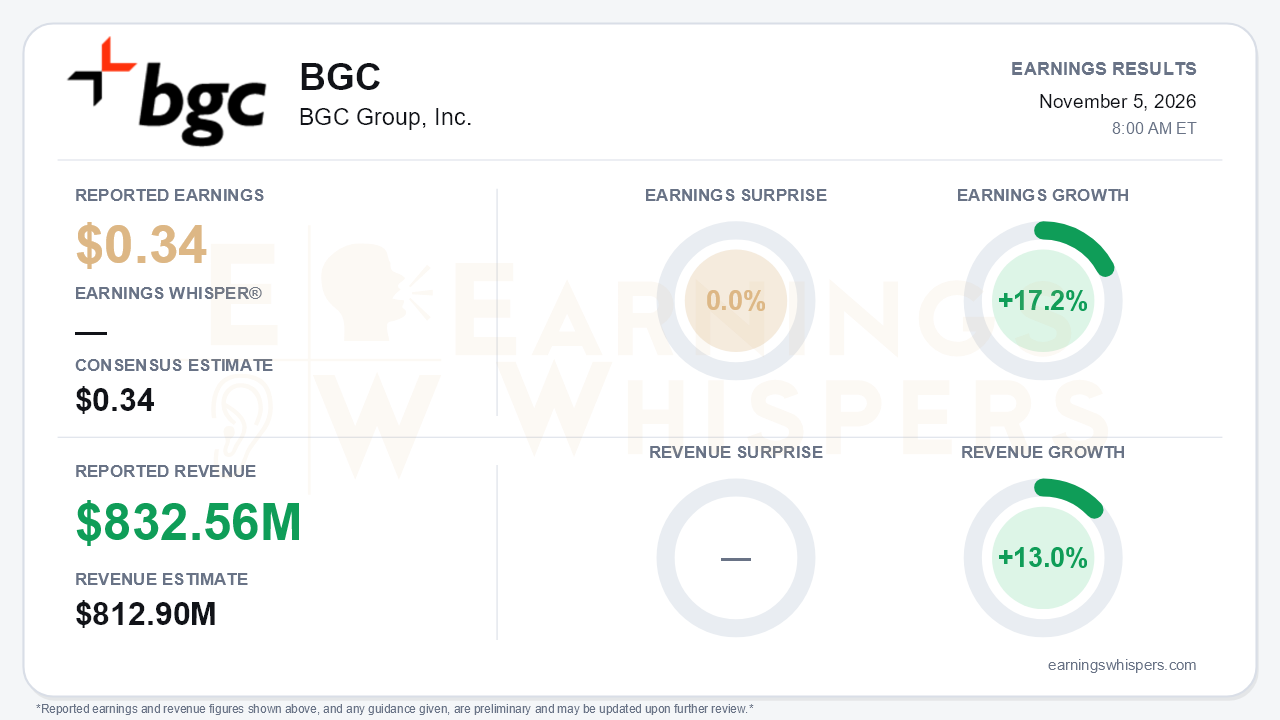
BGC Group's third-quarter EPS matched expectations, but the business underneath reaccelerated. The company reported earnings of $0.34 per share, exactly in line with consensus, on revenue of $832.56 million, which beat the $812.9 million estimate by 2.4%. Earnings grew 17.2% year over year and revenue rose 13.0%. Revenue growth nearly doubled from the 7.8% pace in the second quarter, and it landed near the top of management's $775-835 million guidance range. The central tension is that investors turned noticeably more pessimistic heading into a quarter that showed broadening growth and expanding margins.
The press release itself was a bare-bones notice. It pointed investors to the full results posted on the company's website and declared the usual 2-cent quarterly dividend. The substance came from the call. Pre-tax adjusted earnings rose 20.9% to $187.5 million, in the upper half of the $172-190 million guide. Pre-tax margin improved to roughly 22.5% from about 21.1% a year ago, and adjusted EBITDA jumped 48.9% to $249.5 million. Per-share earnings grew more slowly than pre-tax adjusted earnings, at 17.2% versus 20.9%, and that gap helps explain why the bottom line looked merely in line. Even so, incremental margin rose to 33.9% from 31.3% in the second quarter, which suggests the added revenue is converting to profit more efficiently.
The reacceleration was broad. Energy, commodities and shipping revenue grew 18.8%, up from 5.3% in the prior quarter, as shipping, environmental and biodiesel activity offset weaker refined products. Equities surged 28% after just 2.8% growth in the second quarter. Rates grew 12.4% and FX grew 13.9%. FMX was the standout:
- U.S. Treasury market share reached 42%, up from 37% a year ago.
- Cash Treasury average daily volume hit a third-quarter record of $83 billion.
- After the full Treasury futures curve was listed in August, futures volume topped 80,000 contracts a day, roughly seven times last year's level, and reached 112,000 in September.
- FMX FX volume grew 43%, Fenix growth platforms grew 39.8% and Lucera grew 28%. All three accelerated from the second quarter.
Bears still have legitimate ammunition. Credit was the only declining brokerage asset class, falling 2.5% after gains of 5.4% in the second quarter and 8.2% in the first. Other revenues dropped 19.7% on the logistics wind-down and lower interest income. Portfolio Match volume growth slowed to 34% from 82%. Refined-product volumes were hurt by disruption tied to the Iran conflict and the Strait of Hormuz, which could shift the energy mix once conditions normalize. Management also acknowledged that AI and electronification compress broker compensation and pricing over time. That admission cuts both ways, since BGC simultaneously highlighted its first fully AI-brokered institutional trade. Co-CEO JP Aubin will step down at year end to become Vice Chairman, leaving a two co-CEO structure.
Guidance kept the growth story intact without stretching it. Fourth-quarter revenue is guided to $805-865 million, about 10% growth at the midpoint, with pre-tax earnings of $178-196 million, about 16% growth. That implies roughly 18% revenue growth and 23% earnings growth for the full year. Those figures sit slightly below the 19% and 24% nine-month rates implied on the prior call, but the difference reflects a tougher fourth-quarter comparison rather than a cut. The first quarter's 44% revenue growth, boosted by OTC activity, remains the year's high-water mark. Other supportive items included:
- Credit rating upgrades from Kroll (BBB+) and JCRA (A-).
- Liquidity recovering to $917.3 million from $861.4 million, though still below $979.1 million at year-end 2025.
- Early onboarding of hyperscalers and neoclouds for compute markets, which management said is not yet meaningful to revenue.
The market setup is more complicated than the in-line print implies. Investor sentiment fell from -0.10 to -0.47 since the prior report, a meaningful deterioration deeper into negative territory. Shares were $11.27 in the latest snapshot, down 6.6% from the $12.07 open after the July report. That price sits about 3.6% above the 200-day moving average of $10.88. It is also roughly 10% below the September 11 inter-earnings high of $12.51 and about 11% above the August 12 low of $10.13. The stock has given back much of its late-summer rally without breaking its longer-term trend. The Earnings Whispers trend signals are mixed, with momentum positive while AVWAP remains negative.
The bottom line is that BGC delivered a better quarter than its in-line EPS suggests. Revenue growth reaccelerated, margins widened, FMX gained real traction in futures and Treasuries, and fourth-quarter guidance points to continued double-digit growth. The risks are real but mostly contained: softening credit, refined-product disruption, a co-CEO transition and long-run AI pricing pressure. With sentiment sharply weaker and shares sitting mid-range, expectations appear to have reset lower even as operating trends improved.
Read our earnings preview for BGC Group, Inc.: https://www.earningswhispers.com/article/BGC/22053
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 11 hours | |
| 15 hours | |
| 16 hours | |
| Nov-03 | |
| Oct-28 | |
| Oct-19 | |
| Oct-14 | |
| Sep-30 | |
| Sep-30 | |
| Sep-28 | |
| Sep-10 | |
| Aug-20 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 |
